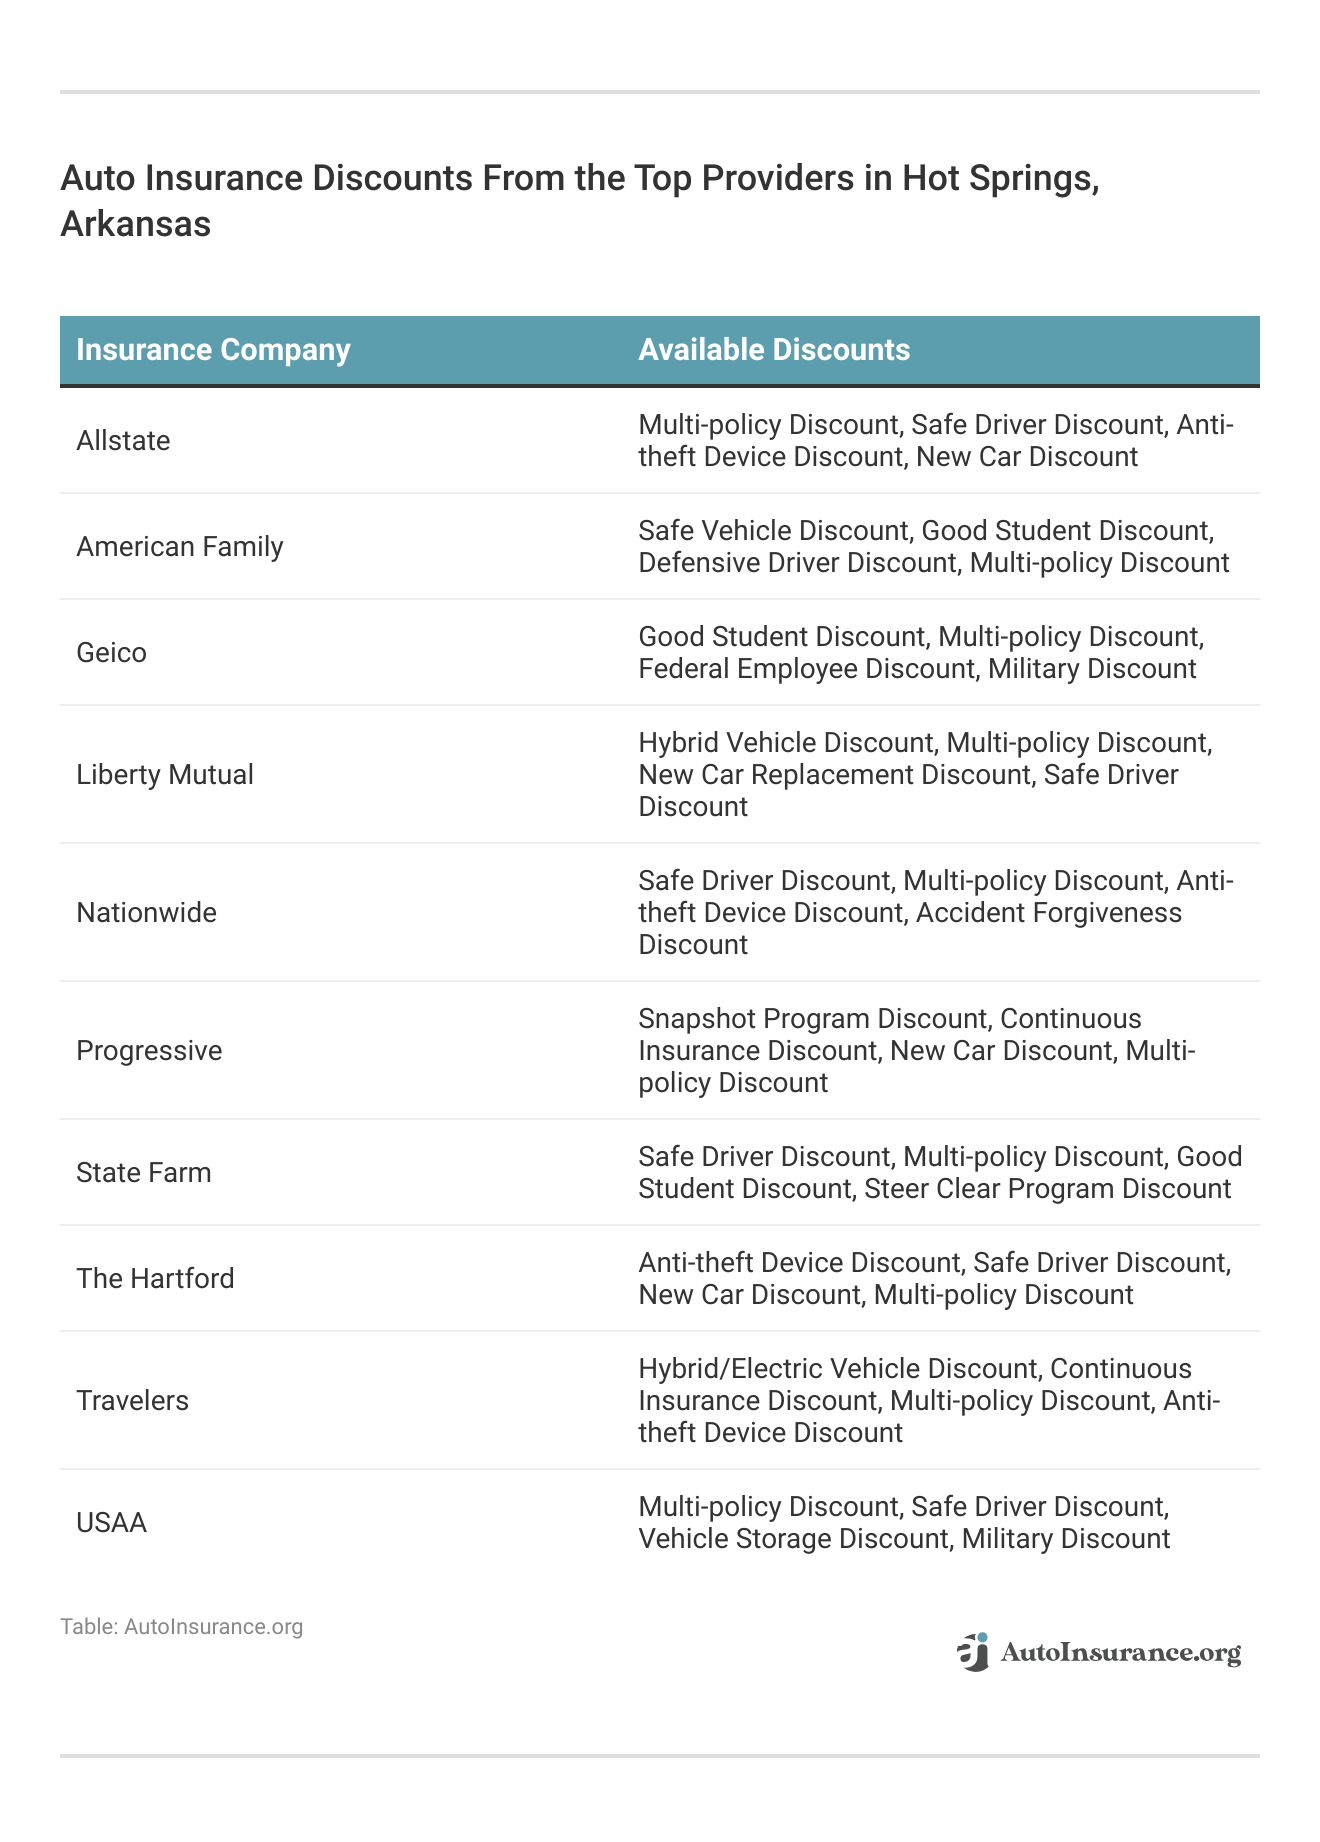
Auto insurance companies serving Blue Springs, Missouri, offer a range of coverage options tailored to state-mandated minimums and local driving conditions. Determining if these providers are "worth the hype" depends on balancing Missouri’s specific legal requirements, individual risk factors such as your driving history and vehicle type, and the quality of customer service provided by regional and national carriers.
Understanding the Landscape of Auto Insurance in Blue Springs
Blue Springs, located within the Kansas City metropolitan area, presents a unique set of circumstances for motorists. As a suburb with a significant amount of commuting traffic flowing into and out of the city, the density of vehicles on the road influences the risk profile for insurance carriers. When residents evaluate whether companies are "worth the hype," they are often weighing marketing promises—such as low rates, rapid claims processing, or advanced mobile app integration—against the reality of their premium costs and coverage reliability.
In Missouri, insurance is regulated at the state level by the Department of Commerce & Insurance (DCI). This agency ensures that the companies operating within Blue Springs maintain the financial solvency necessary to pay claims and adhere to state laws regarding policy cancellation and non-renewal. Because these companies must comply with state regulations, the "hype" usually refers to non-mandatory services, such as accident forgiveness, vanishing deductibles, or personalized agent support. To determine if these perks are worth the extra cost, residents must look past the advertising campaigns and examine the technical merits of their policy offerings.
Missouri Mandatory Liability Requirements
Before considering optional "hype" features, drivers must ensure they meet the baseline requirements set by the state of Missouri. As of 2026, the Missouri Department of Revenue mandates that all drivers maintain "financial responsibility." The most common way to satisfy this is through a standard automobile liability insurance policy.
The minimum limits are often referred to as "25/50/25" coverage:
- $25,000 for bodily injury to one person in any one accident.
- $50,000 for total bodily injury to all persons in any one accident.
- $25,000 for property damage in any one accident.
If you are paying higher premiums for a policy that exceeds these limits, you are essentially paying for protection against personal financial ruin in the event of a significant lawsuit. In this context, the "worth" of an insurance company is measured not by marketing, but by the strength of its legal defense team and its willingness to pay out claims up to your policy limits without excessive disputes.
Evaluating the "Hype": Marketing vs. Technical Value
Insurance companies invest millions in national advertising, focusing on slogans like "Name Your Price" or "Bundling Discounts." For a resident of Blue Springs, these marketing efforts are designed to create a sense of brand familiarity. However, the value of an insurer is technical. You should evaluate companies based on objective criteria:
- Claims Handling Efficiency: Look for companies with high ratings from independent organizations like the National Association of Insurance Commissioners (NAIC). A company might be cheap to join, but if they are notoriously difficult to work with when you need to file a claim, they are not worth the hype.
- Financial Stability Ratings: Check A.M. Best or similar ratings for the insurance providers you are considering. You want a company that will still be in business if a major catastrophe, such as a severe storm or a city-wide hail event, results in thousands of simultaneous claims.
- Local Agent Accessibility: Many consumers prioritize having a brick-and-mortar office in or near Blue Springs. If you prefer to speak to a human face-to-face when navigating the complexities of a policy renewal or an accident report, local agencies provide genuine value that digital-only carriers cannot match.
Factors Influencing Your Premium in Blue Springs
When you solicit quotes from insurers, the "hype" around their advertised low rates often disappears when the actual quote is generated. This is because premiums are calculated based on proprietary underwriting algorithms that weigh specific, measurable risks.
- Commute Distance: Living in Blue Springs but working in downtown Kansas City increases your time on the road, which statistically increases your risk of involvement in an accident.
- Vehicle Safety Features: Modern vehicles equipped with autonomous emergency braking, lane departure warnings, and sophisticated telematics can sometimes qualify for discounts.
- Credit-Based Insurance Scores: In Missouri, insurers are permitted to use credit history as a factor in determining premiums. This practice is often a point of contention, but it remains a primary driver of cost differences between companies.
- Driving Record: Traffic violations, including speeding tickets issued on the I-70 corridor or local arterial roads like Highway 7, will impact your rates for several years.
Comparative Analysis of Insurance Service Models
The following table summarizes the primary models of insurance available to Blue Springs residents, helping you determine which structure aligns with your personal needs.
| Service Model | Primary Benefit | Potential Trade-off | Best For |
|---|---|---|---|
| National Mutuals | High brand recognition; extensive digital tools. | Can feel impersonal; claims may be centralized. | Tech-savvy drivers seeking mobile convenience. |
| Local Independent Agents | Personalized advice; advocacy during claims. | May have limited underwriting authority. | Drivers with complex coverage or multi-policy needs. |
| Direct-to-Consumer | Typically lower premiums due to lower overhead. | No local support; self-service requirements. | Price-conscious consumers with simple needs. |
| High-Risk/Specialty | Coverage for drivers with poor records/SR-22. | Significantly higher premiums. | Drivers denied by standard carriers. |
Why "Cheapest" Is Often Not "Best"
A common mistake among consumers is equating the "worth" of an insurance company solely with the lowest monthly premium. In the insurance industry, price is often a reflection of the risk pool the company is targeting. A company that consistently advertises the lowest rates may also have more stringent requirements for claims approval or may utilize a highly automated, "low-touch" customer service model that can be frustrating during a crisis.
If you are involved in an accident in Blue Springs, the value of your policy is tested at the moment of the collision. An insurer that provides 24/7 access to local adjusters, a network of preferred repair shops in Jackson County, and a clear, transparent claims portal is generally worth the higher premium compared to a budget provider that outsources its customer support to third-party call centers.
When to Switch Insurance Providers
"The hype" often suggests that changing insurance companies frequently is the secret to saving money. While shopping for rates every renewal period can yield savings, frequent switching can sometimes lead to a "loyalty discount" loss or potential gaps in coverage.
You should consider switching if:
- Significant Life Events: Changes such as marriage, moving to a different ZIP code within Blue Springs, or adding a new driver to your household significantly alter your risk profile.
- Consistent Rate Increases: If your current carrier raises premiums without a corresponding change in your driving record or risk level, it is time to benchmark your rate against competitors.
- Claims Dissatisfaction: If you have experienced a claim and felt the service was inadequate, the "brand loyalty" you feel is no longer serving your financial or emotional interest.
Frequently Asked Questions
1. Does Blue Springs have unique insurance risks compared to other Missouri cities? Blue Springs faces typical suburban risks, including commuting congestion and severe weather events common to the Midwest. Hail and wind damage are significant concerns for physical damage coverage, which is a component of comprehensive auto insurance.
2. Are local independent agents in Blue Springs better than national call centers? Local agents act as intermediaries between you and the insurance company. They can provide guidance on specific local regulations and advocate on your behalf during the claims process, which is often superior to speaking with a randomized call center representative.
3. Does my credit score really affect my auto insurance rate in Missouri? Yes. Missouri law allows insurers to use insurance-based credit scores to determine premiums. Carriers argue that this is a statistically significant indicator of the likelihood of future claims, though it remains a controversial practice.
4. How can I verify if an insurance company is authorized to do business in Missouri? You should visit the Missouri Department of Commerce & Insurance (DCI) website. Their online search tools allow you to verify the licensure status of any insurance carrier operating within the state.
5. Is "Full Coverage" a standard term I should look for? "Full coverage" is a marketing term, not a technical insurance definition. It usually refers to a combination of liability, collision, and comprehensive coverage. Always read the policy declarations page to see exactly what is covered, as "full" is subjective and can exclude items like rental car reimbursement or roadside assistance.
Next Steps for Consumers
To determine if your current insurance company is truly worth the investment, take these three practical steps:
- Review your Declarations Page: Do not look at your bill; look at your policy. Ensure your liability limits are sufficient to protect your personal assets. If you have significant savings or a high-value home, consider increasing your liability limits—the cost of doing so is often surprisingly low.
- Conduct a Multi-Carrier Quote Comparison: Use a neutral, third-party comparison tool or reach out to an independent local agent in Blue Springs. Request quotes that mirror your current coverage levels to get an "apples-to-apples" price comparison.
- Check for "Hidden" Discounts: Contact your current provider and ask specifically about discounts you may not be receiving, such as safe driver discounts, defensive driving course credits, or multi-policy bundles that you may have missed during sign-up.
By focusing on the technical quality of the policy and your specific protection needs rather than brand slogans, you can cut through the noise and ensure your insurance coverage provides genuine, reliable value.