Common stocks serve as a primary vehicle for long-term capital appreciation and dividend income, while life insurance functions as a critical risk management tool providing financial security for beneficiaries. Integrating both allows for a balanced approach to wealth accumulation and estate protection, ensuring that growth objectives are met without compromising the financial stability of survivors in the event of an untimely death.
The Strategic Role of Common Stocks in 2026
Common stocks represent a share of ownership in a corporation. As an asset class, they have historically outperformed most other investment vehicles over long durations. In the economic landscape of 2026, where digital transformation and sustainable energy continue to drive market volatility and opportunity, understanding the specific advantages of common stocks is essential for any diversified portfolio.
Potential for Significant Capital Appreciation
The primary allure of common stocks is the potential for capital gains. When a company grows its earnings, expands its market share, or innovates successfully, the value of its shares typically rises. Unlike fixed-income assets such as bonds, which return a set interest rate and the original principal, common stocks have theoretically unlimited upside.
Investors who hold shares in high-growth sectors—such as artificial intelligence, biotechnology, or renewable energy—may see their initial investments multiply several times over a decade. This growth is a fundamental requirement for outpacing inflation, which can erode the purchasing power of cash and low-yield savings accounts.
Passive Income through Dividend Payments
Many established corporations distribute a portion of their profits to shareholders in the form of dividends. For common stockholders, this represents a steady stream of passive income. In 2026, "dividend aristocrats"—companies that have consistently increased their payouts for decades—remain highly sought after by retirees and those seeking to reinvest income to trigger the power of compounding.
Dividends provide a cushion during market downturns. Even if a stock's price remains flat or dips slightly, the dividend yield ensures that the investor still receives a tangible return on their capital. Reinvesting these dividends allows an investor to purchase more shares, which in turn generates more dividends, creating a "snowball effect" for wealth creation.
Liquidity and Market Accessibility
Common stocks are among the most liquid assets available. Most shares in major companies can be bought or sold within seconds during market hours through electronic exchanges. This liquidity provides investors with the flexibility to move into cash or pivot their strategy quickly if their financial needs change.
Furthermore, the barrier to entry has never been lower. Fractional share trading and the prevalence of zero-commission brokerage platforms in 2026 allow individuals to begin investing with as little as a few dollars. This democratization ensures that common stock ownership is not reserved for the wealthy, but is accessible to anyone with a smartphone and a basic understanding of the markets.
Voting Rights and Corporate Governance
As a common stockholder, you typically possess voting rights on corporate policy and the election of the board of directors. While a retail investor holding a few hundred shares may feel their influence is minimal, these rights are a fundamental component of shareholder democracy. They allow investors to have a voice in major company decisions, such as mergers, acquisitions, and executive compensation packages.
The Multi-Faceted Nature of Life Insurance
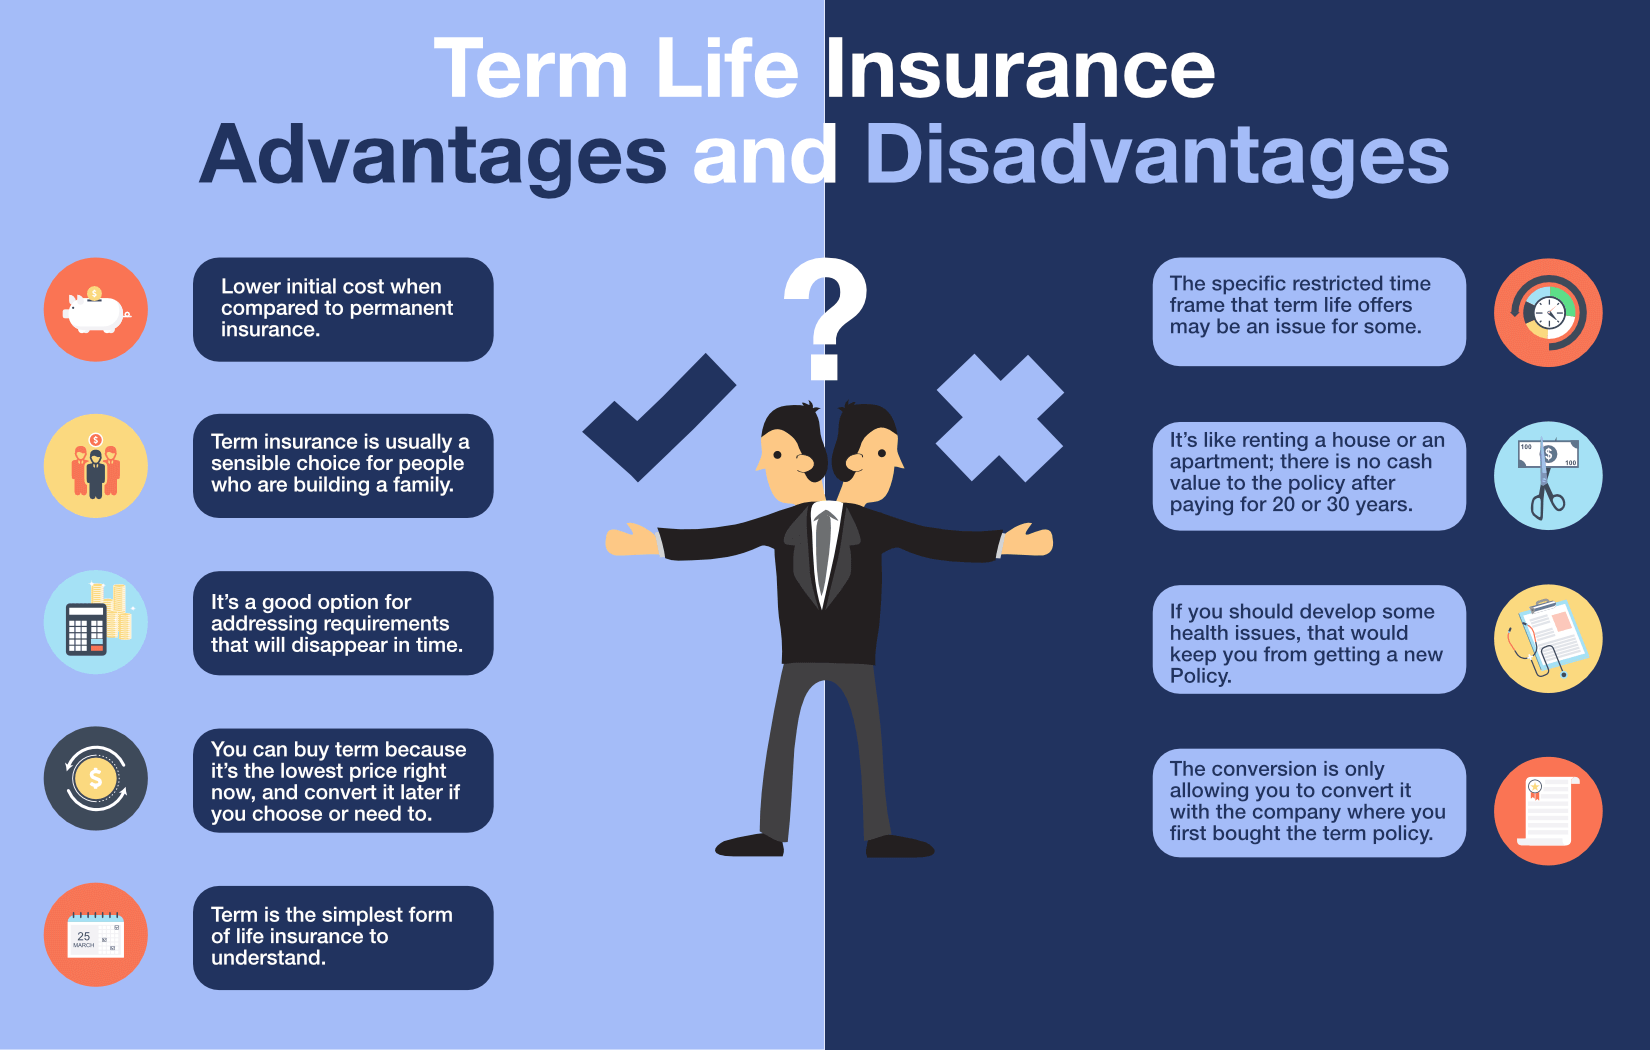
Life insurance is often misunderstood as a simple "death benefit," but it is a sophisticated financial instrument with various types designed for different goals. To evaluate it fairly, one must distinguish between term life insurance, which provides coverage for a specific period, and permanent life insurance (such as Whole Life or Universal Life), which includes a savings or investment component.
The Advantages of Life Insurance
The value proposition of life insurance extends beyond the payout to beneficiaries. It serves as a cornerstone of estate planning and a unique tax-advantaged asset.
Immediate Financial Protection for Beneficiaries
The most significant advantage of life insurance is the immediate creation of an "estate" for your heirs. Upon the death of the insured, the policy pays out a lump sum (the death benefit) to named beneficiaries. This money can be used to replace lost income, pay off a mortgage, cover funeral expenses, or fund a child’s education. In 2026, with the cost of living and education remaining high, this safety net prevents a family's financial ruin during an emotionally devastating time.
Tax-Free Death Benefits
Under current tax laws (IRC Section 101(a)), life insurance death benefits are generally paid to beneficiaries free of federal income tax. This is a massive advantage compared to other assets, such as traditional IRAs or 401(k)s, where beneficiaries may owe significant income taxes on the distributions they receive. This tax efficiency makes life insurance an ideal tool for passing wealth to the next generation.
Cash Value Accumulation and Tax-Deferred Growth
Permanent life insurance policies feature a cash value component that grows over time. A portion of each premium payment is funneled into this account, where it earns interest or tracks a market index (as in Indexed Universal Life). The growth within this cash value account is tax-deferred, meaning you do not pay taxes on the gains as they accumulate.
In 2026, many high-net-worth individuals use the cash value of life insurance as a "volatility buffer." When the stock market is down, they can withdraw or borrow against their policy's cash value instead of selling stocks at a loss, providing a strategic source of liquidity.
Policy Loans and Liquidity
Most permanent policies allow the policyholder to take out loans against the cash value. These loans are often easier to obtain than traditional bank loans because the policy's cash value serves as collateral. These loans do not require credit checks and often carry competitive interest rates. If structured correctly, the money can be used for any purpose—business capital, home down payments, or emergency expenses—without triggering a taxable event.
The Disadvantages of Life Insurance
Despite its benefits, life insurance is not without its drawbacks, particularly when viewed through the lens of investment efficiency and cost.
High Premium Costs for Permanent Policies
One of the primary disadvantages is the high cost of permanent life insurance compared to term life. Premiums for whole life or universal life can be five to ten times higher than for a term policy with the same death benefit. For many families, this high cost can lead to "under-insurance," where they buy a smaller permanent policy because it is all they can afford, leaving their family with insufficient coverage.
Complexity and Opaque Fee Structures
Life insurance contracts, especially those with investment components like Variable Universal Life (VUL), can be incredibly complex. They often come with various fees, including:
- Mortality and Expense (M&E) Risks: Charges to cover the insurance company's risk.
- Administrative Fees: Monthly costs to maintain the policy.
- Surrender Charges: Hefty fees applied if you cancel the policy within the first 10 to 15 years.
- Cost of Insurance (COI): The actual price of the death benefit, which typically increases as the insured gets older.
These fees can significantly eat into the "investment" portion of the policy, often resulting in lower net returns than if the individual had simply invested in common stocks directly.
Opportunity Cost
When you pay high premiums for a permanent life insurance policy, you are committing capital that could have been invested elsewhere. Historically, a "buy term and invest the difference" strategy—where an individual buys an inexpensive term policy and puts the saved premium money into a low-cost stock index fund—often results in a higher total net worth over 20 to 30 years. The opportunity cost of the higher premiums and the lower internal rate of return in many insurance products is a major deterrent for savvy investors.
Inflation Risk for Fixed Death Benefits
If you buy a policy with a fixed death benefit today, that amount will have significantly less purchasing power in twenty years. Unless the policy has an "inflation rider" or is a participating policy that uses dividends to increase the death benefit, the real value of the protection declines every year.
Comparing Common Stocks and Life Insurance
The following table highlights the fundamental differences between these two financial tools to help in decision-making.
| Feature | Common Stocks | Life Insurance (Permanent) |
|---|---|---|
| Primary Goal | Wealth creation and growth | Risk protection and estate planning |
| Growth Potential | High (Market-driven) | Moderate (Fixed or indexed rates) |
| Liquidity | High (Sell shares anytime) | Moderate (Accessible via loans/surrender) |
| Tax Status | Capital gains and dividends taxed | Tax-deferred growth; Tax-free death benefit |
| Risk Level | High (Market volatility) | Low to Moderate (Carrier solvency dependent) |
| Ongoing Costs | Minimal (Brokerage fees/Expense ratios) | High (Premiums and internal fees) |
| Complexity | Low to Moderate | High |
| Guarantees | None (Principal can be lost) | Often includes guaranteed minimum returns |
Strategic Integration: How to Balance Both
For a robust financial plan in 2026, it is rarely a matter of choosing one over the other. Instead, the goal is to use each tool for its specific strength.
- Foundation of Protection: Start with life insurance to ensure your family is protected against the loss of your income. For most people, this means starting with a high-limit term life policy.
- Growth Engine: Once protection is in place, maximize contributions to common stocks through tax-advantaged accounts like 401(k)s or IRAs. This provides the growth necessary for retirement.
- Advanced Tax Planning: For high earners who have already maximized their traditional investment accounts, permanent life insurance can serve as a "shadow IRA," providing a location for additional tax-advantaged savings and estate liquidity.
- The "Volatility Buffer": Using the cash value of life insurance alongside a stock portfolio allows an investor to be more aggressive with their stock picks, knowing they have a stable, non-correlated asset to draw from if the market enters a prolonged bear cycle.
Common Mistakes to Avoid
- Treating Life Insurance as Your Only Investment: Because of the high fees and lower returns, relying solely on insurance for retirement usually results in a shortfall.
- Neglecting Volatility in Stocks: Investors often overestimate their risk tolerance. Without the "anchor" of insurance or bonds, a market crash can lead to panic selling.
- Ignoring the Fine Print: Many life insurance policies in 2026 feature "caps" and "participation rates" on indexed gains. Failing to understand these can lead to disappointment when the market booms but your policy only gains a fraction of that growth.
- Overlooking Beneficiary Designations: Both stocks in brokerage accounts and life insurance policies require clear beneficiary designations. Failure to update these after a marriage, divorce, or birth can lead to lengthy legal battles in probate court.
Frequently Asked Questions
Can I lose money in common stocks?
Yes. Unlike a savings account or some insurance products, the principal invested in common stocks is not guaranteed. If the company performs poorly or the overall market declines, the value of your shares can drop significantly, potentially to zero if the company goes bankrupt. This is why diversification—owning many different stocks across different sectors—is a critical risk management strategy.
Is life insurance a good investment for a young person?
Life insurance is generally cheapest when you are young and healthy. However, if you have no dependents and no debt that someone else would be responsible for, the "investment" value of a permanent policy may be lower than the returns you could get by investing in common stocks. For most young people, a small term policy for final expenses combined with aggressive stock investing is the most efficient path.
How do I access the cash value in my life insurance policy?
You can access cash value through a withdrawal, a policy loan, or by surrendering the policy entirely. Withdrawals are usually tax-free up to the amount of premiums paid (your "basis"). Loans are not taxed as long as the policy remains in force. However, any unpaid loan balance will be deducted from the death benefit when you pass away, and if the policy lapses with a loan outstanding, it could trigger a significant tax bill.
What is the "Rule of 72" in the context of stock investing?
The Rule of 72 is a simple formula used to estimate how long it will take for an investment to double at a fixed annual rate of interest. By dividing 72 by the annual rate of return, investors can get a rough estimate of years for doubling. For example, if a stock portfolio returns 8% annually, the investment will double in approximately 9 years (72 / 8 = 9). This highlights the advantage of the higher growth rates typically found in common stocks compared to the more conservative growth in insurance products.
Does common stock provide any protection during a recession?
Generally, common stocks are hit hard during recessions as corporate earnings decline. However, certain "defensive" stocks—such as those in utilities, healthcare, and consumer staples—tend to hold their value better than cyclical stocks like travel or luxury goods. Life insurance, conversely, remains unaffected by market recessions (unless it is a variable policy), providing a stable financial anchor when stock values are depressed.
Practical Next Action
To optimize your financial position, perform a "gap analysis." First, calculate your family's total financial need (mortgage, education, debt, and income replacement) and compare it to your current life insurance coverage. If there is a gap, secure additional term life insurance immediately. Once protected, review your investment portfolio to ensure you have sufficient exposure to common stocks—preferably through low-cost index funds or ETFs—to meet your long-term retirement goals. If you are in a high tax bracket and have exhausted other options, consult with a financial advisor to see if the tax-advantaged growth of a permanent life insurance policy fits your estate plan.
Disclaimer: This information is for educational purposes only and does not constitute professional financial, legal, or tax advice. Financial regulations and tax laws are subject to change and vary by jurisdiction.