Finding the single best home and auto insurance bundle in Michigan depends on balancing comprehensive coverage, competitive multi-policy discounts, and strong claims satisfaction across the state's unique regulatory environment. While no single company universally ranks first for every resident, Auto-Owners Insurance consistently emerges as the top-rated provider for bundling home and auto coverage in Michigan, scoring highest for overall customer satisfaction, localized agent networks, and robust policy customization.
Navigating the insurance market in the Great Lakes State requires an understanding of Michigan's distinct auto insurance laws, weather-related property risks, and the financial mechanics of multi-policy bundling. This guide examines why top-tier carriers stand out, how bundling works under Michigan regulations, and what you need to evaluate before purchasing a combined policy.
Understanding Michigan’s Unique Insurance Landscape
Michigan features one of the most dynamic and regulated insurance environments in the United States. Residents face distinct legal mandates for auto coverage alongside localized property risks that influence premium calculations for both homeowners and drivers.
Auto Insurance Framework
Michigan operates under a choice system for Personal Injury Protection (PIP) medical benefits, following major legislative overhauls. Drivers can select various levels of medical coverage, ranging from unlimited lifetime benefits to opting out entirely if they have qualifying health insurance. Additionally, Michigan is a comparative fault state with a tort system, meaning drivers must carry bodily injury and property damage liability limits to protect against lawsuits arising from auto accidents.
Home Insurance Considerations
On the property side, Michigan homeowners face severe seasonal weather patterns. Winter brings heavy lake-effect snow, freezing temperatures, and ice dams that can compromise roofs and plumbing. Spring and summer introduce severe thunderstorms, straight-line winds, and localized flooding. Insurance carriers factor these regional perils into their underwriting models, making windstorm deductibles and water backup endorsements critical components of any comprehensive homeowners policy.
Why Auto-Owners Insurance Earns Top Marks for Bundling in Michigan
When evaluating independent industry data, consumer satisfaction surveys from J.D. Power, and financial strength ratings from AM Best, Auto-Owners Insurance frequently leads the Michigan market for bundled policies. Headquartered in neighboring Lansing, Michigan, the company maintains a deep understanding of local risks and operates through a dedicated network of independent insurance agents.
Key Advantages of an Auto-Owners Bundle
- Discounts for Multi-Policy Holders: Combining home and auto policies unlocks substantial percentage discounts on both premiums, often reducing the individual baseline costs significantly.
- Local Independent Agency Model: Policies are serviced by local agents who understand Michigan's regional weather nuances and regulatory requirements, ensuring personalized policy structuring.
- Broad Form and Endorsement Options: Auto-Owners offers unique endorsements such as water backup protection, guaranteed home replacement cost, and personalized car equipment coverage that can be seamlessly added to a bundled package.
- Claim Handling Reputation: The company consistently scores above industry averages in customer satisfaction indexes regarding claims processing speed, transparency, and fairness.
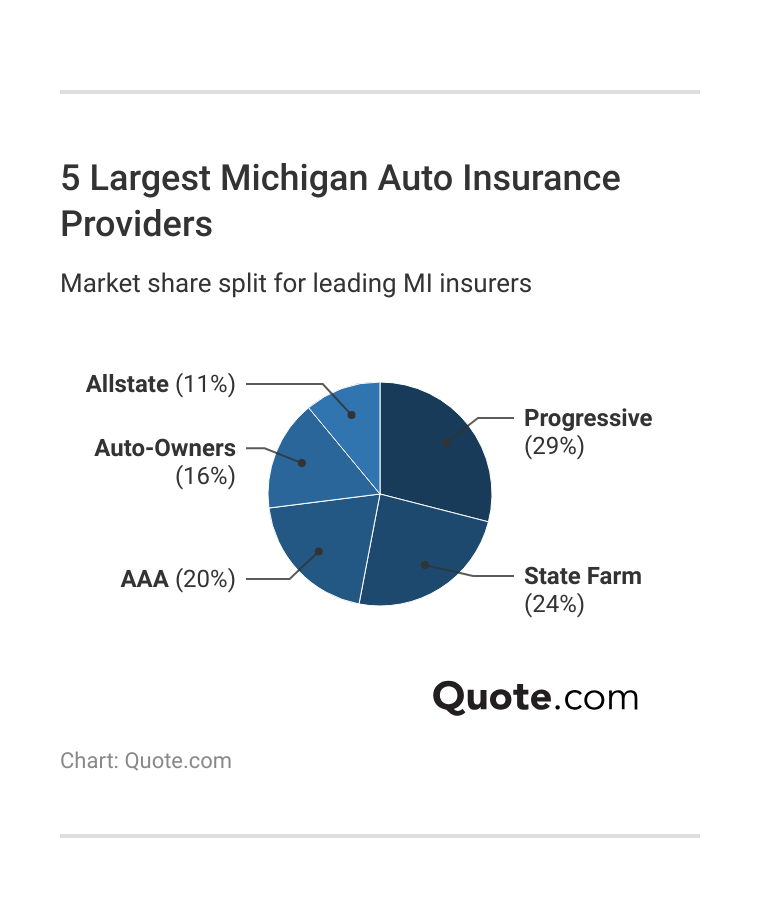
Evaluating Alternative Top Contenders in Michigan
While Auto-Owners stands out for localized service and comprehensive bundling perks, several national carriers also command significant market share and competitive pricing across Michigan.
Progressive
Progressive is renowned for its user-friendly digital tools, name-your-price tool, and competitive bundling rates. While they frequently rank high for tech-forward policy management, their claims handling is often decentralized compared to regional mutual insurers.
State Farm
As a massive national writer with a heavy agent presence in Michigan, State Farm offers reliable bundling discounts and excellent financial stability. Their rates can be highly competitive for drivers with clean records, though homeowners rates may vary significantly depending on the county and proximity to coastal or high-wind zones.
Allstate
Allstate provides robust bundling options paired with accident forgiveness and safe driving rewards. However, baseline rates in urban areas like Detroit can sometimes trend higher than regional alternatives, making quotes highly dependent on ZIP code.
Comparing Michigan Home and Auto Bundling Options
To help visualize how top carriers compare across key decision factors for Michigan residents, review the structural comparison below.
| Insurance Carrier | Primary Strength in Michigan | Typical Bundling Advantage | Agency Model | Financial Strength (AM Best) |
|---|---|---|---|---|
| Auto-Owners Insurance | Local claims service, customization | High multi-policy percentage savings | Independent Agents | A++ (Superior) |
| State Farm | Extensive physical agent network | Consistent bundling credits | Captive Agents | A++ (Superior) |
| Progressive | Digital tools, online quote transparency | Competitive initial pricing | Independent & Direct | A+ (Superior) |
| Allstate | Rewards programs, vanishing deductible | Substantial package discounts | Exclusive Agents | A+ (Superior) |
Financial Mechanics: How Multi-Policy Bundling Saves Money
Insurance carriers reward customer loyalty and risk diversification by offering multi-policy discounts. When you purchase both your homeowners and auto insurance from the same company, the insurer mitigates its operational acquisition costs and secures a larger share of your wallet.
In Michigan, bundling can reduce your combined annual premiums by anywhere from 10% to 25%, depending on the carrier, your credit score, driving history, and the age and construction type of your home. However, it is vital to look past the headline discount percentage. A company offering a 25% discount on an inflated baseline rate may still cost more than a competitor offering a 10% discount on a lower base rate. Always compare the net premium total rather than the discount percentage alone.
Step-by-Step Guide to Securing the Best Bundle
Finding and locking in the optimal home and auto bundle requires a methodical approach. Follow these steps to ensure comprehensive coverage without overpaying:
- Audit Your Current Coverage: Review your existing declarations pages. Note your current liability limits, deductibles, and any specific endorsements (like umbrella insurance or scheduled jewelry riders) that must be matched or improved.
- Gather Property and Vehicle Details: Compile your Vehicle Identification Numbers (VINs), annual mileage estimates, home square footage, roof age, security system details, and recent home improvement receipts.
- Obtain Multiple Quotes: Work with an independent insurance broker who can pull quotes from Auto-Owners, State Farm, Progressive, and other regional carriers simultaneously, or request quotes directly from top providers.
- Normalize Deductibles and Limits: Ensure every quote you compare features identical liability limits and deductible structures (e.g., matching $500,000 liability limits and $1,000 deductibles) so you are performing an accurate apples-to-apples comparison.
- Review Financial Strength Ratings: Verify that any carrier you consider holds an AM Best rating of "A" (Excellent) or higher to guarantee their capacity to pay out major claims.
- Finalize the Effective Dates: Coordinate the start dates of your new bundled policies to ensure zero coverage gaps, and contact your previous insurers to formally cancel old policies only after the new ones are active.
Common Mistakes to Avoid When Bundling Insurance
Policyholders often make critical errors when switching to a bundled package in pursuit of convenience or a lower monthly payment.
- Sacrificing Coverage for Price: Lowering auto liability limits or selecting actual cash value (ACV) instead of replacement cost for your home can expose you to catastrophic financial loss after an accident or property disaster.
- Ignoring Michigan PIP Choices: When bundling auto insurance, ensure you carefully evaluate your PIP medical selection. Blindly accepting minimum limits without understanding your health insurance coordination can leave medical bills exposed in a serious crash.
- Forgetting About Endorsements: Standard policies often exclude water backup, sewer backup, or ordinance or law coverage. Ensure your bundled homeowners policy includes these critical riders.
- Failing to Re-shop Periodically: Insurance rates shift based on claims data, inflation, and credit scoring changes. Re-evaluate your bundled policy every two to three years to ensure your carrier remains competitive.
Frequently Asked Questions
Does bundling home and auto insurance always save money?
In the vast majority of cases, bundling yields a lower combined cost than purchasing policies from separate providers. However, if you have a high-risk driving record or an older home in an area prone to severe storm claims, a specialty carrier focused solely on auto or home might occasionally underprice a bundled competitor. Always compare standalone quotes against bundled packages.
How does Michigan’s auto no-fault reform affect my home insurance bundle?
Michigan’s auto reform changed personal injury protection (PIP) options, allowing drivers to select lower medical coverages if they have qualified health coverage. While auto reform directly impacts auto premiums, it does not alter homeowners insurance regulations. However, many carriers offer enhanced multi-policy discounts if you purchase both policies, regardless of your chosen PIP medical tier.
Can I bundle my auto policy if I rent an apartment or own a condo instead of a house?
Yes. Most major insurance carriers offer multi-policy discounts for combining renters insurance or condo insurance with an auto policy. While the absolute dollar savings may be smaller than a traditional homeowners bundle, the percentage discount on the auto policy often remains substantial.
What should I do if my home is older or has a roof over 15 years old?
Older homes can complicate bundling because insurers frequently require a home inspection before binding coverage. If your roof is past its prime, some carriers may decline the home portion or require roof replacement as a condition of the bundle. Working with an independent agent is especially helpful in these scenarios, as they can place difficult properties with regional mutuals that offer more flexible underwriting.
Will filing a claim on my auto policy cause my home insurance rates to increase?
Generally, filing a claim on one policy within a bundle should not automatically trigger a rate increase on the other policy unless the underlying risk profile changes significantly (such as multiple at-fault accidents or repeated property claims). However, composite rating systems used by some modern insurers can occasionally factor overall household loss history into renewal pricing.
Next Actions for Michigan Homeowners and Drivers
To secure the best home and auto insurance bundle in Michigan, start by requesting comparative quotes through an independent insurance agency that represents top-rated regional carriers like Auto-Owners alongside national options. Verify that your liability limits, deductibles, and property endorsements provide true financial protection rather than just the lowest monthly payment. Review your declarations pages annually to maintain optimal coverage as your assets and personal circumstances evolve.