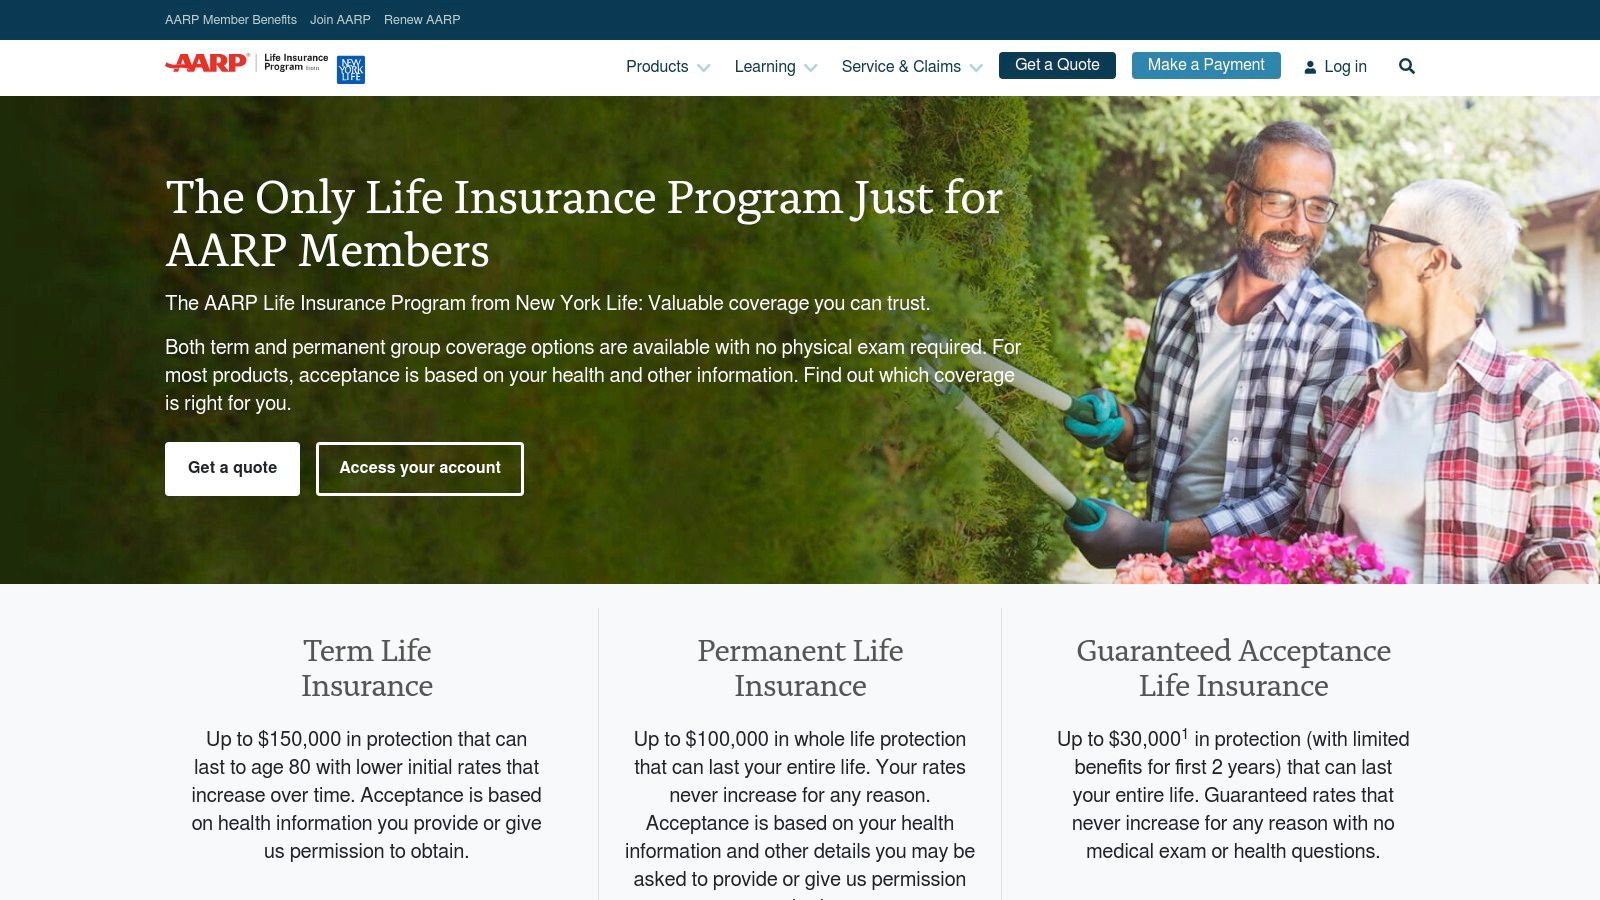
The AARP Life Insurance Program, underwritten by New York Life, provides seniors with simplified term and permanent coverage options. The "basic chart" typically found in their promotional materials illustrates monthly premiums based on age, gender, and coverage amounts. These charts help members identify costs for products that generally do not require medical exams or blood tests.
Understanding the AARP and New York Life Partnership
Before analyzing the specific charts and rates, it is essential to understand the structural foundation of this program. AARP (formerly the American Association of Retired Persons) is not an insurance company. Instead, they endorse specific products for their members. Since 1994, New York Life Insurance Company has been the exclusive underwriter for the AARP Life Insurance Program.
As we look at the landscape in 2026, this partnership remains one of the most significant in the senior insurance market. New York Life is a mutual insurance company, which means it is owned by its policyholders rather than shareholders. This structure often influences the stability and long-term outlook of the products offered to AARP members. When a senior views a "basic chart" for AARP insurance, they are looking at group-negotiated rates designed specifically for the demographics of AARP’s membership base, which includes individuals aged 50 and older.
The program is designed around "simplified issue" underwriting. In the broader insurance industry, "fully underwritten" policies require a paramedical exam, including blood work and a physical. In contrast, AARP’s primary products—the Level Benefit Term and Permanent Life—rely on a series of health questions. This makes the "basic chart" particularly appealing to seniors who may have manageable health issues but want to avoid the invasiveness of a full medical exam.
Decoding the AARP Life Insurance Basic Chart
When a member receives an enrollment kit, the "basic chart" is the focal point. It is usually organized into a grid that allows for quick cross-referencing. To read it accurately, you must understand the three primary variables that dictate where you fall on the grid: product type, age bracket, and coverage amount.
The Component of Age Brackets
AARP charts do not typically list a different price for every single year of age. Instead, they use five-year "age bands" (e.g., 50-54, 55-59, 60-64). Your premium is determined by which band you fall into at the time of application. In the case of Term Life Insurance, your premium will increase as you move from one band to the next. In Permanent Life Insurance, your premium is locked in based on your age at the time of purchase and does not increase as you get older.
Gender-Based Pricing
In most states, the basic chart is split between "Male" and "Female" columns. Statistically, women have a longer life expectancy than men, which is reflected in lower monthly premiums on the chart. However, it is important to note that certain states, such as Montana, require "unisex" pricing, where the chart will show a single rate regardless of gender.
Coverage Tiers
The horizontal axis of the basic chart usually displays coverage amounts. For many AARP products, these start as low as $5,000 or $10,000 and may go up to $100,000 or $150,000. By 2026, the demand for higher coverage amounts has increased due to the rising costs of final expenses and legacy planning, but the "basic" charts in mailers often focus on the $10,000 to $50,000 range to highlight affordability.
AARP Level Benefit Term Life Insurance
The Term Life product is the most common entry point for AARP members. It is designed to provide high coverage amounts for a lower initial cost. However, the "basic chart" for term insurance comes with a significant caveat: the rates are not permanent.
How the Term Chart Works
The Term Life chart displays "introductory" rates. Because these policies are "Level Benefit," the death benefit (the amount paid to your beneficiaries) stays the same, but the premiums increase every five years as you enter a new age bracket. This is a critical distinction to make when reading the chart. A 60-year-old might see a very attractive rate of $40 per month for $50,000 in coverage, but the chart’s fine print will indicate that at age 65, that rate will jump significantly.
Expiration and Conversion
Most AARP Term Life policies expire once the insured reaches age 80. The basic chart usually stops showing rates after age 74 or 79. This creates a "coverage gap" for seniors who live well into their 80s or 90s. To mitigate this, New York Life allows term policyholders to "convert" their policy to a permanent one without a medical exam, though the premiums for the permanent policy will be substantially higher than the term rates shown on the initial chart.
AARP Permanent Life Insurance (Whole Life)
For seniors looking for "final expense" or "burial" insurance, the Permanent Life Insurance chart is more relevant. Unlike term insurance, these policies are designed to last for the duration of the insured's life, provided premiums are paid.
Level Premiums for Life
The most significant advantage of the Permanent Life chart is that the rate you see for your current age is the rate you will pay forever. There are no five-year price jumps. This makes it an ideal choice for seniors on a fixed income who need to budget their monthly expenses precisely.
Cash Value Accumulation
While not always explicitly detailed in the "basic rate chart," AARP Permanent Life Insurance builds "cash value" over time. After the policy has been active for a few years, a portion of the premium builds up as equity. This can be borrowed against in an emergency, though any outstanding loans will be deducted from the death benefit paid to beneficiaries.
Guaranteed Acceptance Life Insurance
A third chart often seen in AARP materials is for "Guaranteed Acceptance" life insurance. This product is specifically designed for seniors with significant health challenges who cannot qualify for the simplified issue products.
No Health Questions
The "chart" for this product is the simplest of all. There are no medical questions and no exams. If you are an AARP member within the eligible age range (typically 50-80), you cannot be turned down.
The Two-Year Graded Death Benefit
This is the most important "fine print" associated with the Guaranteed Acceptance chart. If the insured dies of natural causes within the first two years of the policy, the beneficiaries do not receive the full face value. Instead, they receive a refund of all premiums paid plus a specific percentage of interest (usually 10%). After the two-year "waiting period" is over, the full death benefit is active. This "graded benefit" is how the insurance company offsets the risk of insuring individuals with serious pre-existing conditions.
AARP Life Insurance Product Comparison Table
The following table summarizes the differences between the main products described in the AARP basic charts as of 2026.
| Feature | Level Benefit Term | Permanent (Whole) Life | Guaranteed Acceptance |
|---|---|---|---|
| Age Eligibility | 50 - 74 | 50 - 80 | 50 - 80 |
| Max Coverage | Typically $150,000+ | Typically $50,000 | Typically $25,000 |
| Premium Structure | Increases every 5 years | Fixed / Never increases | Fixed / Never increases |
| Medical Questions | Yes (Simplified) | Yes (Simplified) | None |
| Medical Exam | Not usually required | Not usually required | Never required |
| Waiting Period | Immediate full coverage | Immediate full coverage | 2-Year Graded Benefit |
| Cash Value | No | Yes | Yes |
| Policy Expiration | Usually at age 80 | Never (as long as paid) | Never (as long as paid) |
Factors That Influence Your Specific Rate
While the basic chart gives a generic overview, your actual premium might vary based on several factors that aren't always visible in a simple grid.
State-Specific Regulations
Insurance is regulated at the state level. Some states have different rules regarding how long a "waiting period" can be or how much a premium can increase. When you request a quote from New York Life, the chart you receive will be tailored to the regulations of your state of residence.
Smoking Status
Most AARP life insurance charts distinguish between "Tobacco Users" and "Non-Tobacco Users." If you have used any tobacco products in the last 12 to 24 months, you will likely be moved to a different chart with significantly higher premiums—often 50% to 100% more than the non-tobacco rates.
Membership Status
You must be a member of AARP to apply for these policies. While AARP membership is relatively inexpensive, it is a prerequisite. If your membership lapses, it could potentially complicate your ability to manage or update your policy, although once a policy is "in force," the insurance company generally cannot cancel it as long as the premiums are paid.
Common Mistakes When Reading AARP Charts
Many seniors misinterpret the information presented in the basic charts, leading to frustration later on. Awareness of these common pitfalls can help in making a better decision.
- Ignoring the Term Increase: The biggest mistake is assuming the Term Life price is locked in. Many seniors choose Term because it is the cheapest option on the chart today, only to find it unaffordable ten years later when they are in a different age bracket.
- Overlooking the Graded Benefit: In the Guaranteed Acceptance chart, some users fail to realize the two-year wait for full coverage. It is vital to understand that if a natural death occurs in month 18, the full $25,000 (for example) will not be paid.
- Assuming it's the "Cheapest" Option: While AARP rates are competitive and the application process is easy, "simplified issue" products are sometimes more expensive than "fully underwritten" products. If you are in excellent health, you might find a lower rate by taking a medical exam with a different carrier.
- Miscalculating Coverage Needs: Seniors often look at the $10,000 or $15,000 columns because the monthly premium looks "right." However, by 2026, the average cost of a funeral and associated expenses can easily exceed $12,000 to $15,000. It is important to ensure the coverage amount actually meets the intended goal.
How to Apply Using the Chart Data
If you have analyzed the chart and decided on a plan, the application process is streamlined to match the simplicity of the charts themselves.
- Step 1: Request a Personalized Kit: While the basic charts in magazines are helpful, you should request a personalized quote through the AARP Life Insurance Program website or by calling their toll-free number.
- Step 2: Complete the Health Questionnaire: For the Term and Permanent plans, you will answer a few "Yes/No" questions regarding your medical history (e.g., history of heart disease, cancer, or recent hospitalizations).
- Step 3: Beneficiary Designation: You will need the full legal names and Social Security numbers of the people you want to receive the death benefit.
- Step 4: Review the Free Look Period: New York Life typically offers a 30-day "Free Look" period. This means you can pay your first premium, receive the full policy document, and if you change your mind within 30 days, you can cancel for a full refund.
Frequently Asked Questions
Does AARP life insurance require a physical exam?
No, most AARP life insurance products offered through New York Life do not require a physical exam or blood work. The Term and Permanent Life products use "simplified underwriting," which involves answering a few health questions on the application. The Guaranteed Acceptance product has no health questions at all.
Why do the rates on my AARP term life chart increase every five years?
Term life insurance is designed to cover a specific "term" or period. In the AARP program, these terms are structured in five-year age bands. As you age, the statistical risk of death increases, so the premiums are adjusted every time you enter a new five-year bracket (e.g., moving from the 60-64 bracket to the 65-69 bracket).
Can I keep my AARP life insurance if I leave AARP?
You must be a member to apply for the insurance. Once the policy is active (in force), it is a contract between you and New York Life. Generally, as long as you continue to pay your premiums on time, the coverage remains active even if you do not renew your AARP membership. However, it is always best to maintain your membership to ensure access to all member services and potential dividend opportunities if applicable.
What is the maximum amount of coverage available on the AARP charts?
As of 2026, the maximum coverage for the Level Benefit Term Life Insurance typically reaches $150,000 for most members, though some special offers may allow for more. For Permanent Life Insurance, the limit is usually $50,000, and for Guaranteed Acceptance, it is typically capped at $25,000.
Is the "basic chart" the same for everyone in the United States?
No. While the structure of the chart is similar, the actual dollar amounts can vary based on your state of residence. State insurance departments must approve the rates, and some states have different requirements for pricing (such as unisex rates) and policy features.
Practical Recommendation
When evaluating the AARP Life Insurance basic chart, start by defining your goal. If you only need to cover a mortgage or debt that will be paid off within the next 10 years, the Level Benefit Term plan's initial low cost is attractive. However, if your goal is to provide your family with guaranteed funds for funeral costs regardless of when you pass away, the Permanent Life Insurance plan is the superior choice because it avoids the "age-band" price hikes and never expires. Always compare the "simplified" rates from AARP with at least one "fully underwritten" quote from another carrier if you are in good health, as you may find significant savings elsewhere by undergoing a medical exam.