Arianna Clark represents a vital voice in modern financial technology discourse, offering critical insights as the global economy rapidly transitions away from traditional cash and legacy banking rails. Her analysis captures how emerging innovations—such as decentralized finance networks, instant payment rails, real-time cross-border settlements, and advanced cryptographic authentication—fundamentally reshape consumer expectations and enterprise operational standards.
The Evolution of Global Financial Infrastructure
The historical trajectory of financial transactions has transitioned from paper notes and physical ledgers to centralized digital databases and, increasingly, decentralized or distributed ledger systems. For decades, traditional banking rails—such as the Automated Clearing House (ACH) network in the United States or legacy wire transfer systems—dictated the speed and cost of moving money. These legacy systems, while generally secure, rely on batch-processing mechanisms that create inherent delays, often taking several business days to clear funds fully.
As commercial activity expanded into borderless digital marketplaces and e-commerce platforms, the friction of legacy infrastructure became a major bottleneck. Financial analysts like Arianna Clark have closely tracked this friction, emphasizing that modern consumers and enterprises demand immediate liquidity. The shift toward instant payment infrastructure is not merely a convenience upgrade; it is a structural overhaul driven by technological capabilities and shifting user behaviors.
Central banks and private consortia worldwide have responded by building real-time gross settlement (RTGS) systems and instant payment rails. Examples include the Federal Reserve’s FedNow service in the United States, Europe's TARGET Instant Payment Settlement (TIPS), and Brazil's Pix system. These platforms allow funds to transfer between accounts 24 hours a day, 365 days a year, with immediate finality. This evolution requires financial institutions to modernize their core banking architectures, moving away from monolithic, legacy software toward cloud-native, API-driven systems capable of handling high-volume, real-time data streams.
Key Drivers Transforming the Digital Payment Ecosystem
The ongoing transformation of the payment landscape is propelled by several converging technological, regulatory, and consumer-driven forces. Understanding these drivers is essential for financial institutions, fintech startups, and enterprise merchants aiming to remain competitive.
1. The Rise of Open Banking and API Connectivity
Open banking frameworks mandate that financial institutions securely share customer data with authorized third-party providers via application programming interfaces (APIs). This structural shift breaks down traditional banking silos, allowing alternative payment providers to initiate account-to-account (A2A) payments directly without relying on traditional card networks like Visa or Mastercard. This disintermediation lowers transaction fees for merchants and accelerates settlement speeds.
2. Mobile-First and Omnichannel Commerce
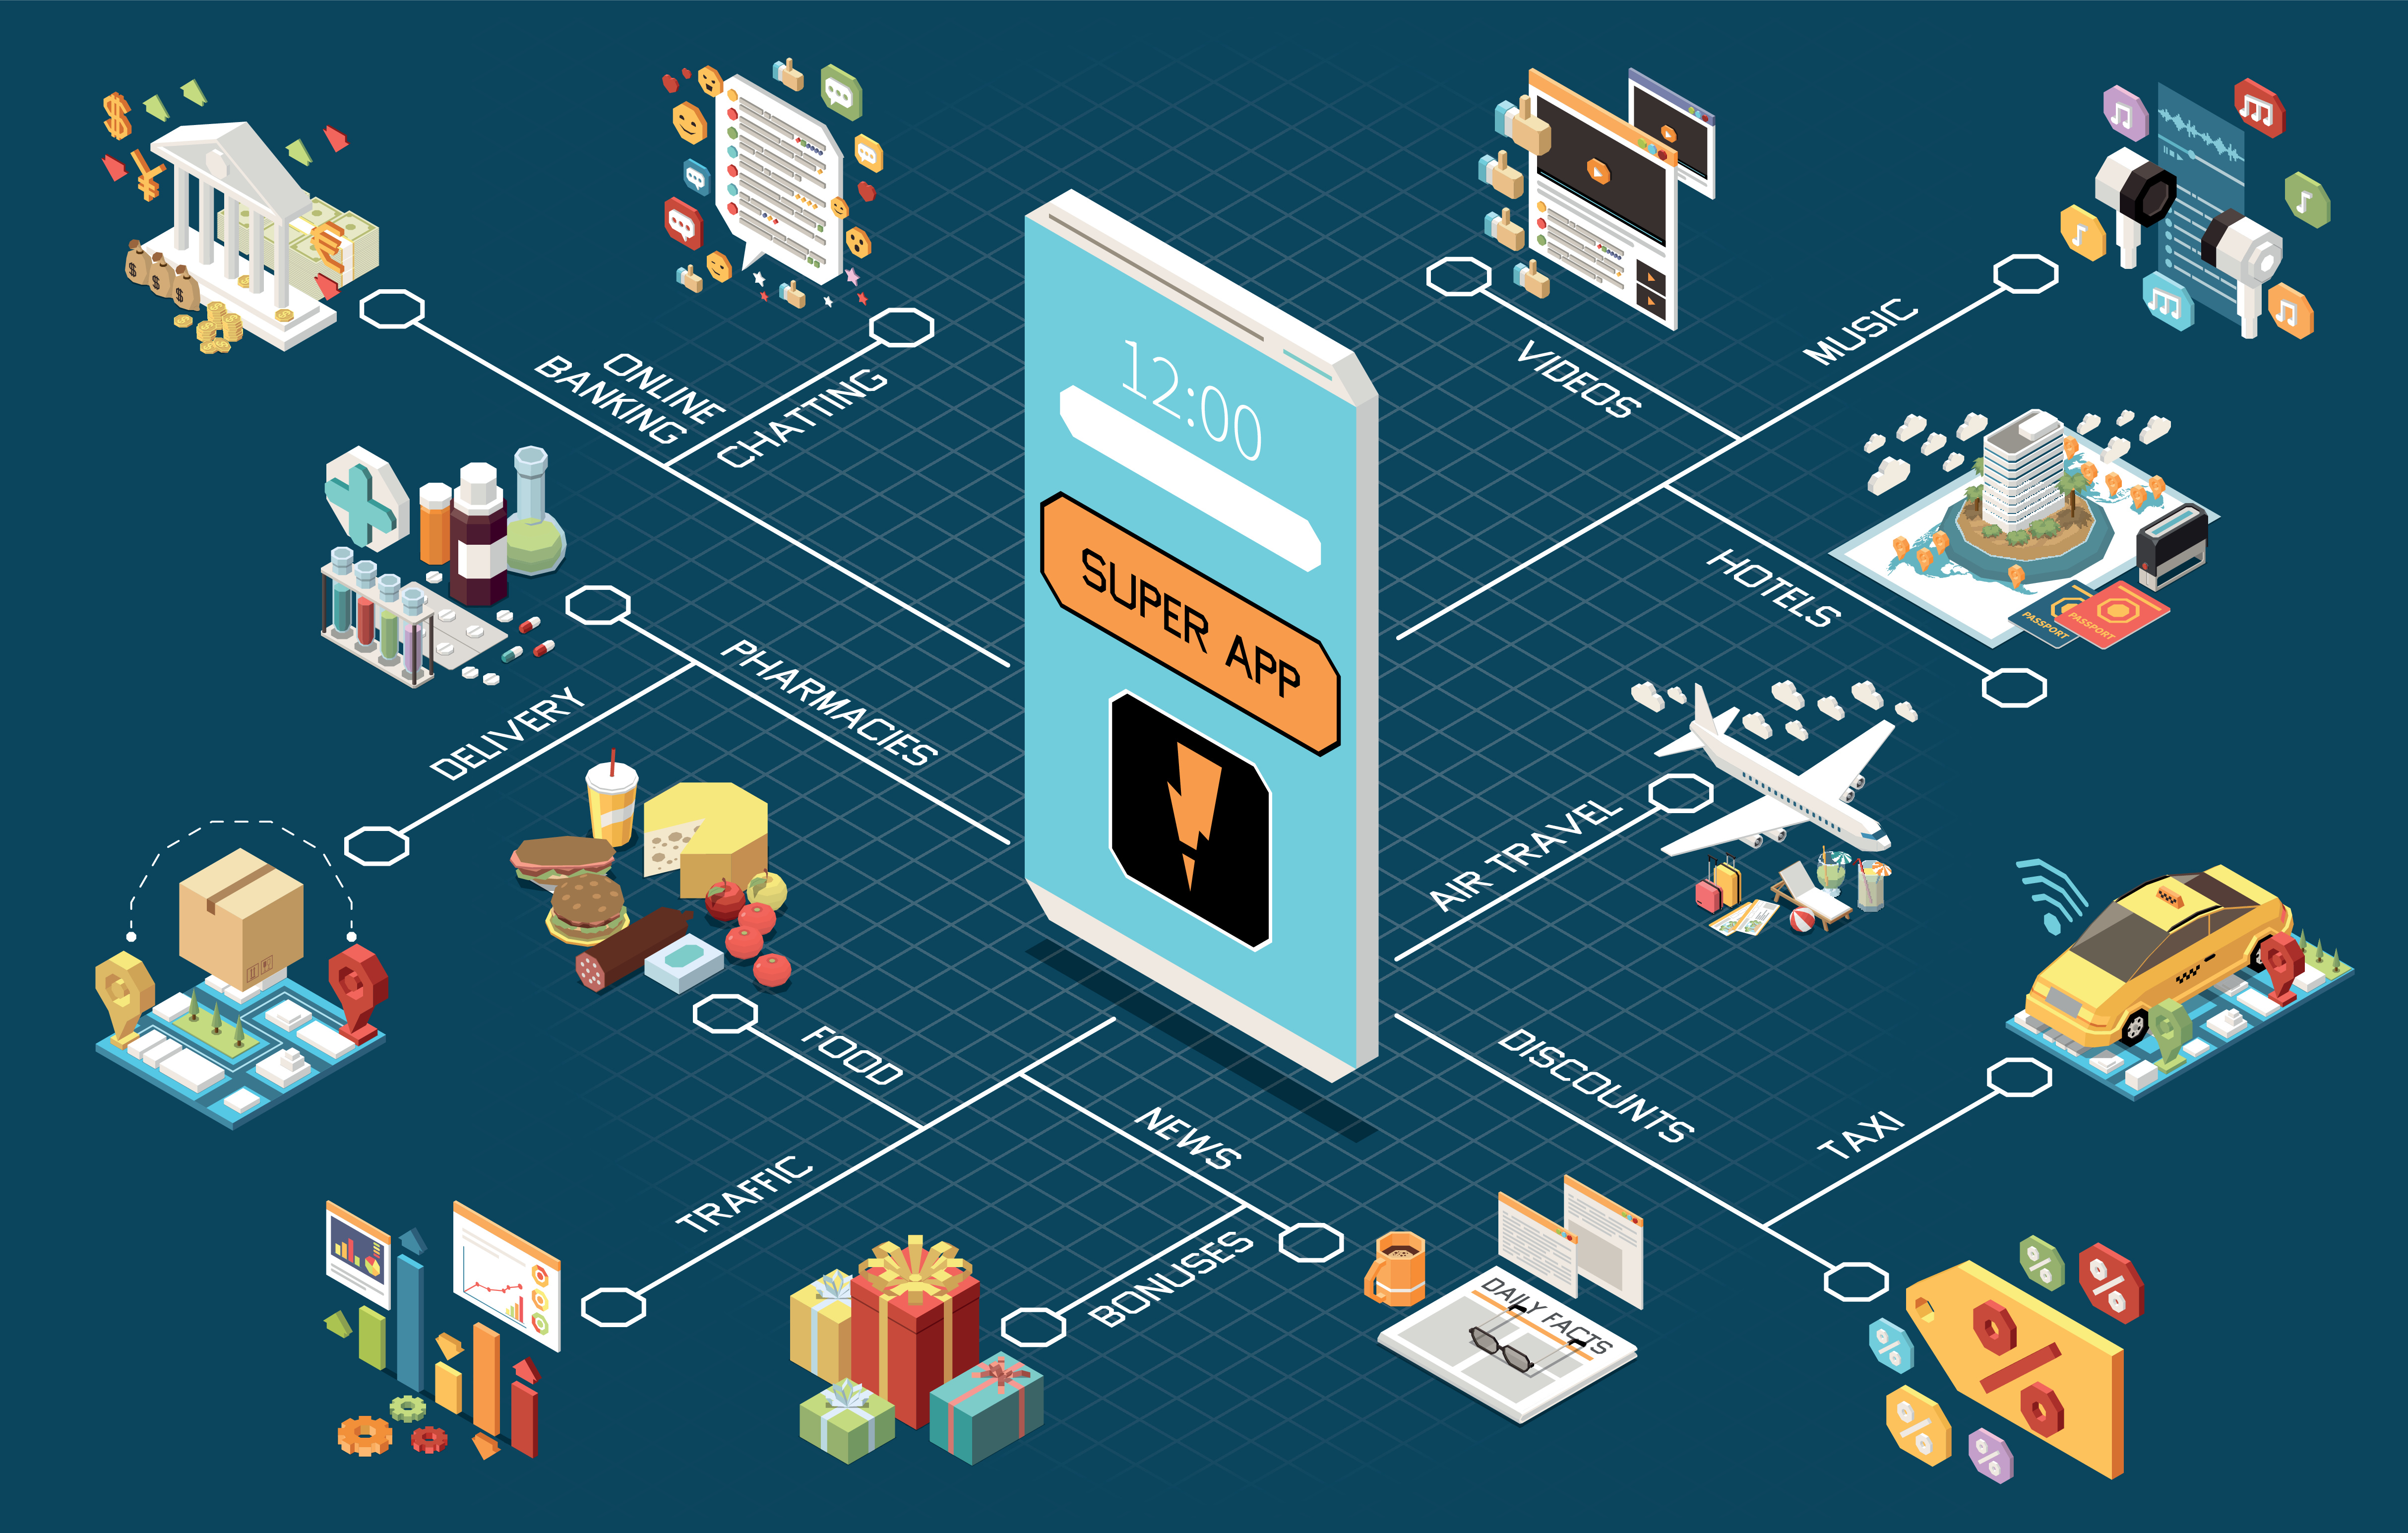
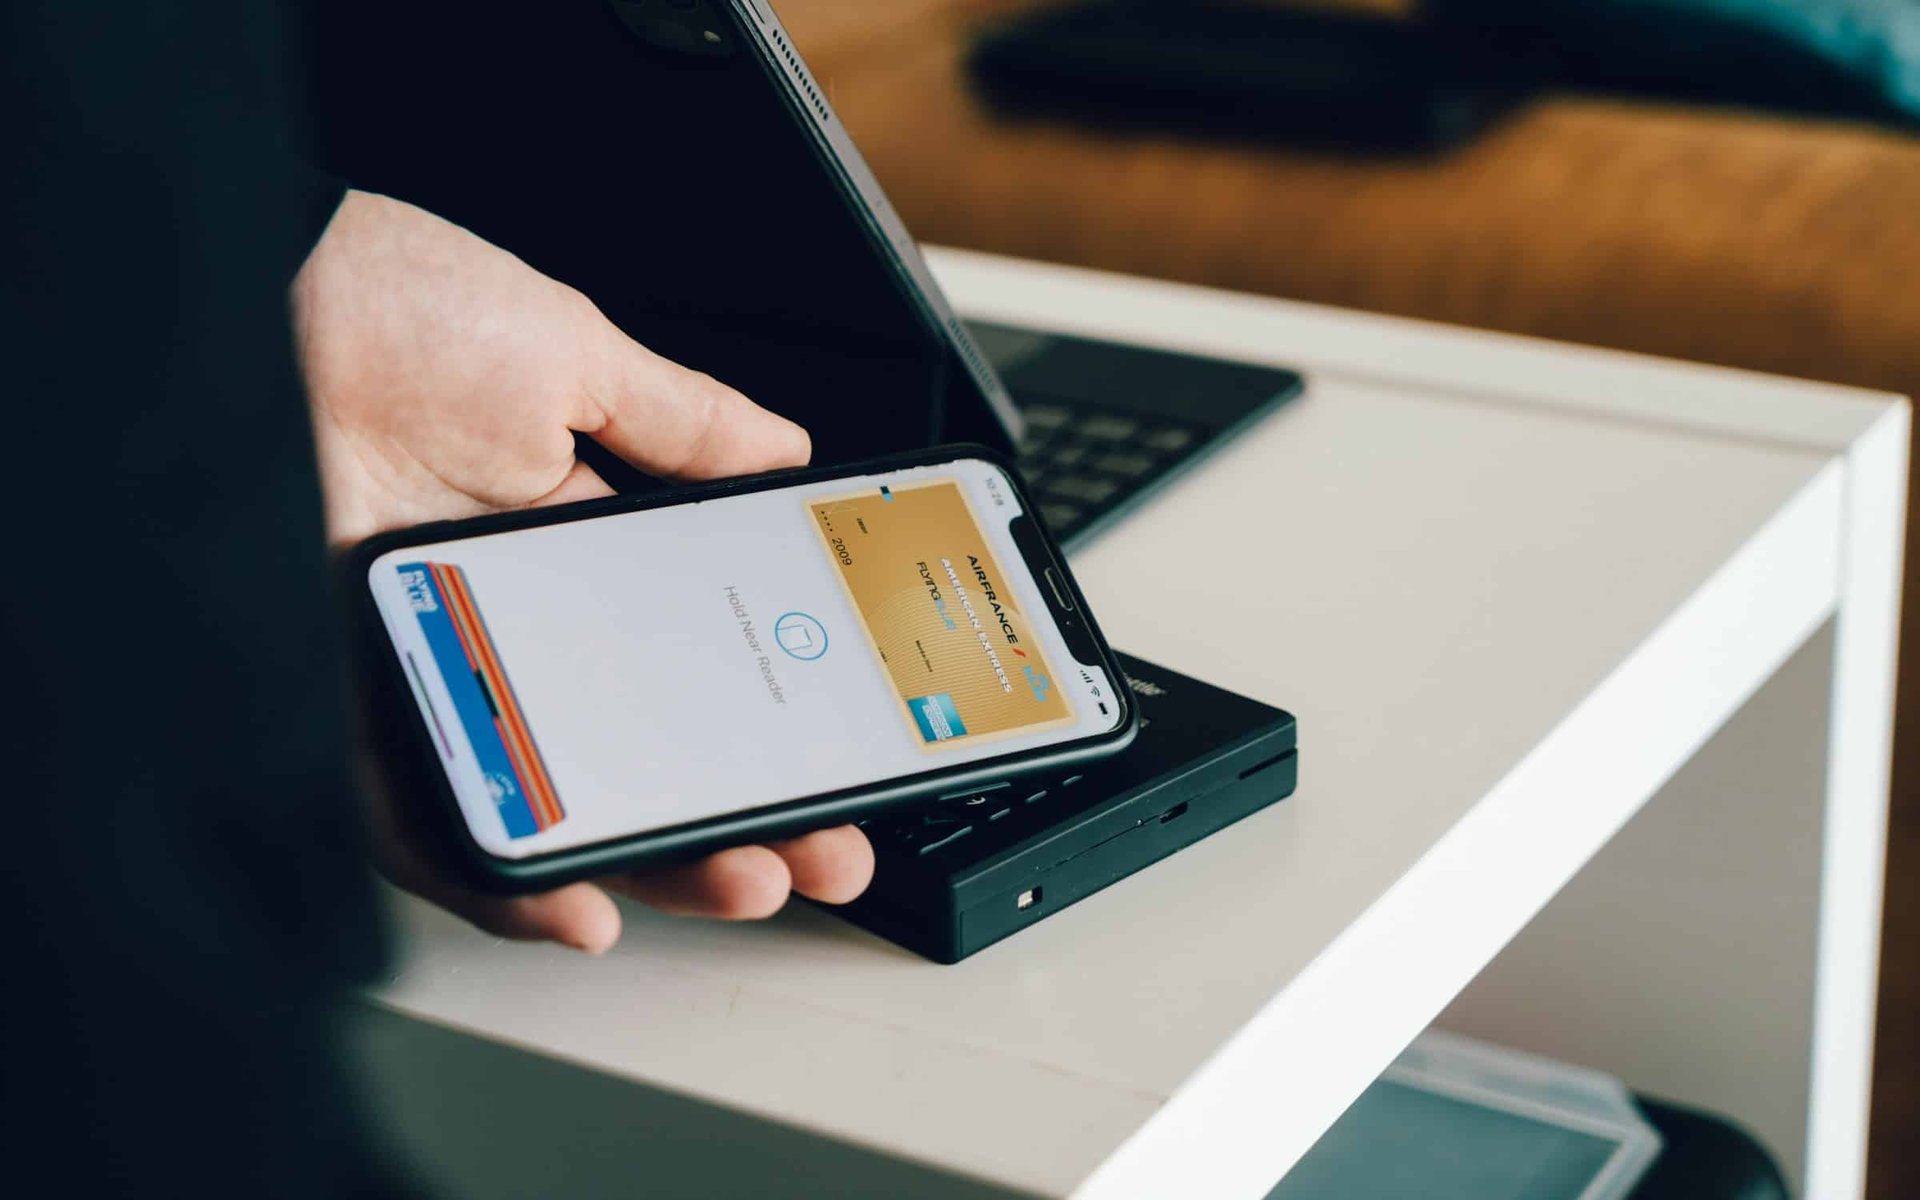
The proliferation of smartphones has fundamentally altered how consumers interact with money. Mobile wallets—such as Apple Pay, Google Wallet, and region-specific super-apps—have moved payment credentials out of physical wallets and into digital spaces. Omnichannel commerce demands that payment experiences remain seamless across physical point-of-sale (POS) terminals, mobile applications, and web browsers, requiring merchants to adopt unified commerce platforms.
3. Cross-Border Settlement Innovations
International trade has historically been plagued by high foreign exchange fees, opaque intermediary bank chains, and multi-day settlement windows. Modern fintech solutions leverage blockchain protocols, stablecoins, and direct correspondent banking networks to compress cross-border settlement times from days to seconds while drastically reducing transaction costs.
Comparative Analysis of Payment Technologies
To understand the trajectory of modern commerce, it is helpful to compare the dominant payment modalities currently operating within the global ecosystem. Each technology presents distinct operational characteristics regarding speed, cost, and risk profile.
| Payment Technology | Average Settlement Speed | Primary Cost Structure | Regulatory & Security Profile | Typical Use Case |
|---|---|---|---|---|
| Legacy Credit/Debit Cards | 1 to 3 Business Days | Interchange fees (1.5% to 3.5%) + processing fees | High PCI-DSS compliance; chargeback protections | Traditional e-commerce and retail POS |
| Real-Time Rails (e.g., FedNow, Pix) | Instant (Seconds) | Low flat per-transaction fees | Central bank regulated; strict authentication rules | P2P transfers, B2B invoicing, emergency payouts |
| Open Banking A2A Payments | Instant to Near-Instant | Intermediary API fees (typically lower than cards) | PSD2/PSD3 compliant in Europe; consent-driven | E-commerce checkouts and bill pay |
| Stablecoin / Blockchain Rails | Minutes (dependent on network) | Network gas fees or nominal merchant processing rates | Evolving global regulatory frameworks (MiCA, etc.) | Cross-border B2B settlement and remittances |
Regulatory Realities and Compliance Challenges
As digital payment systems evolve at a rapid pace, regulatory bodies worldwide are working to establish guardrails that protect consumers without stifling innovation. Observers note that the friction between rapid technological deployment and rigorous compliance creates significant strategic challenges for market participants.
Anti-Money Laundering (AML) and Know Your Customer (KYC)
Digital-first and decentralized payment networks often facilitate cross-border transactions that cross multiple legal jurisdictions instantaneously. Ensuring robust AML and KYC compliance across these distributed rails requires advanced identity verification technologies, including biometric screening, device fingerprinting, and real-time transaction monitoring powered by artificial intelligence.
Data Privacy and Security Standards
Regulations such as the European Union's General Data Protection Regulation (GDPR) and various state-level privacy laws in the United States impose strict limitations on how consumer financial data can be collected, stored, and shared. Payment processors must implement end-to-end encryption, tokenization, and secure data enclaves to prevent catastrophic data breaches while maintaining compliance with regional mandates.
Fragmentation vs. Interoperability
One of the primary hurdles in the modern payment landscape is regulatory fragmentation. Because different countries and economic zones implement divergent technical standards and legal frameworks for digital assets and instant payments, global enterprises face complex compliance matrices when expanding operations internationally.
Security, Fraud Mitigation, and Risk Management
With the digitization of money comes an exponential increase in sophisticated financial crimes, including synthetic identity fraud, account takeover attacks, and real-time authorized push payment (APP) scams. As payment speeds increase, traditional manual fraud review processes become obsolete.
Financial institutions and payment service providers are increasingly deploying artificial intelligence and machine learning models to analyze transaction patterns in milliseconds. These systems evaluate hundreds of risk variables—including geolocation, behavioral biometrics, transaction velocity, and device health—to intercept fraudulent transfers before settlement occurs.
Furthermore, the implementation of Strong Customer Authentication (SCA) mandates multi-factor authentication (MFA) protocols, combining something the user knows (password), something the user has (phone or hardware token), and something the user is (biometric data). While these measures enhance system integrity, they require a delicate balance to avoid introducing unnecessary user friction that could lead to cart abandonment during e-commerce checkouts.
Frequently Asked Questions
What are instant payment rails, and how do they differ from traditional payment methods?
Instant payment rails are modern financial infrastructures that enable funds to transfer between bank accounts within seconds, 24/7/365. Unlike traditional methods like ACH or wire transfers, which rely on batch processing and business-day cutoffs, instant rails achieve immediate clearing and settlement, providing instant liquidity to both payers and payees.
How does open banking impact traditional credit card networks?
Open banking allows direct account-to-account (A2A) payments via secure APIs, bypassing traditional card networks like Visa and Mastercard. By eliminating intermediary card interchange fees, open banking offers merchants a lower-cost payment alternative while giving consumers direct control over their financial data.
What role do stablecoins play in the modern digital payment landscape?
Stablecoins are cryptocurrencies typically pegged to a fiat currency, such as the US Dollar, designed to maintain a stable value. In digital payments, they serve as high-speed, low-cost settlement vehicles for cross-border B2B transactions and remittances, bypassing legacy correspondent banking chains.
What are the primary security risks associated with real-time digital payments?
The primary risks include authorized push payment (APP) scams, account takeover attacks, and synthetic identity fraud. Because real-time payments offer immediate settlement finality, transactions are difficult to reverse once executed, making real-time AI-driven fraud detection essential.
How are regulatory frameworks adapting to decentralized payment innovations?
Regulators are actively developing comprehensive legal frameworks—such as the European Union's Markets in Crypto-Assets (MiCA) regulation—to establish clear licensing requirements, consumer protection standards, and AML/KYC obligations for digital asset and alternative payment providers.
Strategic Next Steps for Enterprises and Financial Institutions
Navigating the shifting landscape of digital payments requires a proactive, adaptable strategy. Organizations operating in commerce, banking, or fintech must evaluate their current technology stacks to ensure compatibility with real-time rails, open banking APIs, and advanced security protocols.
- Audit Legacy Infrastructure: Assess existing core banking or merchant platforms to identify bottlenecks associated with batch-processing and legacy data silos.
- Prioritize Interoperability: Invest in cloud-native, API-first payment orchestration layers that allow seamless integration of multiple payment methods, from traditional cards to instant A2A rails and digital wallets.
- Enhance Fraud Prevention: Deploy real-time, AI-driven risk mitigation and behavioral analytics tools to protect against modern cyber threats without degrading the customer checkout experience.
- Monitor Regulatory Shifts: Maintain close alignment with evolving compliance standards across all operating jurisdictions to mitigate legal risks associated with cross-border data transfer and digital asset handling.