Securing auto insurance in Arcadia, Florida, requires a thorough understanding of state-mandated coverage minimums, localized risk factors such as weather and rural-urban driving patterns, and the distinct offerings of regional versus national carriers. Drivers in this DeSoto County hub must balance mandatory Personal Injury Protection (PIP) and Property Damage Liability (PDL) with optional collision and comprehensive policies to protect their financial well-being against uninsured motorists and environmental hazards.
Understanding the Arcadia, FL Auto Insurance Landscape
Shopping for car insurance in Arcadia, Florida, involves evaluating a mix of regional constraints and statewide regulatory standards. As the county seat of DeSoto County, Arcadia presents a unique driving environment characterized by a blend of rural highways, agricultural vehicle traffic, and dense local corridors near U.S. Route 17 and State Road 70. These geographic and infrastructural realities influence how insurance companies calculate risk, premium rates, and policy availability for local residents.
Unlike major metropolitan hubs like Miami or Orlando, Arcadia's smaller population base can sometimes mean fewer physical brick-and-mortar agency storefronts. However, residents have access to a robust network of regional independent insurance agents, statewide Florida agencies, and national digital-first carriers. Understanding how these entities operate within Florida’s specific no-fault insurance system is the first step toward securing adequate and cost-effective coverage.
The Florida No-Fault System and Arcadia Drivers
Florida operates under a strict motor vehicle no-fault law, which dictates how medical bills and minor property damages are handled following a traffic collision. Every driver registering a motor vehicle in Arcadia must purchase and maintain specific minimum coverages through a licensed insurance carrier authorized to transact business in the state.
The core requirement of this system is that your own insurance company pays for your medical expenses and lost wages up to your policy limits, regardless of who caused the accident. This structure aims to reduce litigation in the court system for minor collisions, but it also places a heavy reliance on Personal Injury Protection (PIP) coverage. Because medical costs across Florida continue to rise, relying solely on the state-mandated minimums often leaves drivers dangerously underinsured in the event of a significant crash on local thoroughfares like County Road 661 or State Road 31.
Mandatory Minimum Insurance Requirements in Florida
To legally operate a motor vehicle registered in Arcadia, FL, you must comply with Florida Statutes Chapter 627. Failing to maintain continuous coverage can lead to severe penalties, including the suspension of your driver's license, vehicle registration revocation, and costly reinstatement fees.
Personal Injury Protection (PIP)
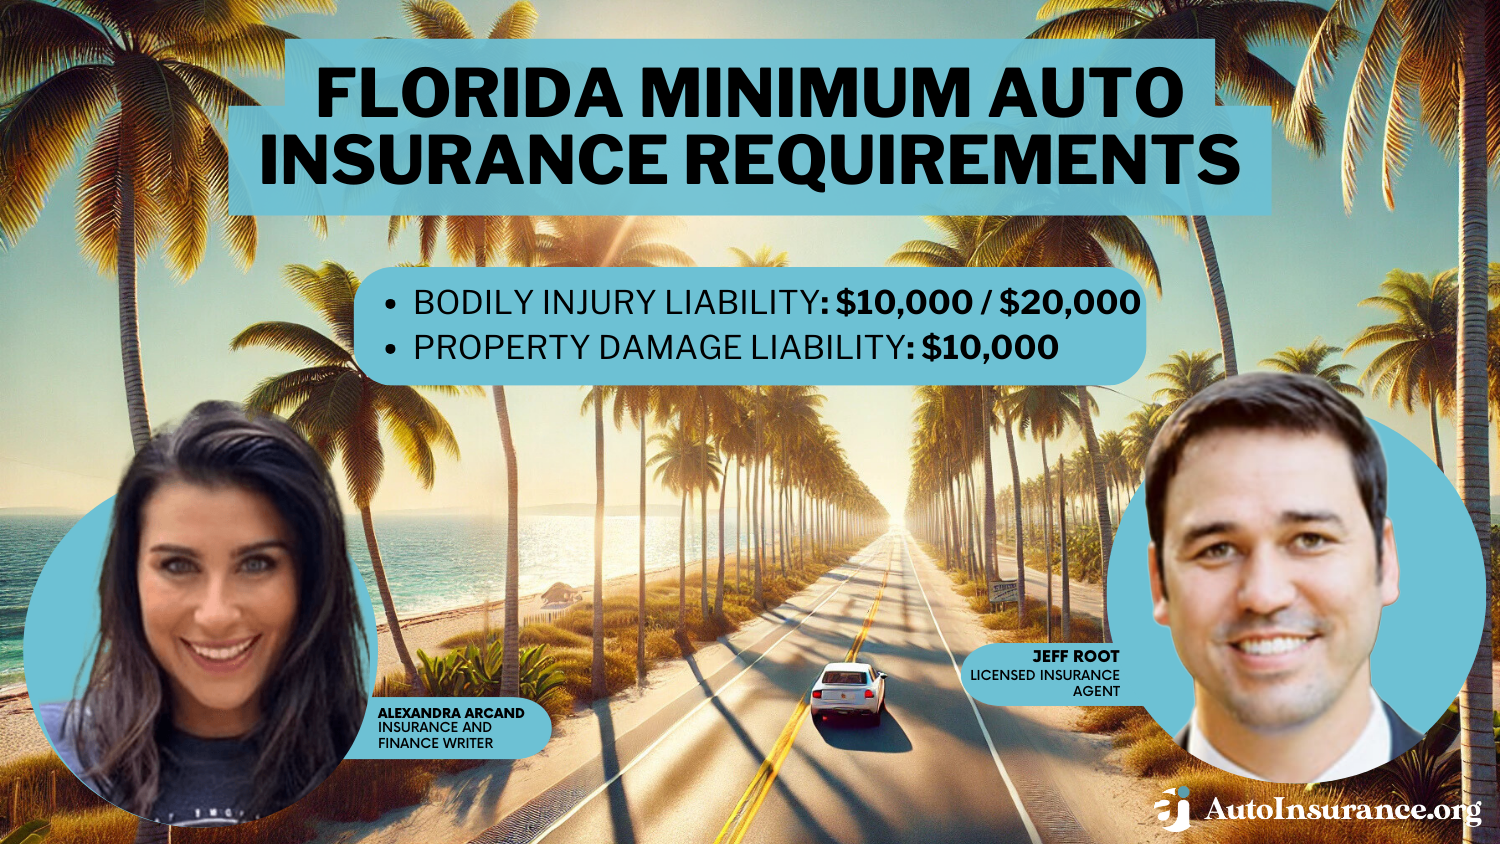
Florida law mandates that all vehicle owners carry a minimum of $10,000 in Personal Injury Protection (PIP). This coverage pays 80% of necessary and চিকিৎসার medical expenses up to $10,000 for covered injuries, regardless of fault. It also provides 60% of lost wages and a minor death benefit.
To qualify for the full $10,000 benefit, treatment must typically be sought within 14 days of the accident from an authorized medical provider, and a physician must diagnose an "emergency medical condition" (EMC). If an EMC is not diagnosed, the PIP benefit is capped at $2,500.
Property Damage Liability (PDL)
In addition to PIP, drivers must carry a minimum of $10,000 in Property Damage Liability (PDL). This coverage pays for damage you cause to someone else's property, such as another vehicle, utility poles, fences, or municipal structures.
While these two coverages represent the legal minimums to drive in Arcadia, insurance professionals universally recommend higher limits and additional coverage types, as $10,000 in property damage is easily exhausted in a minor multi-car collision.
| Coverage Type | Mandatory Minimum | What It Covers | Recommended Action |
|---|---|---|---|
| Personal Injury Protection (PIP) | $10,000 | 80% of your medical bills, 60% of lost wages | Consider higher limits if self-employed or without robust health insurance. |
| Property Damage Liability (PDL) | $10,000 | Damage your vehicle causes to other people's property | Increase to $50,000 or $100,000 to protect personal assets. |
| Bodily Injury Liability (BIL) | Not Mandatory* | Medical costs and legal fees if you injure someone else | Highly recommended (e.g., 50/100/50 limits) to prevent personal lawsuits. |
| Collision Coverage | Optional | Damage to your own vehicle from a crash or rollover | Essential if your car is financed or has a high market value. |
| Comprehensive Coverage | Optional | Theft, fire, vandalism, animal strikes, or storm damage | Crucial in Florida due to hurricane and severe weather risks. |
*Note: While Bodily Injury Liability is not strictly mandated for all standard drivers under Florida law, it becomes mandatory if you have certain driving infractions, such as a DUI, or if you are involved in an accident where you were at fault and lacked coverage.
Types of Auto Insurance Providers Serving Arcadia
When looking for auto insurance companies operating in Arcadia, FL, consumers generally choose between three main categories of providers. Each model offers distinct advantages depending on whether a driver prioritizes personalized local service, broad policy customization, or automated digital convenience.
Independent Insurance Agencies
Independent agents in and around DeSoto County represent multiple insurance carriers rather than a single corporate brand. This allows them to shop around across various regional and national companies on your behalf.
- Advantages: Unbiased comparisons, localized expertise regarding Florida-specific risks, and personalized customer service.
- Considerations: Rates ultimately depend on the underwriting guidelines of the underlying insurance carrier they match you with.
Captive Insurance Agents
Captive agents work exclusively for one major insurance company (such as State Farm, Allstate, or GEICO). They possess deep knowledge of their specific company's proprietary discounts, bundling options, and policy endorsements.
- Advantages: Streamlined claims processes, strong brand recognition, and deep familiarity with a single company's product suite.
- Considerations: Limited to quoting prices from only one parent company, meaning you cannot easily compare competing rates through the same agent.
Direct-to-Consumer Digital Insurers
Online-only or app-based carriers allow drivers to purchase policies directly without interacting with a traditional agent. These companies often utilize telematics devices or smartphone apps to track driving habits in exchange for lower initial premiums.
- Advantages: Fast quote generation, 24/7 digital policy management, and potential savings for safe or low-mileage drivers.
- Considerations: Lack of face-to-face support can make complex claims or coverage adjustments more challenging to navigate.
Factors Influencing Auto Insurance Rates in Arcadia, FL
Auto insurance premiums are not uniform across the state of Florida; they vary significantly by zip code, city, and individual driver characteristics. Insurance companies evaluate several localized and personal risk factors when determining the cost of coverage in Arcadia.
Local Risk Factors in DeSoto County
- Weather and Environmental Hazards: Florida’s subtropical climate introduces severe weather risks, including tropical storms, heavy seasonal rainfall, and hurricanes. Vehicles parked or driven in Arcadia can be vulnerable to wind damage, flying debris, and localized flooding. These environmental risks influence comprehensive insurance pricing.
- Rural and Semi-Rural Driving Patterns: While Arcadia features quieter rural stretches, it also experiences heavy agricultural transport trucks, seasonal tourist traffic heading toward the coast, and transit along major state arteries. Accident severity on two-lane rural highways often trends higher due to increased speeds, impacting bodily injury underwriting models.
- Statewide Litigiousness: Florida consistently ranks among states with high rates of auto insurance litigation and fraudulent claims. This broader legal environment drives up reinsurance and loss costs for insurance companies statewide, which reflects in regional premium adjustments.
Personal Rating Factors
Beyond geography, insurers evaluate your individual profile:
- Driving Record: Points accrued from speeding tickets, moving violations, and at-fault accidents remain on your motor vehicle record for several years, directly increasing your risk tier.
- Credit-Based Insurance Score: In Florida, insurers are permitted to use credit history as a rating factor (with certain regulatory restrictions) to predict the statistical likelihood of filing a claim.
- Vehicle Make, Model, and Safety Features: Repair costs, theft rates, and standard safety equipment (such as advanced driver-assistance systems) heavily alter collision and comprehensive premiums.
How to Compare and Choose the Right Policy
Selecting the right auto insurance company in Arcadia requires a methodical approach that goes beyond simply choosing the lowest monthly quote. A cheap policy that fails to provide adequate protection during a major claim can lead to severe financial distress.
Step-by-Step Evaluation Process
- Audit Your Current Coverage: Review your existing policy declarations page. Note your current liability limits, deductibles, and optional coverages like roadside assistance or rental car reimbursement.
- Determine Your Asset Protection Needs: If you own a home, have significant savings, or earn a high income, purchasing higher Bodily Injury Liability limits (such as 100/300/100) shields your personal assets from aggressive litigation following a severe accident.
- Gather Multiple Quotes: Obtain quotes from at least three different sources—combining independent local agents, captive agents, and direct digital carriers—ensuring that each quote features identical coverage limits for an accurate apples-to-apples comparison.
- Verify Carrier Financial Stability: Check the financial strength ratings of unfamiliar regional insurers through independent rating agencies like A.M. Best or Demotech (which is widely used by Florida-domiciled property and casualty insurers). A high financial rating ensures the company has the liquidity to pay out large claims promptly.
- Inspect Customer Service and Claims Reputations: Read independent consumer reviews and look at complaint ratios published by the Florida Office of Insurance Regulation to gauge how efficiently a company handles claims processing and customer support.
Common Mistakes to Avoid When Buying Car Insurance
Navigating the insurance market can be complex, and policyholders often make costly errors that compromise their coverage or inflate their expenses.
- Opting Solely for State Minimums: Choosing the absolute legal minimums ($10,000 PIP and $10,000 PDL) to secure the lowest possible monthly payment is a dangerous gamble. If you cause an accident that totals a modern truck or results in extensive medical bills for another driver, you will be held personally liable for every dollar exceeding your policy limits.
- Failing to Disclose Household Drivers: Every licensed driver living in your household—including teenagers or aging family members—must typically be listed on your policy or formally excluded. Failing to disclose household drivers can lead to denied claims or policy cancellation for misrepresentation.
- Ignoring Available Discounts: Many drivers miss out on substantial savings by failing to ask about discounts for bundling auto and homeowners insurance, maintaining a paperless account, completing defensive driving courses, or equipping their vehicles with anti-theft devices.
- Overlooking Comprehensive and Collision Deductibles: Setting deductibles too low can unnecessarily spike your monthly premium, while setting them higher than your emergency savings can make repairs unaffordable after an incident. Balance your deductible amount against your liquid cash reserves.
Frequently Asked Questions
Is Florida a no-fault state for auto insurance, and what does that mean for Arcadia drivers?
Yes, Florida is a no-fault state. This means that if you are injured in a car accident in Arcadia, your own Personal Injury Protection (PIP) insurance covers your medical bills and lost wages up to your policy limits, regardless of who caused the crash. You only step outside the no-fault system to sue the at-fault driver if your injuries meet Florida's severe injury threshold, such as permanent and significant loss of an important bodily function.
What are the minimum auto insurance limits required in Arcadia, FL?
The legal minimum auto insurance required to register and drive a vehicle in Arcadia, Florida, consists of $10,000 in Personal Injury Protection (PIP) and $10,000 in Property Damage Liability (PDL). However, insurance professionals strongly recommend carrying Bodily Injury Liability and higher coverage limits to protect against personal financial exposure.
Can I buy car insurance in Arcadia with an out-of-state driver's license?
Yes, you can purchase an auto insurance policy in Florida with an out-of-state license, but most insurance carriers require you to register and title your vehicle in Florida if you are living in the state for more than a temporary period, or if you establish residency. Insurers will evaluate your driving history from your previous state using your motor vehicle record.
How can I lower my auto insurance rates in DeSoto County?
You can lower your insurance premiums by maintaining a clean driving record, bundling your auto policy with homeowners or renters insurance, opting for higher deductibles on comprehensive and collision coverage, and inquiring about defensive driving course discounts. Additionally, shopping your policy around with an independent agent every few years ensures you remain competitive in the market.
What should I do immediately after a car accident in Arcadia, FL?
First, ensure everyone is safe and move to a secure location if possible. Call 911 to report the accident and request law enforcement and medical assistance. Exchange insurance and contact information with the other drivers involved, take clear photographs of the scene and vehicle damage, and notify your insurance company as soon as possible to initiate the claims process. Avoid admitting fault at the scene.
Next Steps and Action Plan
Protecting yourself on Arcadia roads begins with a proactive review of your current coverage levels. If your policy only reflects Florida's mandatory minimums, contact a licensed local agent or compare quotes online to add adequate Bodily Injury Liability, comprehensive, and collision protection. Evaluate your deductible comfort levels, confirm that all household drivers are properly accounted for, and ensure your chosen carrier maintains strong financial stability ratings. Taking these steps today safeguards your financial future against unforeseen road and weather risks.