ADM Milling whole life insurance is a voluntary permanent life insurance benefit offered to employees of Archer Daniels Midland (ADM) and its milling divisions. Unlike standard group term life insurance, this policy provides a guaranteed death benefit and builds cash value over time, remaining in force for the employee’s entire life as long as premiums are paid, even after leaving the company.
In 2026, ADM Milling employees continue to navigate a complex landscape of corporate benefits. Among the most misunderstood of these offerings is the voluntary whole life insurance program. While most employees are familiar with the "Basic Life" insurance provided at no cost by the employer, the whole life option serves a different strategic purpose in a long-term financial plan. This article provides a technical breakdown of how this coverage functions, the mechanics of cash value accumulation, and the specific advantages of securing permanent coverage through a payroll-deduction model.
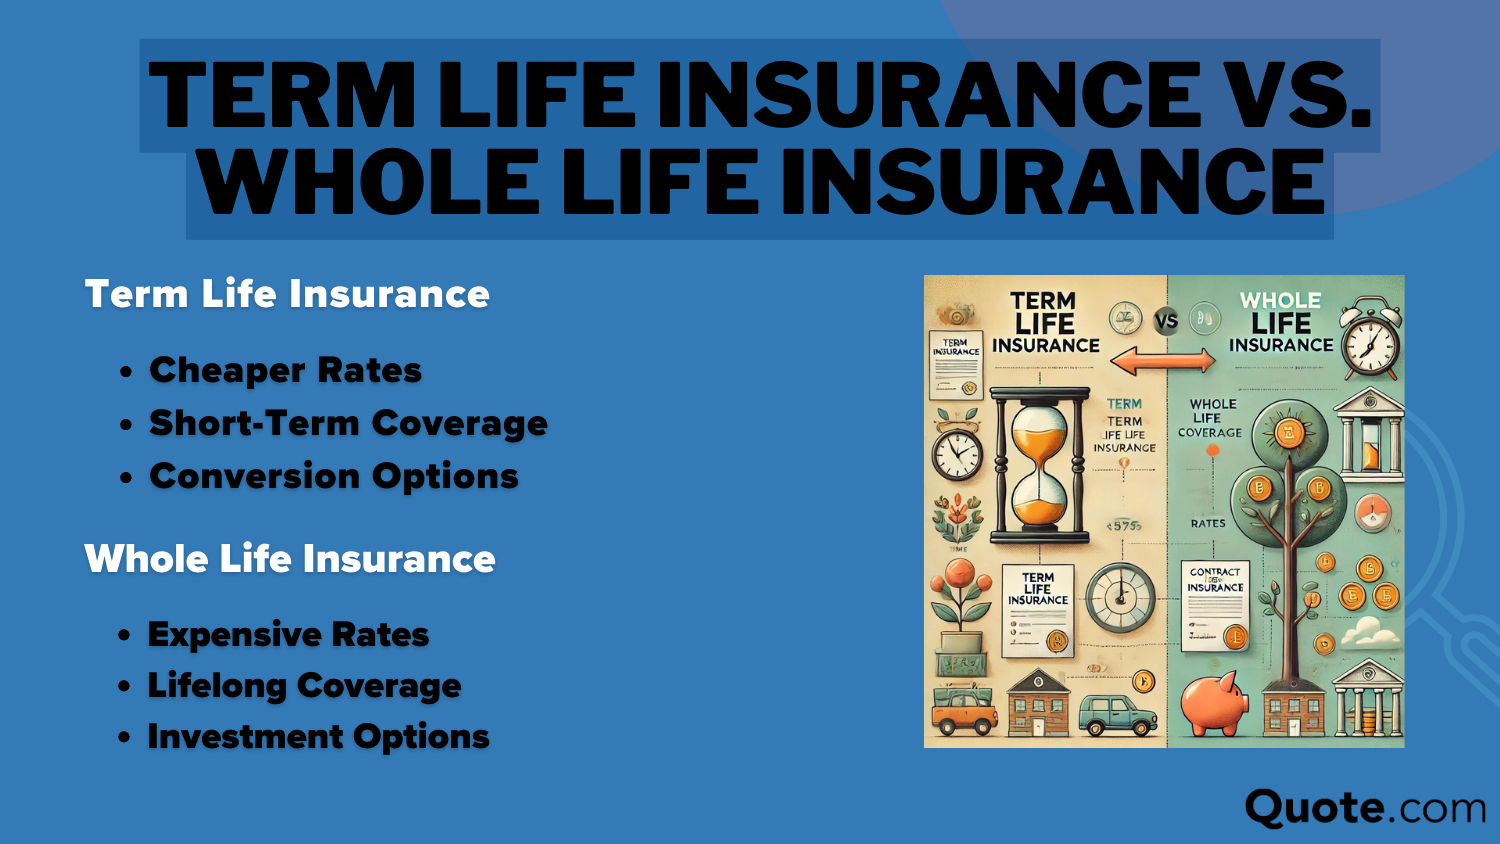
The Distinction Between Term and Whole Life at ADM
To understand ADM Milling’s whole life offering, one must first distinguish it from the basic and supplemental term life insurance options typically available during the annual open enrollment period.
Basic Group Term Life Insurance
For most ADM Milling employees, the company provides a "Basic Term Life" policy, often equal to one or two times the employee’s annual salary. This is a "pure protection" product. It has no cash value, and the coverage typically ends or becomes prohibitively expensive when the employee leaves ADM or retires. In 2026, this remains the foundational layer of protection, but it is not permanent.
Voluntary Whole Life Insurance
The voluntary whole life insurance program is an "individual" policy that is marketed and administered through the group. Because it is a whole life product, it is designed to last until age 100 or beyond. The premiums are fixed at the age of purchase and do not increase as the employee gets older. This stability is a significant draw for milling professionals who want to lock in a "final expense" or "legacy" benefit that will not disappear upon retirement.
Core Features of the ADM Milling Whole Life Policy
The whole life policies offered to ADM staff are structured to provide three specific guarantees that are not present in term products: guaranteed death benefits, guaranteed level premiums, and guaranteed cash value growth.
Fixed Premiums and Level Benefits
Once an employee enrolls in the ADM Milling whole life plan, the premium is locked in. Even if the employee’s health declines later or they reach an advanced age, the cost remains the same. This "level premium" structure is essential for long-term budgeting. In the 2026 benefits environment, where healthcare and term insurance costs often fluctuate based on inflationary pressures, the fixed nature of this policy provides a predictable financial anchor.
Cash Value Accumulation
A portion of every premium dollar paid into the ADM Milling whole life policy is directed into a cash value account. This account grows on a tax-deferred basis according to a set interest rate determined by the insurance carrier. Over several decades, this cash value can grow into a significant sum that the employee can access through policy loans or withdrawals for various needs, such as emergency repairs, educational expenses, or supplementing retirement income.
Portability and Ownership
Perhaps the most critical feature of the ADM Milling whole life plan is its portability. Standard group benefits are "owned" by the employer's master contract. However, voluntary whole life is typically an individual contract. If an employee leaves ADM Milling to join another firm or decides to retire in 2026, they can "port" the policy. They simply transition from payroll deduction to direct billing with the insurance carrier, maintaining the same coverage and premium rate they had while employed.
Eligibility and the Enrollment Process
Enrollment in whole life insurance is generally available to full-time ADM Milling employees during their initial hiring window or during the annual open enrollment period.
Guaranteed Issue vs. Evidence of Insurability
During specific "Guaranteed Issue" windows—usually when a new hire first joins ADM Milling—employees may be able to secure a certain amount of whole life coverage without undergoing a medical exam or answering health questions. This is a massive advantage for individuals with pre-existing conditions who might otherwise be denied coverage or charged "rated" (higher) premiums in the private market.
If an employee waits until a later enrollment period to sign up, or if they request a coverage amount above the guaranteed limit, they may be required to provide Evidence of Insurability (EOI). This typically involves a health questionnaire and, in some cases, a brief medical screening. In 2026, many of these processes have been digitized, allowing for real-time underwriting decisions through the ADM benefits portal.
Coverage for Family Members
Many ADM Milling benefit packages allow employees to purchase whole life coverage for their spouses and eligible dependent children or grandchildren. These "rider" options or standalone policies for family members allow the employee to establish a financial foundation for their children at very low, locked-in rates based on the child's young age.
The Financial Mechanics of Cash Value
The cash value component of an ADM Milling whole life policy is more than just a savings account; it is a contractually guaranteed asset.
Tax-Deferred Growth
Under current internal revenue codes (specifically Section 7702), the growth of the cash value within a life insurance policy is not taxed as it accumulates. This allows the interest to compound more efficiently than a traditional savings account, where interest is taxed annually. For high-earning ADM employees, this provides an additional tax-advantaged "bucket" alongside their 401(k) and HSA.
Accessing Policy Values
If an employee needs to access the funds, they have two primary methods:
- Policy Loans: The owner can borrow against the cash value. The insurance company charges interest on the loan, but there is no requirement to "qualify" for the loan based on credit score. If the loan is not repaid before the insured dies, the outstanding balance is subtracted from the death benefit.
- Surrender: If the employee no longer needs the insurance, they can cancel the policy and receive the "Cash Surrender Value." However, this terminates the death benefit protection.
Comparing ADM Insurance Options
When deciding how much whole life insurance to carry, it is helpful to compare it against the other life insurance options available in the ADM Milling benefits suite.
| Feature | Basic Term Life | Supplemental Term | Voluntary Whole Life |
|---|---|---|---|
| Payer | ADM (Employer) | Employee | Employee |
| Premium Cost | $0 (Free to employee) | Increases with age | Locked-in at age of purchase |
| Cash Value | None | None | Accumulates over time |
| Portability | Limited/None | Ends at termination | Fully Portable |
| Duration | While employed | While employed | Permanent (Life) |
| Underwriting | None | Required for high amounts | Guaranteed Issue (limits apply) |
Strategic Use Cases for ADM Milling Employees
Why would an ADM Milling professional choose a whole life policy over a cheaper term policy? There are several specific financial strategies where whole life is superior.
1. Final Expenses and Estate Planning
Term insurance is designed to replace income during working years. However, everyone will eventually face "final expenses" (funeral costs, legal fees, medical bills). Since whole life is guaranteed to pay out regardless of when death occurs, it is the ideal tool for covering these permanent liabilities.
2. The "Pension Maximization" Strategy
For long-tenured ADM employees who may have access to older pension structures, whole life insurance can play a role in "Pension Maximization." An employee can choose the "Life Only" pension payout (which is the highest monthly amount) and use a whole life policy to provide the survivor benefit for their spouse, rather than accepting a lower pension payout with a survivor option.
3. Supplementing the 401(k)
In 2026, many employees find they are hitting the contribution limits on their 401(k) plans. A whole life policy provides a non-correlated asset class. While the 401(k) is subject to stock market volatility, the whole life cash value is guaranteed to grow every year, providing a "safe money" hedge in the overall portfolio.
Troubleshooting and Managing Your Policy
Managing an ADM Milling whole life policy in 2026 is primarily done through the corporate benefits portal or the third-party administrator (TPA) hired by ADM.
Changing Beneficiaries
One of the most common mistakes employees make is failing to update their beneficiaries after a "life event" such as marriage, divorce, or the birth of a child. Because whole life is a permanent asset, it is vital to review these designations annually during open enrollment.
Payroll Deduction Discrepancies
Since premiums are deducted directly from the ADM Milling paycheck, it is important to monitor pay stubs to ensure deductions are accurate. If an employee takes a leave of absence or goes on disability, they may need to make "direct-bill" arrangements with the insurance company to prevent the policy from lapsing.
Filing a Claim
In the event of the insured's death, beneficiaries must contact the ADM Human Resources department or the specific insurance carrier (e.g., MetLife, MassMutual, or Unum, depending on the current 2026 contract holder). They will need a certified copy of the death certificate to initiate the payout process. Most claims are processed within 10 to 30 days.
Frequently Asked Questions
Can I increase my coverage amount at any time?
Usually, you can only increase your coverage during the annual open enrollment period or following a "Qualifying Life Event" (QLE) like a marriage or birth. Increasing coverage will likely require Evidence of Insurability (EOI), and the premium for the additional coverage will be based on your current age.
What happens to my ADM whole life policy if the company is sold?
Because the voluntary whole life policy is an individual contract between you and the insurance carrier, it generally remains in force even if ADM Milling undergoes a corporate restructuring or sale. You would simply continue paying premiums directly to the insurer if payroll deduction is no longer available.
Is the cash value growth guaranteed?
Yes. Whole life policies include a "Guaranteed Cash Value" schedule that is part of the original contract. While some policies may also pay non-guaranteed dividends (depending on the carrier's performance), the core growth outlined in your policy illustration at the time of purchase is contractually obligated.
Is the death benefit taxable to my heirs?
Under current federal law in 2026, life insurance death benefits are generally received by beneficiaries income-tax-free. However, if the death benefit is paid to the "estate" rather than a named individual, it may be subject to estate taxes if the total estate exceeds federal or state thresholds.
Can I borrow from my cash value immediately?
Most whole life policies require a "vesting" period—often two to three years—before enough cash value has accumulated to allow for a policy loan. You should review your specific policy illustration to see exactly when "loanable" values become available.
What is the difference between this and "Group Universal Life"?
While both are permanent, Universal Life has flexible premiums and the cash value is often tied to current interest rates or market indices. ADM Milling’s "Whole Life" is more rigid but offers more "guarantees," meaning the premium and death benefit will never change as long as the contract is followed.
Summary of Recommendations
For ADM Milling employees, the whole life insurance option is a powerful tool for long-term financial security, but it should be used correctly. It is not a replacement for a 401(k), nor is it usually a replacement for a large term life policy during the years when you have a mortgage and young children.
Next Steps for Employees:
- Audit Your Current Coverage: Log into the ADM benefits portal to see if you are currently enrolled in "Basic," "Supplemental," or "Voluntary Whole Life."
- Assess Your "Final Expense" Need: If you are nearing retirement or have health concerns that make private insurance expensive, consider locking in a whole life policy now to ensure you have permanent coverage.
- Review Beneficiaries: Ensure your primary and contingent beneficiaries are up to date for 2026.
- Evaluate Portability: If you are planning to leave ADM Milling soon, contact the insurance carrier to find out the exact steps required to take your policy with you.