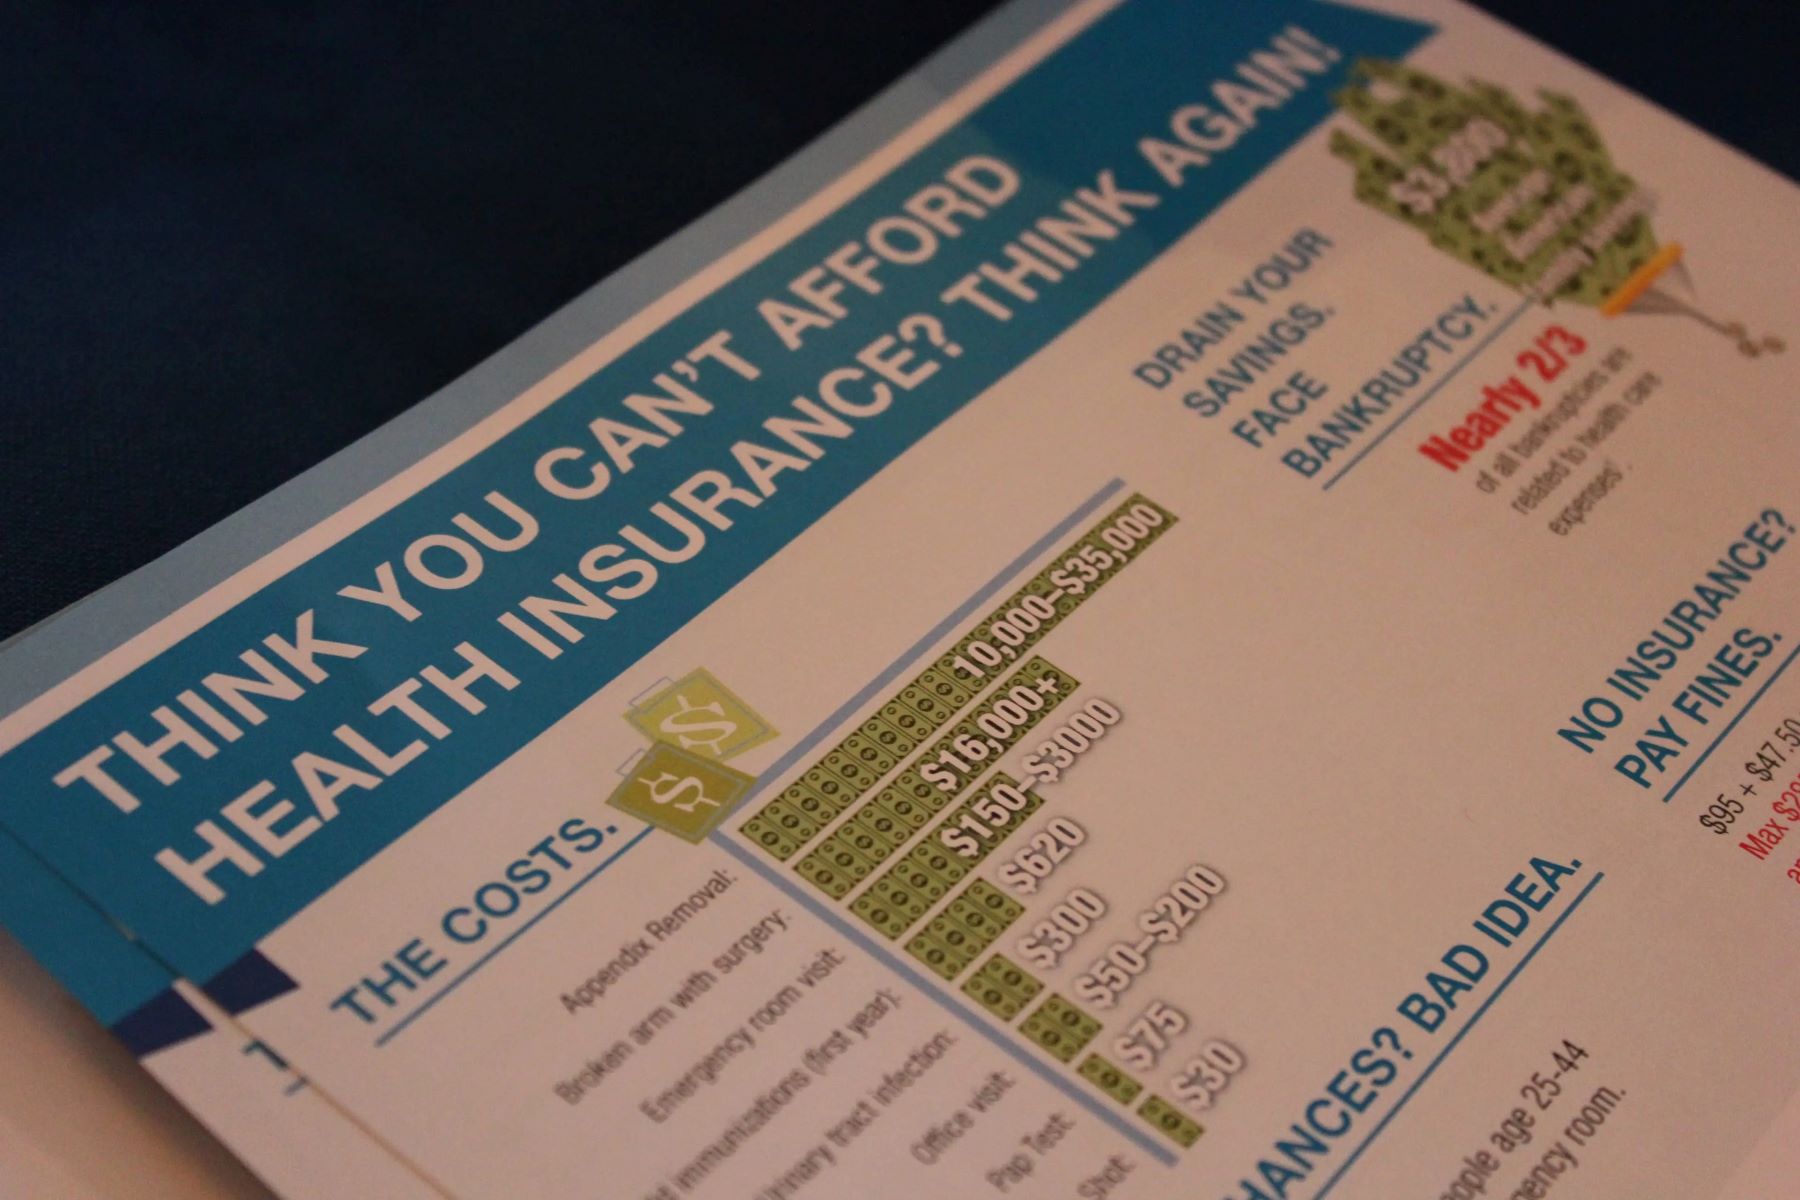
Adding a child to health insurance after a qualifying life event requires notifying your insurer or state marketplace, submitting required verification documents, and selecting or updating your plan within a strict 60-day window. Missing this window generally forces families to wait until the next open enrollment period.
Navigating the healthcare system after welcoming a new child through birth, adoption, or foster placement can feel overwhelming, particularly when combined with the everyday demands of a growing family. While health insurance rules are notoriously complex, understanding the specific mechanics of adding a dependent ensures your newborn or newly placed child receives uninterrupted medical care. Federal regulations and standard employer-sponsored health plans provide clear pathways for modifying coverage outside the standard annual enrollment cycle. By understanding the precise timelines, documentation requirements, and administrative procedures involved, you can secure comprehensive medical protection for your child efficiently and without unnecessary financial risk.
Understanding Qualifying Life Events and Enrollment Windows
The foundation of changing your health insurance outside the standard annual enrollment period rests on a concept known as a Qualifying Life Event (QLE). Under standard regulations set by the Health Insurance Portability and Accountability Act (HIPAA) and the Affordable Care Act (ACA), the arrival of a child is universally recognized as a major life change that triggers a Special Enrollment Period (SEP).
A Special Enrollment Period is a designated window of time—typically 60 days from the date of the event—during which you are legally permitted to enroll in a new health plan or add a dependent to your existing employer-sponsored or individual marketplace plan. For a biological child, the qualifying event date is the exact date of birth. For adopted children or children placed for adoption or foster care, the date is typically the date of placement, the date legal custody is established, or the finalization date, depending on state and plan guidelines.
Failing to act within this 60-day window carries severe consequences. If you miss the deadline, you generally cannot add your child to your policy until the next annual open enrollment period, leaving the child uninsured unless they qualify for public programs like Medicaid or the Children's Health Insurance Program (CHIP). These public programs do not adhere to the standard employer open enrollment cycle and accept applications year-round based on household income and eligibility.
Comparing Coverage Pathways for a New Child
When adding a child to health insurance, families typically navigate one of three primary administrative channels. Each pathway features distinct timelines, documentation standards, and cost implications.
| Coverage Pathway | Primary Administrative Body | Enrollment Window | Key Documentation Required |
|---|---|---|---|
| Employer-Sponsored Plan | Human Resources / Benefits Administrator | 30 to 60 days (often plan-specific) | Birth certificate, hospital proof of birth, or adoption papers |
| State Marketplace (ACA) | State Health Exchange or Healthcare.gov | Exactly 60 days from the event | Social Security Number (SSN), proof of birth/adoption |
| Medicaid / CHIP | State Department of Health and Human Services | Year-round eligibility | Income verification, proof of residency, birth certificate |
Steps to Add a Child to an Employer-Sponsored Plan
For most working families, employer-sponsored group health insurance is the primary vehicle for healthcare coverage. Managing this process requires close coordination with your company's human resources (HR) or benefits department.
1. Notify Human Resources Immediately
Do not wait for formal documentation, such as an official state-issued birth certificate, to notify your employer. Many state vital statistics offices take several weeks to process and issue birth certificates. Instead, inform your HR department immediately upon the child's birth or placement to log the Qualifying Life Event. HR will provide the necessary change-of-status forms and verify your specific plan’s notification deadline, which is sometimes shorter than the federal maximum (for instance, 30 days instead of 60 days).
2. Gather Supporting Documentation
While you can initiate the request early, your insurer will ultimately require official proof of the dependent’s eligibility. Acceptable documents typically include:
- A hospital-issued declaration of birth or birth certificate.
- Official court documents verifying adoption or foster care placement.
- A Social Security Number (SSN), though many insurers allow you to submit this retroactively once issued by the Social Security Administration.
3. Choose the Appropriate Coverage Tier
Adding a child moves you from "Employee Only" or "Employee + Spouse" to "Employee + Children" or "Family" coverage. This structural shift will alter your payroll deductions. Review the premium differences among available plan tiers (such as Bronze, Silver, or Gold equivalents within your employer's offerings) to ensure the chosen tier aligns with your family’s projected medical utilization for pediatric checkups, vaccinations, and potential specialist visits.
Retroactive Coverage and Medical Claims
One of the most critical protections for parents adding a newborn or newly adopted child to health insurance is the rule regarding retroactive coverage. Under federal guidelines for employer-sponsored plans and marketplace policies, coverage for a newborn is retroactive to the exact date of birth. For adopted children, coverage typically retroacts to the date of placement.
This retroactive application means that any medical services, hospital stays, pediatrician visits, or emergency interventions your child receives immediately following birth or placement are fully covered by the policy, provided you successfully complete the enrollment process within the designated 60-day window.
- Hospital Billing Coordination: Hospitals routinely bill the mother’s insurance for labor and delivery services during the birth admission. Once the child is formally added to the policy, the hospital will generate a separate set of claims billed directly under the newborn’s unique member ID or retroactive policy segment.
- Managing Pre-Existing Conditions: Under modern insurance regulations, health plans cannot deny coverage or charge higher premiums to children based on pre-existing conditions or congenital health issues identified at birth.
Special Considerations for Marketplace and Public Insurance
Families who purchase individual health insurance through federal or state health insurance marketplaces face a slightly different administrative workflow compared to employer-sponsored group plans.
Navigating Healthcare.gov or State Exchanges
If you purchase insurance through an individual marketplace, you must log into your account, report a life change (selecting "having a child" or "adoption"), and submit the update within 60 days of the event. The marketplace system will prompt you to upload digital copies of supporting documentation. Once verified, you can choose to keep your current plan and simply add the child, or switch to a different tier or plan category that better suits a larger family size.
Interaction with Medicaid and CHIP
If a family’s household income falls below specific state thresholds, a newborn or adopted child may qualify for state-administered Medicaid or the Children's Health Insurance Program (CHIP). Unlike private insurance, Medicaid and CHIP applications are processed on a rolling, year-round basis. In many states, a child born to a mother who is already enrolled in Medicaid during pregnancy is automatically enrolled in Medicaid for the first year of life, bypassing the standard application hurdle entirely.
Common Pitfalls and Troubleshooting
Navigating insurance bureaucracy during the sleep-deprived weeks following a child's arrival leaves room for administrative errors. Avoiding common mistakes prevents catastrophic coverage gaps.
- Missing the 60-Day Deadline: This is the single most frequent error. If you realize on day 61 that you forgot to notify your employer or marketplace, insurers and employers rarely grant exceptions, leaving you responsible for out-of-pocket medical costs until the next open enrollment period.
- Delaying Because of Missing SSNs: Parents often wait to enroll their child until they receive a Social Security card in the mail. This is unnecessary. Most HR departments and health plans allow you to submit enrollment paperwork immediately and provide the SSN later once it is issued.
- Failing to Verify Provider Networks: When adding a child, ensure that your preferred pediatrician or family practice accepts the specific network tier associated with your updated insurance policy (such as an HMO versus a PPO network).
Expert Guidance and Next Actions
To ensure a seamless transition and protect your family from unforeseen medical debt, take immediate, methodical action following the arrival of a child.
- Contact HR or your marketplace representative within the first week to establish the qualifying life event and request the required paperwork.
- Request a Social Security Number promptly through the hospital's birth registration process or your local Social Security office.
- Audit your first few post-enrollment paystubs or marketplace invoices to confirm that the premium adjustment is accurate and that your child appears on the active roster of covered dependents.
By adhering strictly to these timelines and administrative requirements, you secure comprehensive financial and medical protection for your new dependent from day one.