Generally, you do not need to report a group term life insurance death benefit payout on your Form 1040 because life insurance proceeds are not considered taxable income by the IRS. However, if the insurance company pays you interest on the benefit, that interest must be reported as taxable interest on Line 2b.
Receiving a payout from a group term life insurance policy is often a bittersweet moment, occurring during a period of significant personal loss. In the 2026 tax filing season, understanding the nuances of how the Internal Revenue Service (IRS) treats these funds is essential for accurate reporting and peace of mind. While the core benefit is usually tax-free, specific circumstances—such as interest accumulation or installment-based distributions—can trigger reporting requirements on Form 1040.
Understanding Group Term Life Insurance and Taxability
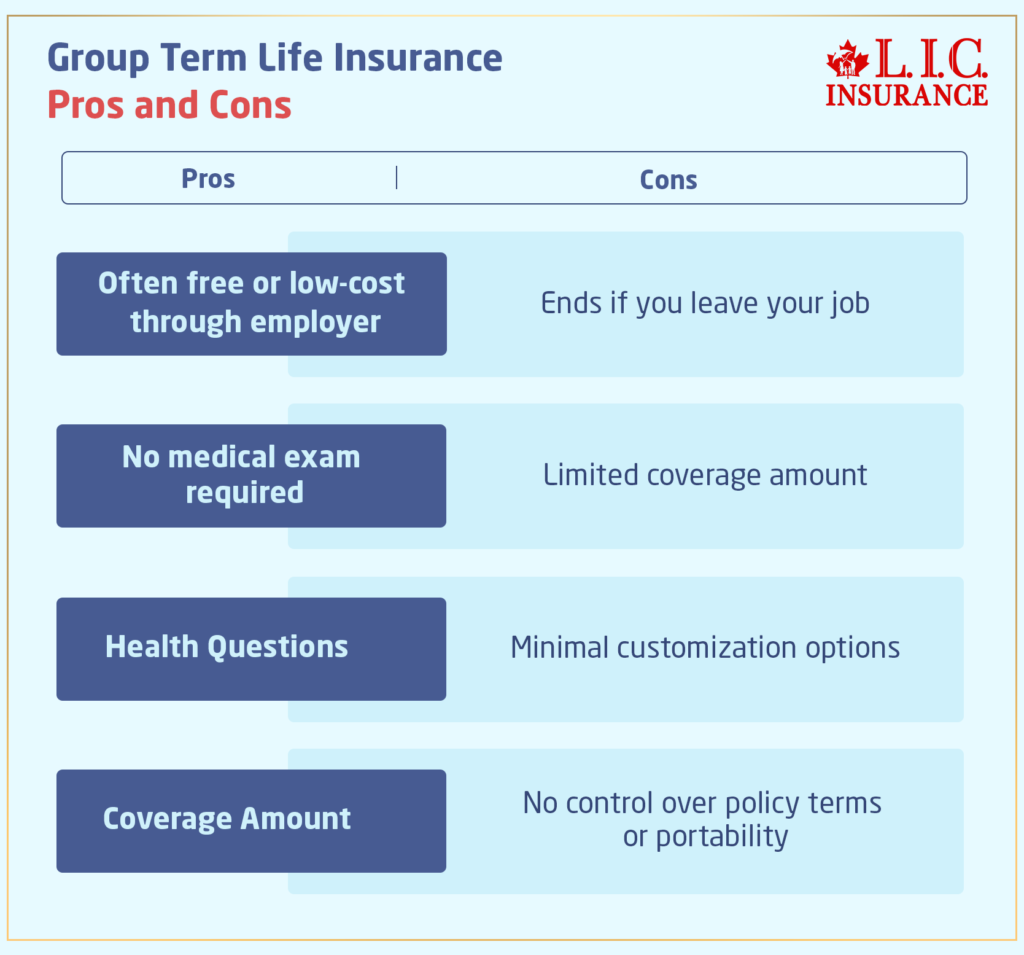
Group term life insurance is a type of life insurance coverage offered by employers or organizations to a large group of people, typically employees. It provides a death benefit for a specific "term" or period, usually as long as the individual remains employed by the company. For the beneficiary, the most critical question is whether this payout constitutes "gross income."
Under Section 101(a)(1) of the Internal Revenue Code, amounts received under a life insurance contract, if paid by reason of the death of the insured, are generally excluded from gross income. This means that if you receive a $100,000 lump-sum payout from a group term policy after a loved one passes away, that $100,000 is yours to keep without sharing a portion with the IRS. Because it is excluded from gross income, there is no specific line on Form 1040 to enter the lump-sum amount.
The $50,000 Rule Confusion
Many taxpayers get confused by the "$50,000 rule" associated with group term life insurance. This rule applies to the employee while they are alive, not to the beneficiary receiving the payout. Employers can provide up to $50,000 of group term life insurance as a tax-free fringe benefit. The "imputed cost" of any coverage above $50,000 is treated as taxable income to the employee and is reported on their Form W-2.
However, once the insured person passes away, the actual death benefit paid to the beneficiary is tax-free regardless of whether the coverage was $10,000 or $1,000,000. The taxation of premiums during the employee's life does not make the payout taxable to the beneficiary.
When You MUST Report a Payout on Form 1040
While the principal amount of the life insurance payout is non-taxable, there are two primary scenarios where you will have to enter information on your 2026 tax return.
1. Interest Earned on the Death Benefit
It is common for insurance companies to take a few weeks or months to process a claim. If the insurer holds the funds for a period after the date of death, they are legally required in many jurisdictions to pay interest on those funds.
This interest is considered taxable income in the year it is received. Even if the $100,000 payout is tax-free, the $200 in interest the insurance company added to the check is not.
- Where to put it: You report this interest on Form 1040, Line 2b (Taxable interest).
- Documentation: You should receive a Form 1099-INT from the insurance company if the interest earned is $10 or more. Even if you do not receive a 1099-INT, you are still responsible for reporting the interest.
2. Installment Payments or Annuity Options
Some beneficiaries choose to receive the life insurance payout in installments rather than a single lump sum. This is often referred to as a "settlement option." In this scenario, each payment consists of two parts: a portion of the tax-free principal and a portion of taxable interest.
The insurance company will calculate the "exclusion ratio," which determines how much of each payment is a return of the non-taxable death benefit. The remaining portion represents the earnings (interest) on the funds being held by the insurer.
- Where to put it: The taxable portion of these payments is generally reported on Form 1040, Line 4b (Taxable amount of IRA distributions/pensions and annuities), depending on how the insurer classifies the distribution.
- Documentation: You will likely receive a Form 1099-R showing the gross distribution and the taxable amount.
How to Handle Specific Forms on Your 2026 Return
Navigating tax forms can be daunting, especially when dealing with six-figure sums that you "know" shouldn't be taxed but feel like they should be reported. Here is how to handle the documents you might receive.
Form 1099-INT: Interest Income
If the insurance company pays you interest, they will send you a 1099-INT. Box 1 of this form will show the interest amount. When filing your 2026 taxes, you will enter this on Line 2b. If your total taxable interest exceeds $1,500, you will also need to fill out Schedule B (Form 1040) to list the name of the insurance company and the amount.
Form 1099-R: Distributions from Insurance Contracts
If you receive a 1099-R, it means the insurance company has determined that part of your payout is taxable. This typically happens with "excess" distributions or interest components of an annuity-style payout.
- Box 1 (Gross distribution): This is the total amount you received.
- Box 2a (Taxable amount): This is the part you must report on your 1040. If this box is empty or says "Taxable amount not determined," you may need to consult the insurance company’s benefit statement or a tax professional.
The No-Form Scenario
If you receive a check for $50,000 and no tax forms (no 1099-INT or 1099-R), it is almost certain that the entire amount is a tax-free death benefit. In this case, you do not enter anything on your Form 1040. You do not even need to attach a note or the death certificate to your return. The IRS does not require you to report non-taxable gifts or life insurance proceeds unless they meet specific, rare international reporting requirements (which generally wouldn't apply to a domestic group term policy).
Comparison of Tax Treatments for Life Insurance Components
| Component | Tax Status | Reporting Line on Form 1040 | Document Received |
|---|---|---|---|
| Principal Death Benefit (Lump Sum) | Non-Taxable | Not Reported | None |
| Interest on Delayed Payout | Taxable | Line 2b | Form 1099-INT |
| Installment Payments (Principal) | Non-Taxable | Not Reported | Form 1099-R (Box 1 only) |
| Installment Payments (Interest) | Taxable | Line 4b | Form 1099-R (Box 2a) |
| Employer-Paid Premiums >$50k | Taxable (to Employee) | Reported on W-2 | Form W-2 (Box 12, Code C) |
Common Pitfalls and Expert Guidance
Even though the rules are generally favorable, there are nuances that can lead to errors on your tax return.
The "Transfer-for-Value" Rule
While group term life insurance is almost always provided as a benefit of employment, if a life insurance policy was sold or transferred to another party for "valuable consideration" (money or something of value), the death benefit might become partially taxable. This is rare in group settings but can happen if a policy is assigned in a way that violates the transfer-for-value rules. If the policy was simply a standard benefit provided by an employer, this rule likely does not apply.
State Tax Considerations
For the 2026 filing year, most states follow federal guidelines regarding the taxability of life insurance proceeds. This means if it is tax-free federally, it is tax-free at the state level. However, a few states have unique inheritance or estate tax rules. It is important to check the specific Department of Revenue guidelines for your state of residence, especially if the payout is exceptionally large (exceeding several million dollars).
Estate Tax vs. Income Tax
It is vital to distinguish between income tax (Form 1040) and estate tax (Form 706). Even if the payout is not taxable income to you as the beneficiary, it may be included in the gross estate of the deceased person for federal estate tax purposes. In 2026, the federal estate tax exemption remains high, but if the deceased had a very high net worth, the estate—not the beneficiary—might owe taxes on the value of the life insurance policy if the deceased "owned" the policy or had "incidents of ownership" at the time of death.
Frequently Asked Questions
Do I need to report a $250,000 life insurance payout as income?
No, the $250,000 principal amount of a life insurance payout is generally not considered income and should not be reported on Form 1040. The IRS excludes death benefits from gross income under Section 101(a). You only report the interest earned on that money, if any, which usually arrives as a separate amount or is noted on a 1099-INT.
The insurance company didn't send me a 1099 form. Does that mean I'm safe?
If the payout was purely the death benefit with no interest, the insurance company is not required to send a Form 1099, because there is no taxable income to report. However, if you know you received interest (e.g., your payout was $50,500 but the policy was for $50,000), you are legally obligated to report that $500 as interest income on Line 2b, even without a form.
What if the life insurance was part of a 401(k) or pension plan?
If the group term life insurance was held within a qualified retirement plan, the rules are slightly different. The "net value" of the death benefit (the total payout minus the cash value of the policy) is generally tax-free. However, any portion representing the cash value or previously untaxed contributions might be taxable. In these cases, the plan administrator will almost always provide a Form 1099-R with Box 2a filled out to show the taxable portion.
Is the payout from a "supplemental" group life policy taxed differently?
No. Whether it is the basic coverage provided by the employer or "supplemental" coverage that the employee paid for themselves through payroll deductions, the death benefit remains tax-free to the beneficiary. The tax treatment of the premiums (whether paid with pre-tax or post-tax dollars) only affects the employee’s W-2 while they are alive; it does not change the tax-exempt status of the payout for the beneficiary.
Can I put the payout into an IRA to avoid taxes?
Since the payout is already tax-free, you cannot "roll it over" into an IRA to get a tax deduction. However, you can use the money to make a standard IRA contribution if you have "earned income" for the year, subject to the annual contribution limits set for 2026. You cannot deposit the entire $100,000 into a traditional IRA to claim a $100,000 deduction.
Final Recommendations for 2026 Filers
When preparing your 2026 tax return, follow these practical steps to ensure you handle your group term life insurance payout correctly:
- Gather Your Documents: Look for a "Benefit Statement" or "Settlement Letter" from the insurance company. This will show the total amount paid and break it down between the "Death Benefit" and "Interest Paid."
- Wait for 1099s: Do not file your taxes until at least mid-February. If the insurer paid you taxable interest, they have until January 31st to mail your 1099-INT or 1099-R.
- Identify Interest: If you see an amount for interest, enter it on Line 2b of Form 1040.
- Ignore the Principal: If there is no interest and no 1099 form, simply leave the life insurance payout off your tax return entirely.
- Consult a Professional for Large Estates: If the total estate of the deceased exceeds the 2026 federal exemption limit, or if you are the executor, consult with a tax professional regarding Form 706 (Estate Tax), even if the beneficiary doesn't owe income tax.
By following these guidelines, you can ensure that you are fully compliant with IRS regulations while retaining the full financial benefit of the insurance policy during a difficult time of transition.