American Express rental auto insurance coverage provides financial protection against theft or damage to a rental vehicle when the rental is charged to an eligible American Express card. Most cards include "Secondary" coverage for free, while the "Premium Car Rental Protection" program offers "Primary" coverage for a flat per-rental fee.
Navigating the complexities of credit card travel benefits can be daunting, especially when standing at a rental car counter being pressured to buy expensive daily waivers. In 2026, American Express (Amex) remains a leader in this space, offering some of the most robust protections available to cardmembers. However, understanding the difference between the standard "built-in" benefit and the optional "premium" enrollment is essential to avoid significant out-of-pocket expenses in the event of an accident.
This guide explores the mechanisms of American Express car rental insurance, detailing how to activate it, what it covers, and the critical limitations you must know before you drive off the lot.
Understanding the Two Tiers of Amex Rental Coverage
American Express does not offer a single "one-size-fits-all" insurance product. Instead, it provides two distinct levels of protection. Choosing the right one depends on your existing personal auto insurance policy and your tolerance for risk.
1. Car Rental Loss and Damage Insurance (Standard/Secondary)
This is the base-level benefit included with most American Express cards at no additional cost. It is technically referred to as secondary coverage.
- How it works: If you have a personal auto insurance policy, the Amex benefit only pays for costs that your primary insurer does not cover. This typically includes your personal insurance deductible and any "excess" charges.
- The Caveat: Because it is secondary, you must first file a claim with your own insurance company. This could potentially lead to an increase in your personal insurance premiums.
- Cost: $0 (Included with the card annual fee).
2. Premium Car Rental Protection (Primary)
This is an optional program that cardmembers must specifically enroll in. Once enrolled, the coverage becomes primary, meaning it pays out before any other insurance you have.
- How it works: In the event of an accident or theft, you file the claim directly with American Express. You do not need to involve your personal insurance company, which protects your personal premiums from rising.
- Cost: A flat fee per rental period (not per day). As of 2026, this typically ranges from $12.25 to $24.95 for the entire rental (up to 42 consecutive days).
- Key Advantage: It offers higher coverage limits (up to $100,000 for some cards) and includes coverage for certain luxury vehicles that are excluded under the standard plan.
Mandatory Requirements for Coverage Activation
Simply owning an American Express card does not automatically guarantee that you are covered the moment you sit in a rental car. To ensure the insurance is valid in 2026, you must adhere to several strict procedural requirements.
Use the Eligible Amex Card
The entire rental transaction must be charged to your American Express card. This includes the initial reservation and the final payment. If you use a different card for the deposit or use loyalty points from a rental company that result in a $0 balance, the coverage may be voided. If you use Amex Membership Rewards points to pay for the rental, you are generally covered, provided the points were redeemed through the Amex Travel portal.
Decline the Rental Company’s CDW/LDW
When the rental agent asks if you want to purchase their Collision Damage Waiver (CDW) or Loss Damage Waiver (LDW), you must explicitly decline it. If you accept the rental company's insurance, the American Express coverage will not apply, as you have essentially paid another entity to take on the risk.
Authorized Drivers
The person named on the American Express card must be the primary renter. Coverage typically extends to "additional authorized drivers" as long as they are listed on the rental agreement. If an unlisted driver is behind the wheel during an incident, Amex will deny the claim.
What is Covered? (And What is Not)
The scope of American Express rental insurance is focused primarily on the vehicle itself. It is a "Loss and Damage" policy, which differs significantly from a full "Liability" policy.
Included Protections
- Collision and Damage: Repair costs if the car is damaged in an accident.
- Theft: The actual cash value of the vehicle if it is stolen.
- Vandalism: Damage resulting from intentional acts by others.
- Loss of Use: Charges the rental company applies for the time the car is out of service being repaired.
- Storage and Towing: Reasonable fees to move and house the damaged vehicle.
Critical Exclusions: The Liability Gap
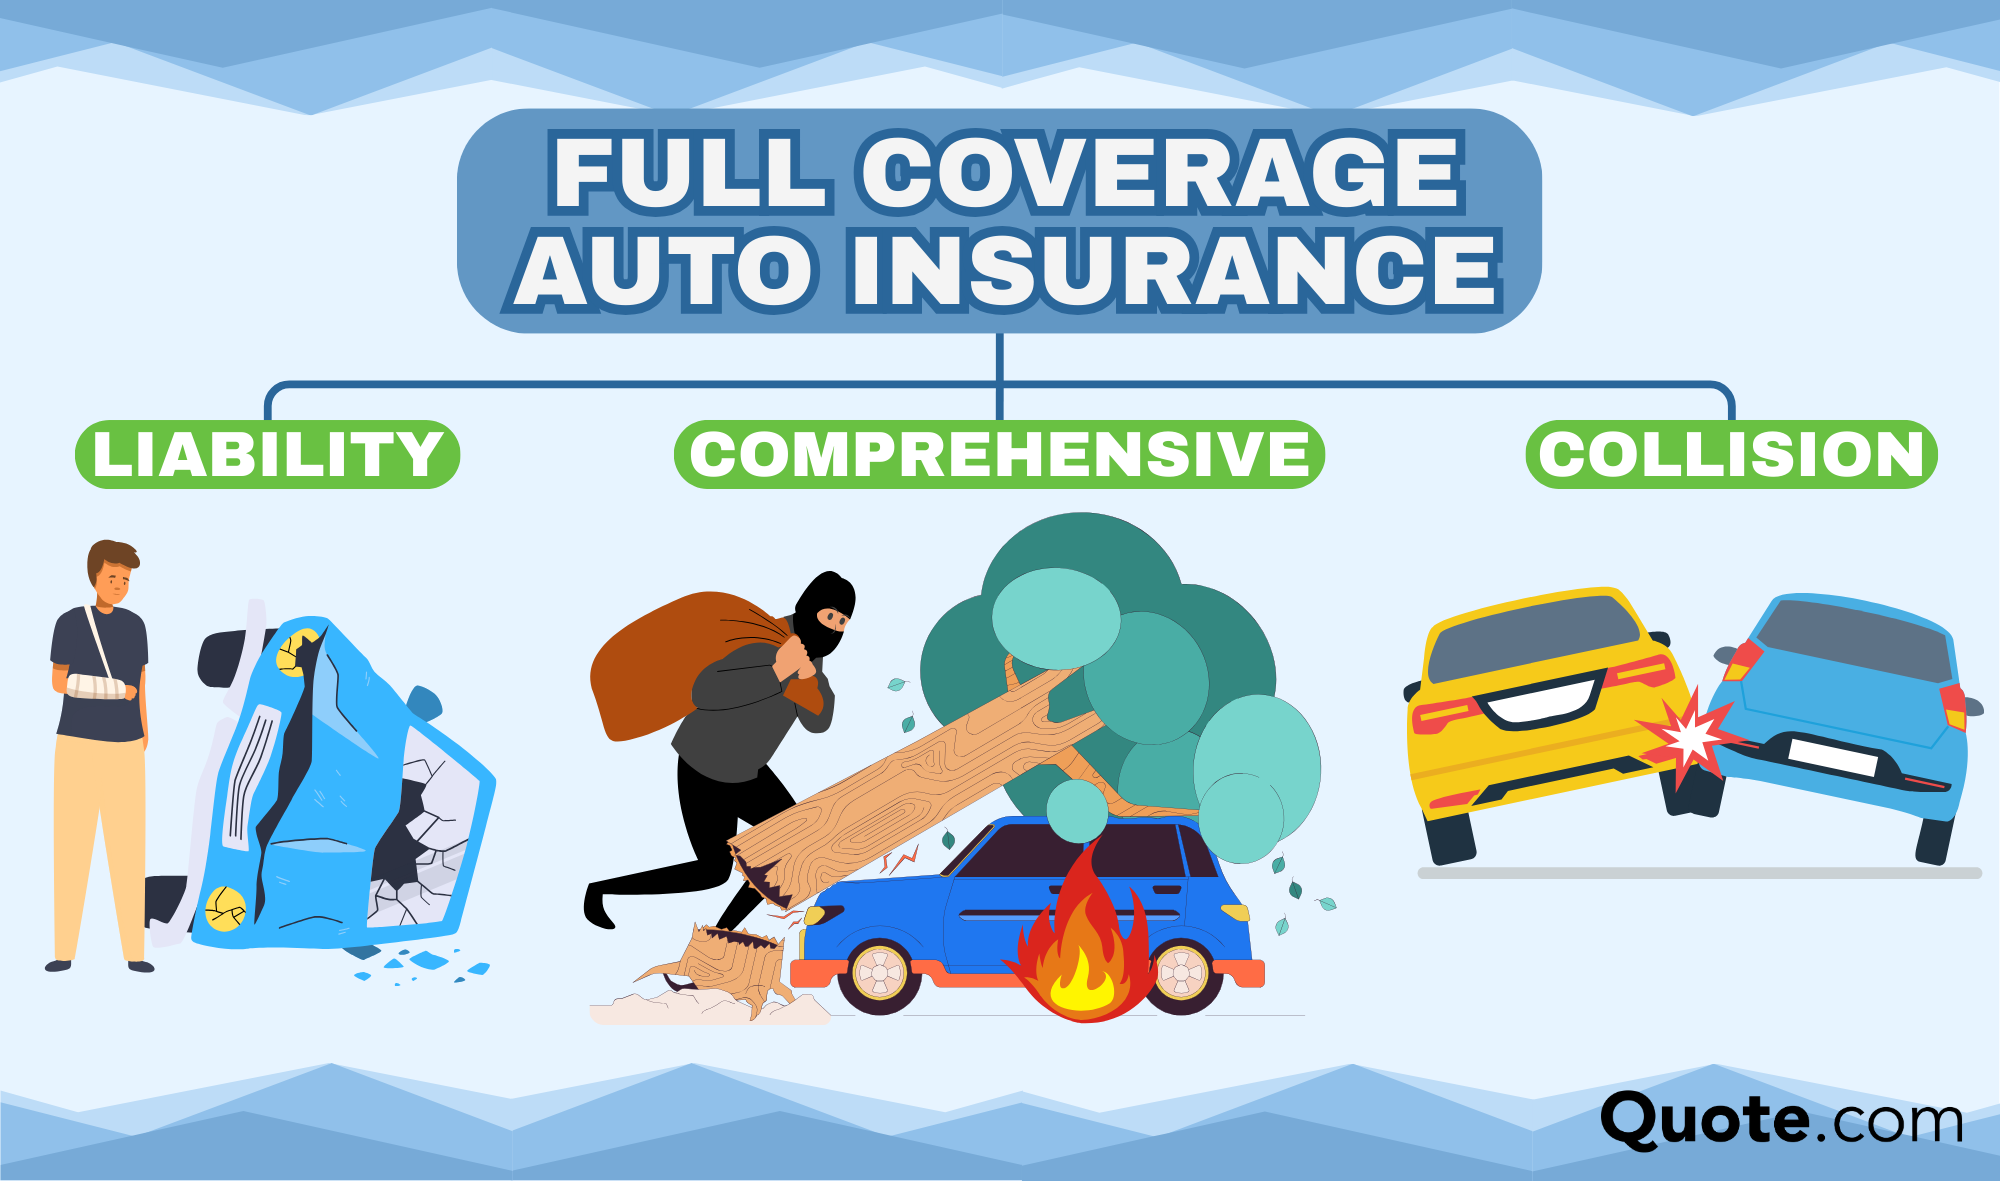
Perhaps the most important takeaway is that Amex rental insurance does not provide liability coverage.
- No Third-Party Property Damage: If you hit someone else's car, Amex will pay to fix your rental, but they will not pay to fix the other person's car.
- No Third-Party Medical: If you injure another driver or a pedestrian, Amex does not cover their medical bills or legal fees.
- Your Own Medical: While some Amex plans offer a small amount for accidental death or dismemberment, they do not serve as a replacement for health insurance or Personal Injury Protection (PIP).
Recommendation: For liability protection, you must rely on your personal auto insurance policy or purchase the "Supplemental Liability Insurance" offered at the rental counter.
Vehicle and Geographic Limitations
In 2026, American Express maintains specific lists of excluded vehicles and prohibited countries. Checking these lists before you travel is vital to ensuring your coverage remains intact.
Excluded Vehicle Types
Standard coverage often excludes high-value or specialty vehicles. Common exclusions include:
- Luxury and Exotic Cars: Vehicles manufactured by Aston Martin, Bentley, Ferrari, Lamborghini, and Maserati.
- Off-Road Vehicles: Any vehicle driven on unpaved roads (which voids most rental agreements anyway).
- Trucks and Vans: Full-size cargo vans, moving trucks (like U-Haul), and large passenger vans (usually those seating more than 8 or 9 people).
- Antique Cars: Any vehicle over 20 years old or that has not been manufactured for 10 years.
Geographic Exclusions
While American Express provides "global" coverage, local laws in certain countries make it impossible for Amex to provide insurance. Historically, these countries have included:
- Italy
- Australia
- New Zealand
- Israel
- Ireland
- Jamaica
If you are renting in these locations, you must verify the current status in your 2026 Cardmember Agreement, as geopolitical changes or insurance regulations can shift these exclusions.
Comparison of Coverage Options
To help you decide whether to rely on your card’s built-in benefit or pay for the Premium protection, consider the following comparison.
| Feature | Standard (Secondary) | Premium (Primary) | Rental Company LDW |
|---|---|---|---|
| Cost | Free with Card | $12.25 – $24.95 per rental | $20 – $50 per day |
| Claim Priority | Secondary to personal insurance | Primary | Primary |
| Deductible | Covers your personal deductible | No deductible | No deductible |
| Max Coverage | $50,000 – $75,000 | Up to $100,000 | Full value of car |
| Duration | Up to 30 days | Up to 42 days | Length of rental |
| Liability | None | None | None (unless added) |
How to File a Claim with Amex
If an incident occurs, you must act quickly. The "window of opportunity" for filing paperwork is strict.
- Report the Incident: Contact the local authorities to get a police report. This is often a mandatory requirement for the claim to be processed.
- Notify the Rental Agency: Ensure they document the damage on their own forms.
- Call Amex Assurance: You should notify American Express as soon as possible, ideally within 48 to 72 hours. In 2026, this can be done via the Amex mobile app or by calling the number on the back of your card.
- Submit Documentation: You will typically be required to provide:
- A copy of the rental agreement (front and back).
- The "Check-in" and "Check-out" reports showing the condition of the car.
- An itemized repair bill or estimate.
- The police report.
- Photographs of the damage.
- Timeline: Most claims must be fully submitted within 60 to 90 days of the incident.
Frequently Asked Questions
Does Amex car rental insurance cover peer-to-peer rentals like Turo?
As of 2026, American Express generally does not cover peer-to-peer car-sharing services like Turo, Getaround, or Avail. These services are classified as "car-sharing" rather than "commercial rental agencies." Because you are renting a vehicle from a private individual, the standard "Car Rental Loss and Damage Insurance" terms typically do not apply.
Is the Premium Car Rental Protection fee per day or per trip?
The fee is per rental period. If you rent a car for 10 days, you pay the flat fee (e.g., $19.95) once at the beginning of the trip. This makes it significantly more cost-effective than the rental desk's LDW, which would charge you $19.95 or more every single day.
If I have the Amex Platinum Card, is the coverage different?
Yes. Higher-tier cards like the Platinum Card® or the Business Platinum Card® often come with higher coverage limits (e.g., $75,000 vs. $50,000 on the Gold Card). However, even for Platinum cardmembers, the built-in coverage remains secondary unless you specifically enroll in the Premium Car Rental Protection program.
Will Amex insurance cover me if I rent a Tesla or other EV?
In 2026, most standard Electric Vehicles (EVs) like the Tesla Model 3 or Model Y are covered under Amex policies, provided they do not exceed the MSRP limits defined in your specific card's terms. However, high-performance EVs (like a Lucid Air Sapphire or Tesla Roadster) may fall under the "Exotic" exclusion.
Do I need to enroll in Premium Protection every time I rent?
No. Once you enroll your card in the Premium Car Rental Protection program, it stays active. Every time you use that specific Amex card at a rental car agency, the flat fee will be automatically charged to your statement, and the primary coverage will be activated. You must remember to de-enroll if you no longer want the service.
Expert Recommendations for 2026
When deciding how to handle your rental insurance, follow these three steps to ensure maximum protection:
- Check Your Personal Policy: Call your primary auto insurance provider and ask if your current coverage extends to rentals. If it does, and you have a low deductible, the free secondary coverage from Amex may be sufficient.
- Evaluate the "Premium" Upgrade: If you have a high personal insurance deductible (e.g., $1,000 or $2,000), or if you simply do not want an accident to affect your personal insurance rates, the $12–$25 flat fee for Amex Premium Protection is one of the best values in the travel industry.
- Mind the Liability: Never assume your credit card protects you against lawsuits or damage to others. If you do not have a personal auto policy with liability coverage, you must purchase liability insurance directly from the rental company.
By understanding the technical nuances of American Express rental auto insurance coverage, you can save hundreds of dollars on "junk" fees at the rental counter while maintaining the peace of mind that your financial interests are protected on the road.