Atlanta life insurance general agencies serve as the primary infrastructure for independent agents, providing essential back-office support, specialized underwriting expertise, and access to diverse carrier portfolios. In 2026, these organizations remain widely misunderstood, often incorrectly viewed as unnecessary intermediaries rather than critical partners that enhance agent profitability and client coverage accuracy through centralized resources.
Understanding the reality of the General Agency (GA) model is vital for both veteran financial professionals and newcomers entering the Georgia insurance market. As the industry evolves with more sophisticated digital underwriting and shifting regulatory landscapes, several long-standing myths continue to circulate, clouding the actual value proposition of working with a localized Atlanta agency.
The Evolution of the Atlanta General Agency Model
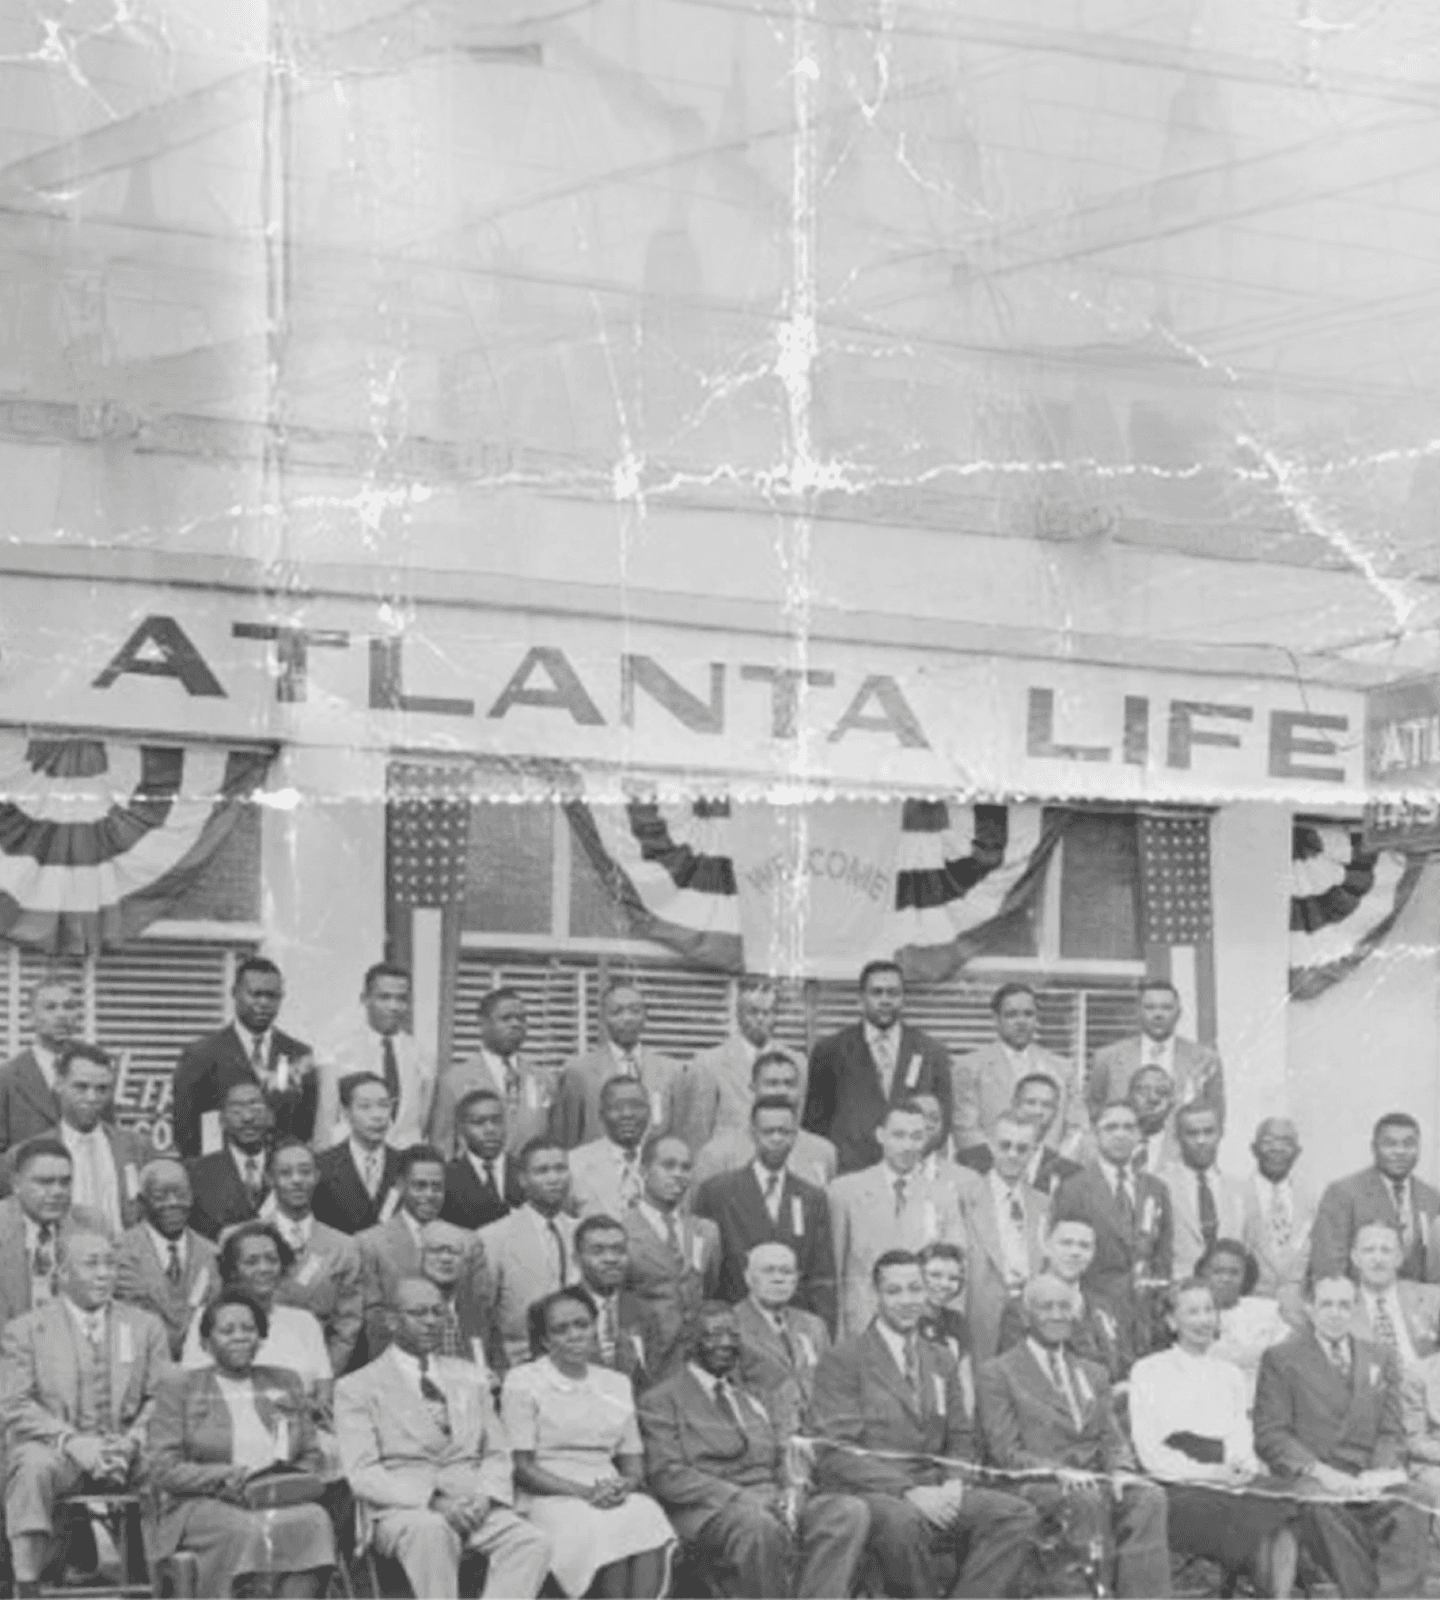
The term "Atlanta Life Insurance General Agency" carries significant historical and functional weight. Historically, the city was the birthplace of the Atlanta Life Insurance Company, founded by Alonzo Herndon, which set a precedent for institutional reliability and community-focused insurance services. While that specific company represents a singular historical entity, the broader "General Agency" model in Atlanta has expanded into a diverse ecosystem of Independent Marketing Organizations (IMOs) and Managing General Agents (MGAs).
In 2026, a General Agency functions as a bridge between the massive insurance carriers (such as Prudential, Transamerica, or Pacific Life) and the individual agent. These agencies are responsible for recruiting, training, and supporting agents, ensuring that every policy written complies with the current Georgia Department of Insurance regulations. The myths debunked below address the most common points of friction that prevent agents from leveraging these partnerships effectively.
Myth 1: General Agencies Reduce Agent Commissions
Perhaps the most persistent myth is that joining a General Agency means "giving up" a portion of your commission to the agency. Agents often believe that by going "direct" to a carrier, they would receive a higher percentage of the premium.
The Reality of Contract Levels
In reality, the insurance industry operates on a tiered contracting system. Carriers generally prefer to work with GAs because it offloads the cost of agent training, licensing oversight, and administrative support. Because a GA brings a high volume of business to the carrier, they are granted "overrides"—compensation paid by the carrier to the agency that does not come out of the agent's pocket.
In 2026, most Atlanta-based GAs offer "Street Level" commissions, which are the standard highest levels available to independent producers. In many cases, a GA can actually negotiate a higher contract level for a high-performing agent than the agent could get on their own, because the agency has the collective bargaining power of hundreds of producers.
The Value of "Net" Income vs. "Gross" Percentage
Agents must look at their net income rather than their gross commission percentage. A GA provides free or subsidized software, CRM tools, and case management. If an agent goes direct, they often have to pay out-of-pocket for:
- Advanced quote engines and comparison tools.
- Application tracking software.
- Underwriting consultations.
- Compliance review services.
When these overhead costs are factored in, agents working with an Atlanta GA typically see a higher net profit margin than those attempting to manage a solo enterprise.
Myth 2: GAs Are Unnecessary Middlemen in the Digital Age
With the rise of "InsurTech" and direct-to-consumer platforms, some argue that the General Agency model is obsolete. This myth assumes that technology has replaced the need for human intervention in the insurance procurement process.
Complex Case Management
While a simple term life policy for a healthy 30-year-old might be automated, the bulk of high-value insurance work in Atlanta—such as estate planning, premium financing, and buy-sell agreements—requires sophisticated manual intervention.
Atlanta GAs employ specialized case managers who act as advocates. When a carrier’s automated system flags an applicant for a medical "table rating" (a higher price due to health risks), a GA's underwriting team steps in. They may shop the medical file to five different carriers simultaneously to find the one that will offer a "Standard" or "Preferred" rating for that specific condition. This level of advocacy is something a digital portal cannot provide.
Regulatory Compliance and Oversight
The Georgia Office of Commissioner of Insurance and Safety Fire maintains strict standards for agent conduct and policy disclosures. In 2026, the complexity of these regulations has only increased. GAs provide a necessary layer of protection by vetting the marketing materials and sales practices of their agents. They ensure that the "Atlanta life insurance" products being sold meet the latest fiduciary standards, protecting the agent from E&O (Errors and Omissions) claims.
Myth 3: Captive Agencies Provide More Stability Than Independent GAs
New agents are often told that "captive" agencies (where you work for only one company, like State Farm or Northwestern Mutual) offer more stability and better leads than the independent GA route.
Ownership of the "Book of Business"
The primary difference lies in the ownership of the client list. In most captive environments, the company owns the data. If the agent leaves, they cannot take their clients with them. In the independent General Agency model prevalent in Atlanta, the agent typically owns their "book of business" from day one. This creates long-term wealth and an asset that can eventually be sold or passed down to heirs.
Product Diversity as a Safety Net
Stability in 2026 is defined by the ability to pivot. If a single carrier decides to raise its rates or stop offering a specific product (like Long-Term Care riders), a captive agent is stuck. An agent affiliated with an Atlanta independent GA can simply switch the client to another carrier within the agency's portfolio. This diversity protects the agent's income stream from market volatility.
Myth 4: "Atlanta Life" Refers Only to One Historical Company
There is a common misconception that "Atlanta Life Insurance" refers exclusively to the historic Atlanta Life Insurance Company founded in 1905. While that company is a cornerstone of the city's business history, the term now describes a much broader market.
The Modern Atlanta Market
Today, Atlanta is recognized as a major "Fintech" and "Insurtech" hub. The city hosts regional headquarters for dozens of global carriers and hundreds of independent general agencies. When people search for "Atlanta life insurance," they are often looking for the local expertise that understands Georgia's specific probate laws, tax environment, and demographic needs.
| Feature | Captive Agency | Independent General Agency (GA) |
|---|---|---|
| Carrier Access | Single Carrier | Multiple Carriers (30+) |
| Ownership | Usually the Carrier | Usually the Agent |
| Underwriting | Rigid/Internal | Flexible/Advocacy-based |
| Commission | Often lower (with base salary) | Higher (Street Level + Overrides) |
| Training | Standardized | Specialized/Market-specific |
| Technology | Proprietary | Choice of Industry-leading Tools |
Myth 5: Technology in Atlanta GAs Lags Behind National Firms
Some believe that to get the best technology, you must work with a massive national IMO located in a tech hub like San Francisco or New York. This ignores Atlanta’s status as "Transaction Alley," where a significant percentage of all U.S. financial transactions are processed.
Localized Tech Integration
In 2026, Atlanta-based GAs utilize AI-driven predictive underwriting tools that are integrated with local medical data exchange networks. These tools allow agents to give clients "instant-issue" decisions on policies that previously took six weeks to underwrite. Furthermore, local agencies often provide more personalized tech support, helping agents integrate these tools into their specific workflows rather than offering a one-size-fits-all national platform.
The Role of Specialty Markets in Atlanta
Atlanta's diverse economy—spanning film, technology, and logistics—requires life insurance solutions that aren't found in standard "off-the-shelf" policies. General Agencies in the city have developed niches in:
- Executive Bonus Plans (162 Plans): Catering to the city's growing corporate leadership.
- Key Person Insurance: Protecting the numerous startups in the Midtown and Tech Square areas.
- Foreign National Coverage: Serving the international population connected through Hartsfield-Jackson International Airport.
By debunking the myth that GAs only handle "basic" life insurance, agents can see the opportunity to move into these high-ticket, specialized markets that require the deep carrier relationships only a GA provides.
Training and Mentorship Myths
The final myth to address is the idea that General Agencies don't provide "real" training. Some believe that unless you are in a corporate office, you are left to learn on your own.
In 2026, the most successful Atlanta GAs have moved beyond simple "product knowledge" sessions. They now offer:
- Joint Field Work: Experienced mentors go on appointments with new agents to close complex cases.
- Digital Marketing Labs: Training on how to generate leads through social media and SEO within the Georgia market.
- Advanced Sales Concepts: Workshops on the National Association of Insurance Commissioners (NAIC) model laws and how they affect estate planning.
Frequently Asked Questions
Is the historic Atlanta Life Insurance Company still active in 2026?
The legacy of the Atlanta Life Insurance Company continues to influence the market, though its operational structure has evolved through various acquisitions and management groups over the decades. In 2026, the brand remains an important symbol of the city's financial history, but it is one of many entities operating within the massive Atlanta life insurance sector.
Do I need a special license to work with an Atlanta General Agency?
You need a standard Georgia Life and Health Insurance Counselor or Agent license issued by the Georgia Department of Insurance. Once licensed, you "contract" with the GA, which then "appoints" you with various carriers. The GA typically assists with the paperwork for these appointments at no cost to the agent.
How do Atlanta GAs handle lead generation?
Most GAs do not provide "free" leads, as those are often low-quality. Instead, they provide the infrastructure for you to build your own lead generation systems. However, some Atlanta agencies offer co-op lead programs where they split the cost of high-quality, vetted leads with the agent, or provide access to exclusive "orphan" policyholder lists from carriers they represent.
Can I work with more than one General Agency at a time?
Technically, yes. Independent agents are not usually bound by "exclusive" contracts unless they have signed a specific agreement for a specialized product. However, most agents find it more efficient to consolidate their business with one or two primary GAs to maximize their production bonuses and simplify their back-office workflows.
What is the difference between an MGA and a GA in Atlanta?
A Managing General Agent (MGA) typically has more authority from the insurance carrier, including the ability to perform underwriting functions or settle claims. A General Agency (GA) focuses more on the sales, marketing, and agent support side. In the 2026 Atlanta market, many firms use these terms interchangeably, but it is important to ask which specific authorities the agency holds.
Are commissions paid by the agency or the carrier?
In the vast majority of cases, the insurance carrier pays the agent directly via electronic funds transfer. The General Agency receives their override separately from the carrier. This ensures transparency and ensures the agent is paid on time, regardless of the agency's internal finances.
Strategic Recommendation
For insurance professionals in the Atlanta area, the path to growth in 2026 involves choosing a General Agency that functions as a true partner rather than a simple contract-holder. Look for an agency that offers a robust technology stack, a dedicated underwriting advocate, and a clear path for owning your book of business.
Before signing a contract, verify the agency's standing with the Better Business Bureau and speak with current agents about their experience with case management response times. Debunking these myths is the first step toward building a scalable, independent insurance practice that leverages the unique economic strengths of the Atlanta metropolitan area.