In 2026, the average cost for full coverage auto insurance on a 2019 model-year vehicle in New Mexico typically ranges between $1,200 and $1,500 per year. This price bracket applies primarily to drivers with clean records and good credit scores, reflecting the vehicle's depreciated market value balanced against New Mexico's unique regional risk factors.
Obtaining a premium within the $1,200 to $1,500 range requires a nuanced understanding of how New Mexico’s insurance landscape operates. As a 2019 vehicle is now seven years old, its actual cash value (ACV) has stabilized, which generally lowers the cost of collision and comprehensive premiums compared to newer models. However, New Mexico continues to face challenges regarding high rates of uninsured motorists and specific localized risks like property crime and weather-related incidents. To maintain a budget-friendly premium while ensuring robust protection, drivers must navigate state-specific mandates and utilize available discounts effectively.
Understanding the $1,200 to $1,500 Price Point in 2026
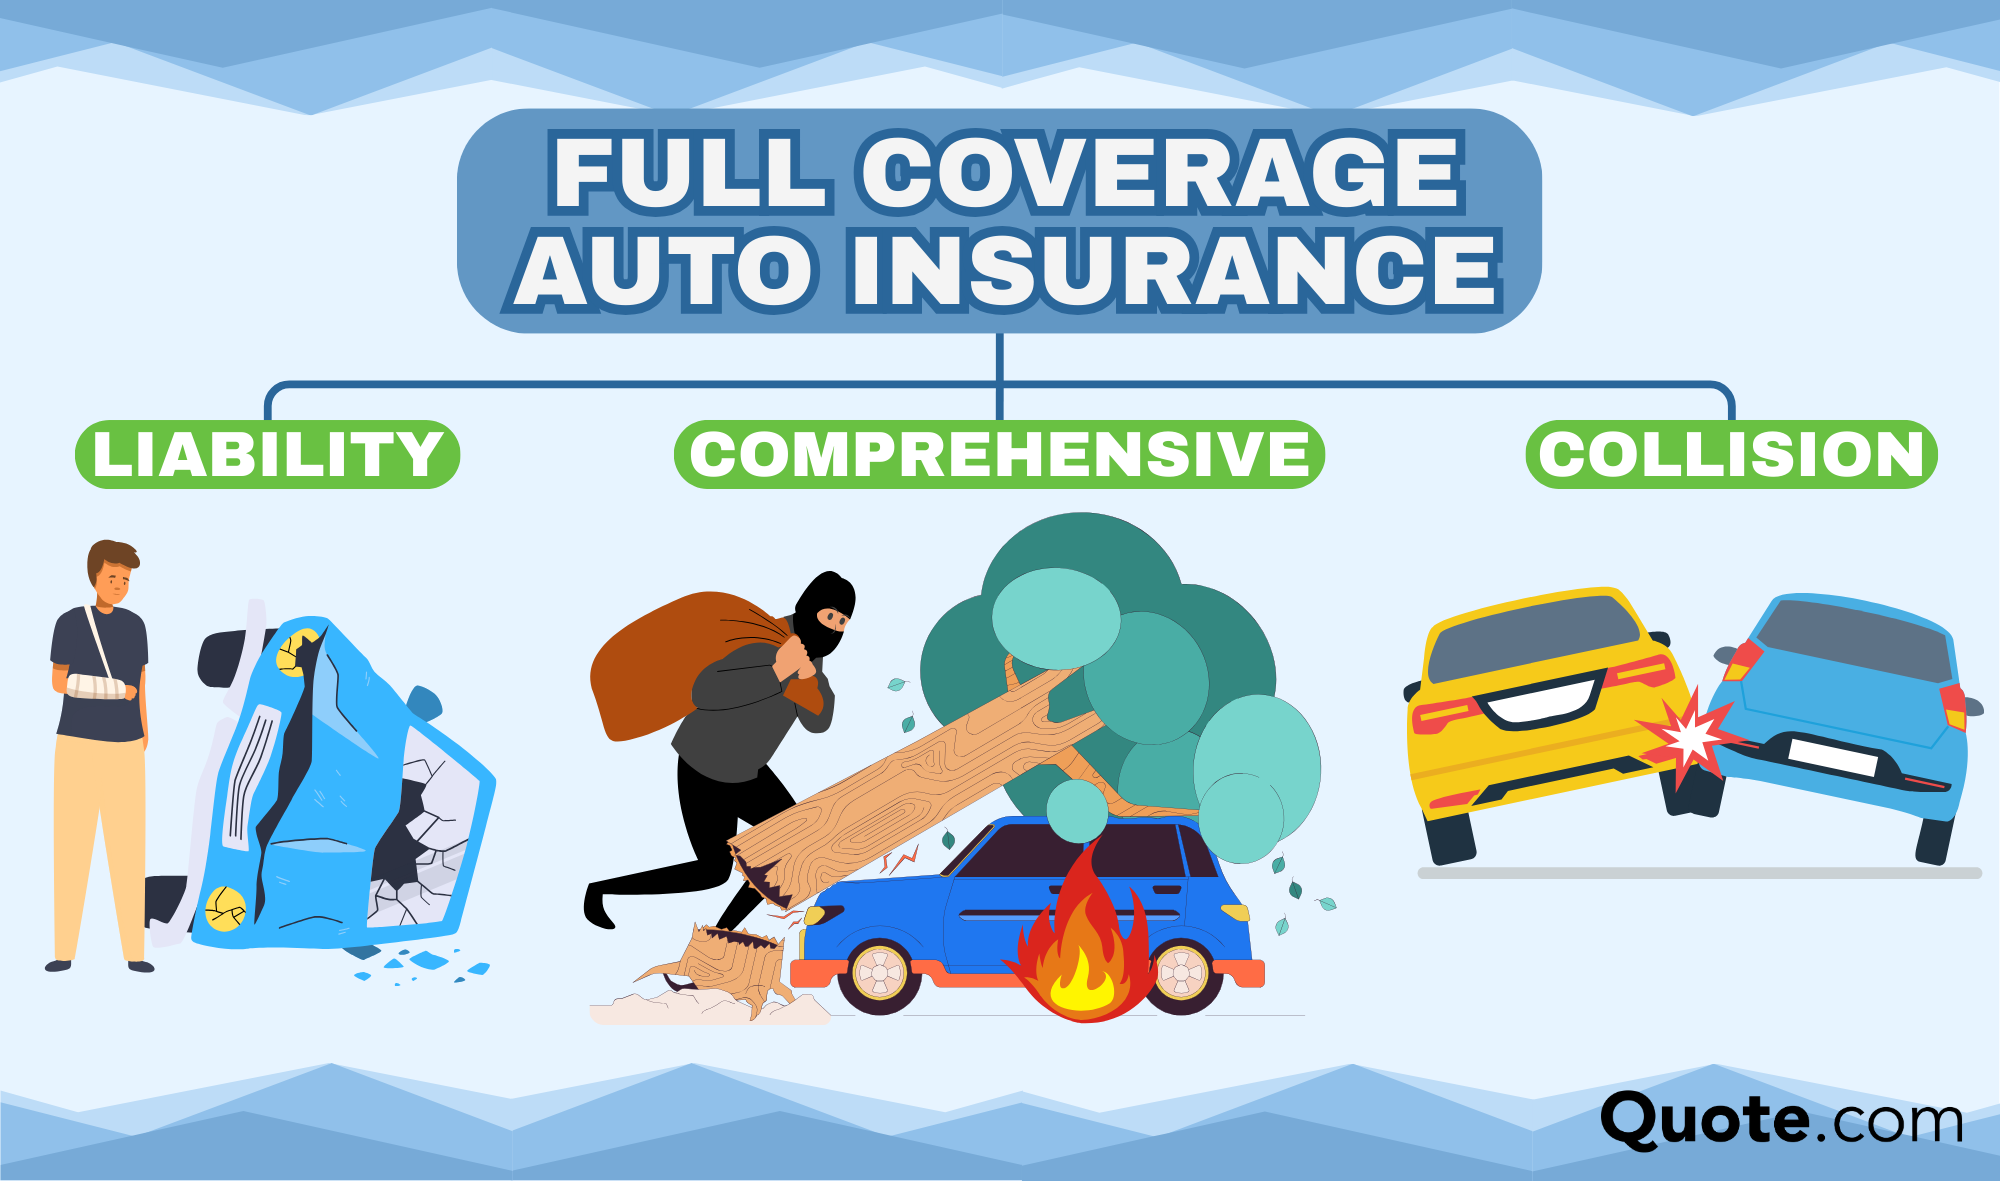
The $1,200 to $1,500 annual premium range represents a "sweet spot" for many New Mexico motorists. At approximately $100 to $125 per month, this rate typically covers a 2019 sedan or mid-sized SUV under a "full coverage" umbrella. While the term "full coverage" is not a formal legal classification, in the industry, it refers to a policy that includes state-mandated liability plus physical damage protections (collision and comprehensive) and, crucially for New Mexico, Uninsured/Underinsured Motorist (UM/UIM) coverage.
Several factors contribute to why a 2019 vehicle fits comfortably into this pricing tier in 2026:
- Depreciation and Replacement Cost: By 2026, a 2019 vehicle has undergone significant depreciation. Because collision and comprehensive claims are paid out based on the vehicle's current market value, the insurer's potential liability is lower than it was when the car was new.
- Safety Technology Standards: 2019 was a pivotal year for the standardization of Advanced Driver Assistance Systems (ADAS). Most 2019 models come equipped with automatic emergency braking and lane-departure warnings, which reduce the frequency of accidents and qualify the vehicle for modern safety discounts.
- Repair Parts Availability: Seven years after production, aftermarket and recycled parts for 2019 models are widely available. This reduces the cost of repairs compared to 2025 or 2026 models that might require expensive OEM-only components and specialized calibration.
Components of a Full Coverage Policy in New Mexico
To achieve a price between $1,200 and $1,500, you are likely looking at a policy with standard limits. New Mexico law requires minimum liability limits of 25/50/10 ($25,000 for bodily injury per person, $50,000 per accident, and $10,000 for property damage). However, a full coverage policy in this price range usually exceeds these minimums to provide meaningful protection.
Liability Coverage (Bodily Injury and Property Damage)
Liability remains the foundation of your premium. In New Mexico, which follows a traditional tort system, the driver at fault is responsible for the damages. If you carry 50/100/50 limits—higher than the state minimum—you are better protected against lawsuits. For a 2019 vehicle, liability often accounts for 40% to 50% of the total premium.
Collision Coverage
This pays for damage to your 2019 vehicle resulting from an accident, regardless of fault. Since the vehicle is seven years old, the cost of collision coverage is lower than for a new car, but it is still necessary if you want to avoid a total financial loss in a wreck. Choosing a $500 or $1,000 deductible is often the key to keeping the total annual cost under the $1,500 mark.
Comprehensive Coverage
Often called "other than collision," this covers theft, vandalism, fire, and weather damage. New Mexico's climate—including hail in the plains and high theft rates in urban centers like Albuquerque—makes comprehensive coverage vital. For a 2019 model, comprehensive is relatively affordable but remains a significant contributor to the $1,200–$1,500 total.
Uninsured/Underinsured Motorist (UM/UIM)
New Mexico consistently ranks among the states with the highest percentage of uninsured drivers. According to the Insurance Research Council, nearly one in five New Mexico drivers may lack insurance. Consequently, UM/UIM is a critical component of any "full coverage" quote. While you can technically reject this in writing, doing so is highly discouraged. A $1,200–$1,500 budget usually has enough room to include $25,000/$50,000 of UM/UIM coverage.
Geographic Variations Within New Mexico
The cost of insuring a 2019 vehicle is not uniform across the state. Your ZIP code is one of the most influential factors in determining whether your quote lands at the bottom ($1,200) or the top ($1,500) of the expected range.
- Albuquerque and Bernalillo County: Due to higher traffic density and higher rates of vehicle theft, premiums here often push toward the $1,500 limit. Drivers in the 87102 or 87121 ZIP codes may even see quotes slightly higher if they have any recent claims.
- Santa Fe and Las Cruces: These mid-sized urban areas typically see rates right in the middle of the range. The risk profile is lower than Albuquerque but higher than rural counties.
- Rural New Mexico (e.g., Catron or Union Counties): In less populated areas, the lower risk of collisions and theft often results in premiums closer to the $1,200 mark. However, long commute distances can sometimes offset these savings.
Impact of Driver Profile on 2026 Premiums
While the vehicle (a 2019 model) and the location (NM) set the baseline, the driver's personal profile determines the final number. To stay within the $1,200 to $1,500 range, a driver generally needs to meet several criteria.
The Role of Credit-Based Insurance Scores
New Mexico allows insurance companies to use credit-based insurance scores to help determine premiums. In 2026, this remains a legal and standard practice. A driver with an "Excellent" credit score may find a full coverage policy for $1,150, while a driver with "Poor" credit might see the same coverage for the same 2019 vehicle jump to $2,200.
Driving History and Claims
The $1,200–$1,500 range assumes a clean driving record for at least the past three to five years. A single at-fault accident or a major speeding ticket can increase premiums by 20% to 40% in the New Mexico market, quickly pushing the cost of a 2019 vehicle’s policy beyond $1,800.
Age and Experience
Drivers between the ages of 35 and 60 generally see the lowest rates. If the primary driver of the 2019 vehicle is under 25 or over 75, the premium is likely to exceed $1,500 due to the statistically higher risk associated with those age groups.
Comparative Annual Rates for a 2019 Vehicle in NM (2026 Estimates)
The following table illustrates how different profiles and carrier types might influence the annual cost of full coverage in New Mexico.
| Driver Profile | Estimated Annual Premium (Low) | Estimated Annual Premium (High) | Primary Cost Driver |
|---|---|---|---|
| Clean Record / Excellent Credit | $1,180 | $1,350 | Lowest risk tier in NM |
| Clean Record / Average Credit | $1,350 | $1,550 | Standard market rate |
| One Minor Infraction / Good Credit | $1,500 | $1,750 | Surcharge for risk |
| Rural Resident (Clean Record) | $1,100 | $1,250 | Low density / Low theft |
| Albuquerque Resident (Clean Record) | $1,400 | $1,650 | High theft / Collision risk |
Note: These estimates assume a $500 deductible for collision and comprehensive. Actual quotes will vary by specific vehicle trim and mileage.
Strategies to Secure a Rate Under $1,500
If your current quotes for a 2019 vehicle in New Mexico are exceeding $1,500, there are several verified methods to reduce the cost without sacrificing essential coverage.
1. Opt for Telematics Programs
In 2026, most major insurers in New Mexico offer "pay-how-you-drive" or "pay-as-you-go" programs. By using a smartphone app or a plug-in device to track your braking, acceleration, and mileage, you can secure discounts often ranging from 10% to 30%. For a 2019 vehicle, this is a highly effective way to pull a $1,600 quote down into the $1,300 range.
2. Bundle Home and Auto
The multi-policy discount remains one of the most significant ways to save. Bundling your 2019 vehicle insurance with a homeowners or renters policy in New Mexico can result in a 15% to 25% discount on the auto premium alone.
3. Adjust Your Deductibles
Moving from a $250 deductible to a $1,000 deductible can significantly lower the "physical damage" portion of your premium. Because a 2019 vehicle has lower overall value than a new car, carrying a higher deductible is a calculated risk that often pays off in annual premium savings.
4. Review Annual Mileage
As we move through 2026, many New Mexico employees continue to work in hybrid or remote capacities. If your 2019 vehicle is driven less than 7,500 miles per year, ensure your insurer has classified you as a "low-mileage" or "commuter" driver rather than a "pleasure" or "high-mileage" driver.
Vehicle-Specific Considerations for 2019 Models
The type of 2019 vehicle you are insuring greatly affects whether you stay within the $1,200–$1,500 range.
- Sedans (e.g., Toyota Camry, Honda Civic): These are the most likely to hit the $1,200–$1,300 mark due to lower repair costs and high safety ratings.
- Trucks (e.g., Ford F-150, Chevy Silverado): Full-sized trucks from 2019 often have higher premiums. This is due to their higher mass (which causes more damage in liability claims) and higher comprehensive costs (as trucks are frequent targets for theft in the Southwest).
- Luxury Vehicles (e.g., BMW 3 Series, Audi A4): Even at seven years old, these vehicles require more expensive parts and specialized labor. Insuring a 2019 luxury car for under $1,500 in New Mexico is challenging and usually requires a pristine driving record and high deductibles.
Legal and Regulatory Environment in New Mexico
The New Mexico Office of Superintendent of Insurance (OSI) regulates the rates and forms used by insurance companies in the state. By 2026, several regulatory updates may influence your costs:
- Rate Filings: Insurers must justify rate increases with the OSI. New Mexico has seen moderate rate stability compared to coastal states, helping keep the 2019 vehicle segment affordable.
- Uninsured Motorist Stacking: New Mexico allows "stacking" of UM/UIM coverage if you have multiple vehicles. If you own two cars, you can essentially combine the limits. While this increases the premium slightly, it provides significantly more value per dollar spent.
- Minimum Liability Discussions: There have been periodic legislative efforts to increase the 25/50/10 minimum limits. If these limits are raised by the legislature in 2026, all "full coverage" quotes will likely see a corresponding minor increase to comply with the new baseline.
Frequently Asked Questions
Is $1,200 to $1,500 a good price for full coverage in NM?
Yes. For a 2019 vehicle in 2026, this range is considered very competitive. It suggests that you are receiving the benefit of several discounts (such as a clean record or bundling) and that you are not being penalized for high-risk factors like poor credit or living in a high-crime ZIP code.
Does the trim level of my 2019 car affect these costs?
Absolutely. A 2019 base-trim model will be cheaper to insure than a top-tier trim with high-end tech or a larger engine. Higher trims have more expensive components to replace (like LED adaptive headlights or advanced sensors), which increases the comprehensive and collision portions of the premium.
Why is New Mexico insurance often more expensive than in neighboring states?
New Mexico faces higher-than-average rates of uninsured motorists and property crime (vehicle theft and burglary). Additionally, the state's geography leads to higher-speed travel on rural highways, which can increase the severity of accidents and the subsequent cost of liability claims.
Can I drop collision coverage on my 2019 vehicle to save money?
While you can drop collision once you own the vehicle outright (no active loan), it is generally not recommended for a 2019 model in 2026. A 2019 vehicle still retains significant value (likely $12,000–$20,000 depending on the model). Dropping collision means you would have to pay out of pocket to replace the car if you are at fault in an accident.
Does New Mexico require "No-Fault" insurance?
No. New Mexico is an "at-fault" or "tort" state. This means the person who caused the accident is responsible for the damages. This system is part of why UM/UIM coverage is so important; if an at-fault driver has no insurance, you must rely on your own policy to cover your medical bills and repairs.
Final Recommendation
To secure an annual premium between $1,200 and $1,500 for a 2019 vehicle in New Mexico, drivers should first ensure their credit score is in good standing and then request quotes from at least three different carriers. Prioritize insurers that offer robust Uninsured Motorist coverage, as this is the most critical protection in the New Mexico market. If your quote is on the higher end, consider increasing your deductible to $1,000 or enrolling in a telematics program to demonstrate safe driving habits and lock in a lower rate for the 2026-2027 policy term.