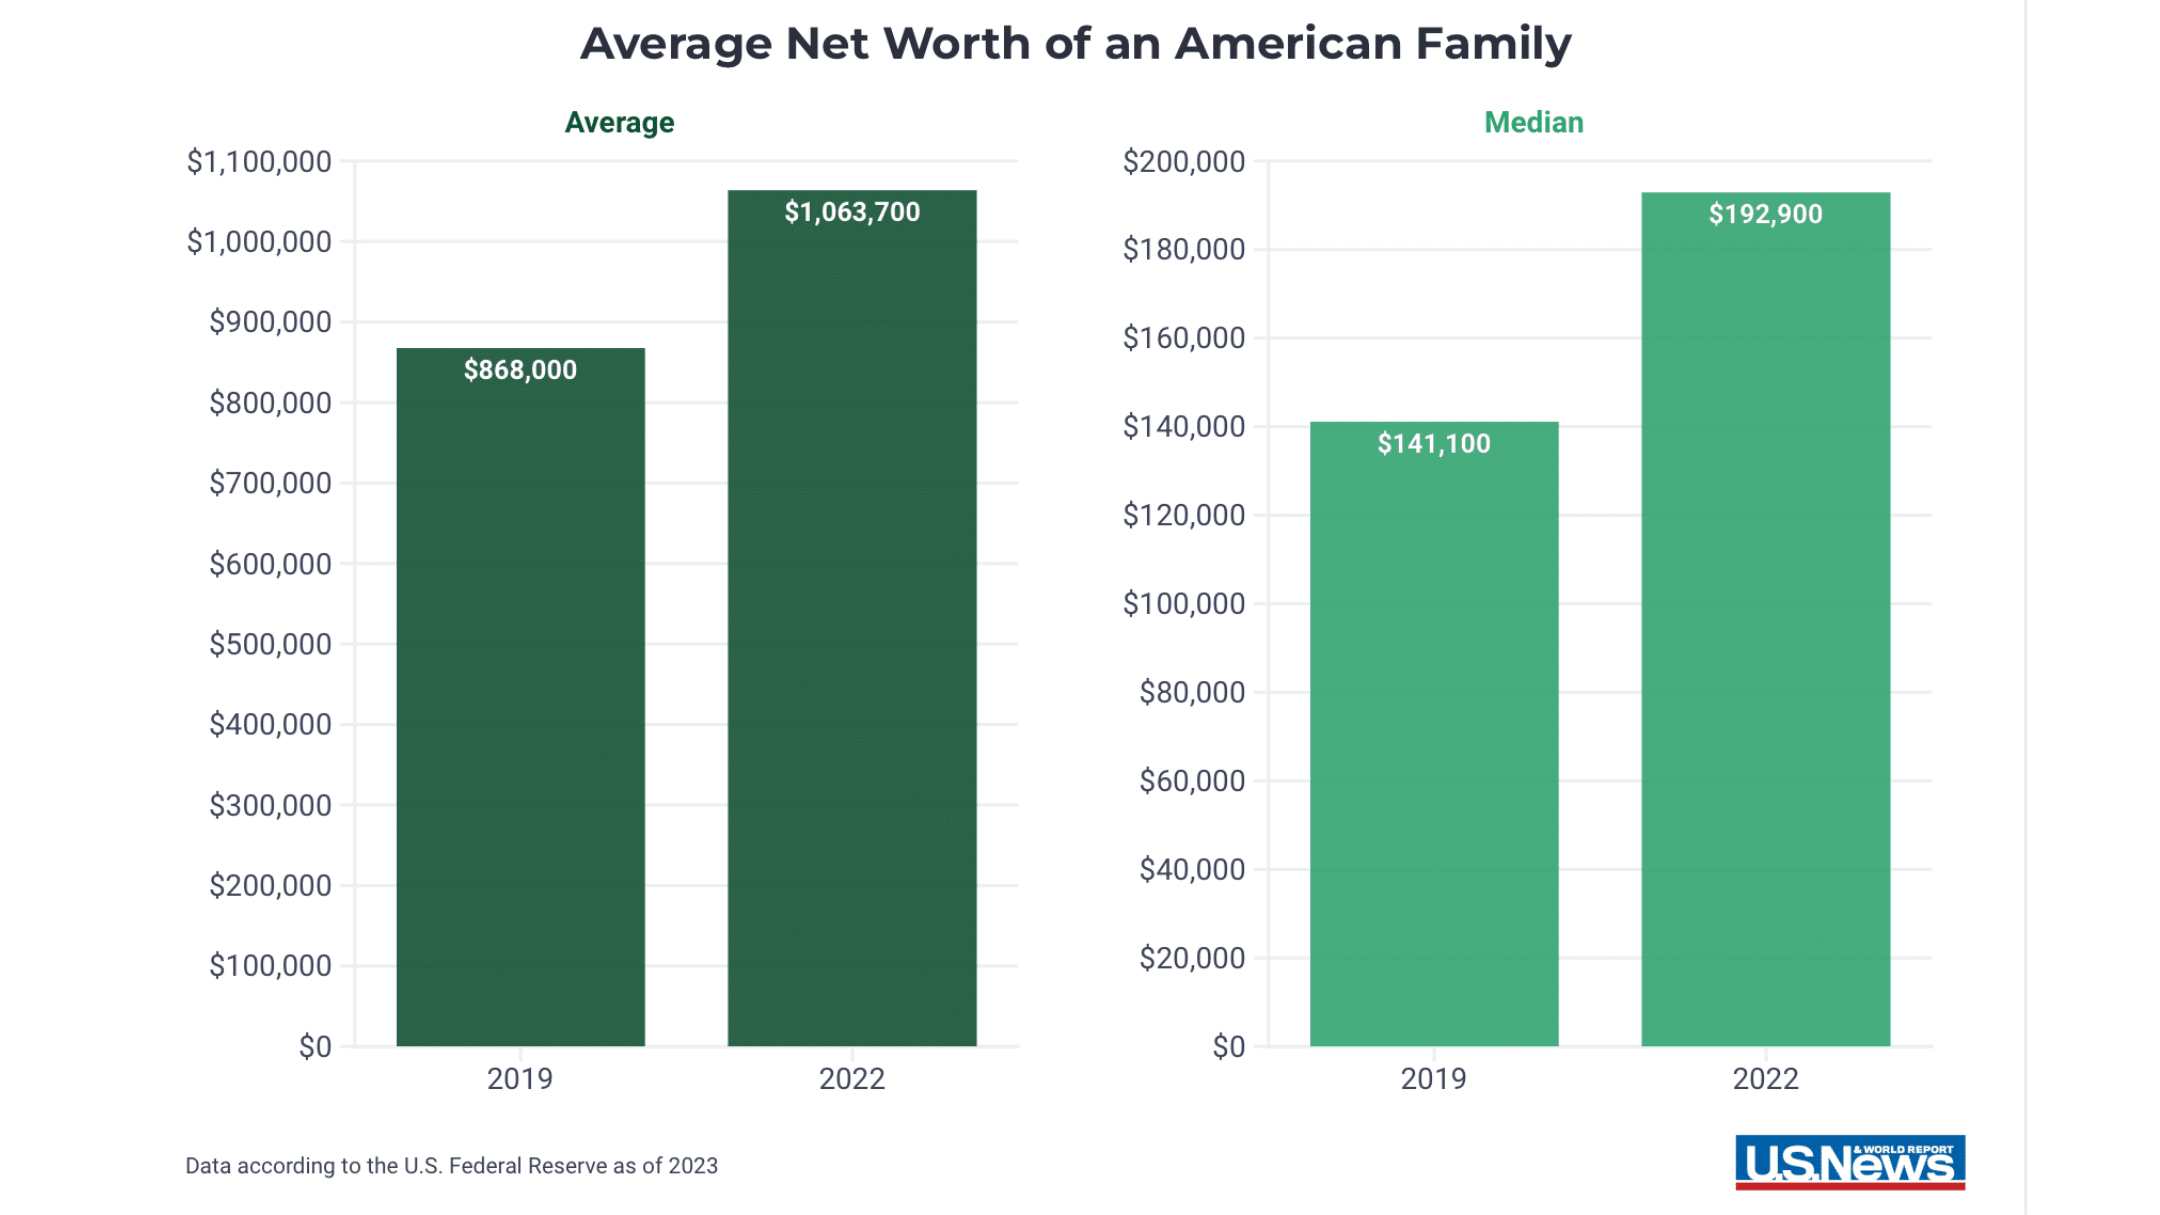
Calculating your net worth accurately requires factoring in your retirement accounts, but you must account for future taxes and potential penalties to avoid overestimating your true financial standing. By subtracting estimated future income taxes from your 401(k) balance, you get a realistic picture of your liquid wealth if you were to liquidate your assets today.
Determining your true financial health is a foundational step in personal finance, long-term wealth planning, and retirement readiness. While calculating net worth might initially seem as simple as adding up the value of your checking accounts, real estate, and investments and subtracting your liabilities, retirement accounts introduce a layer of complexity. Specifically, adding a 401(k) to your net worth requires looking beyond the raw balance displayed on your brokerage dashboard. Because most traditional 401(k) contributions are made with pre-tax dollars, the money sitting in that account is not entirely yours; a portion belongs to the federal and state governments when you eventually make withdrawals.
Understanding how to treat these retirement funds ensures that your financial roadmap remains realistic, stress-free, and aligned with your actual purchasing power. This comprehensive guide explores the mechanics of net worth tracking, the distinction between nominal and real net worth regarding retirement accounts, step-by-step calculation methods, common pitfalls, and strategies to optimize your financial tracking over time.
Understanding Net Worth and the Role of Retirement Accounts
At its core, net worth is a snapshot of your financial position at a single point in time. The formula is straightforward:
$$\text{Net Worth} = \text{Total Assets} - \text{Total Liabilities}$$
Assets include anything of monetary value that you own, ranging from cash and investments to physical property like real estate, vehicles, and valuable collections. Liabilities encompass all outstanding debts, including mortgages, student loans, car loans, credit card balances, and personal loans.
Within the asset category, investments and retirement accounts often make up the largest share for working adults. A 401(k) is an employer-sponsored defined-contribution retirement plan authorized under section 401(k) of the Internal Revenue Code. Because these accounts grow over decades through compounding interest and regular contributions, they frequently become an individual's most valuable asset outside of primary real estate.
However, treating a dollar in a traditional 401(k) the exact same as a dollar sitting in a high-yield savings account or brokerage account introduces an accounting distortion. The cash in a savings account has already been taxed; the money in a traditional 401(k) has not. Consequently, financial planners often distinguish between nominal net worth and real, after-tax net worth.
Traditional vs. Roth 401(k): Why Tax Status Changes the Math
The type of 401(k) you hold dictates how you should approach adding it to your net worth calculation. Tax treatment at the time of withdrawal changes the net realizable value of the asset.
Traditional 401(k) Accounts
Contributions to a traditional 401(k) are made with pre-tax dollars, lowering your taxable income in the year you earn the money. Investment earnings grow tax-deferred. However, every single dollar withdrawn in retirement is taxed as ordinary income at whatever federal and state tax brackets are in effect at that time.
If you have $500,000 in a traditional 401(k), you cannot spend $500,000 today. If you liquidated the entire account today, federal income taxes, state income taxes, and potentially an early withdrawal penalty (if you are under age 59½, as mandated by the Internal Revenue Service) would drastically reduce the final take-home amount.
Roth 401(k) Accounts
Contributions to a Roth 401(k) are made with after-tax dollars. While you do not get an upfront tax break today, your contributions and all investment earnings grow completely tax-free. Furthermore, qualified withdrawals in retirement are 100% tax-free.
If you have $500,000 in a Roth 401(k), that figure represents true, unencumbered value. You can add a Roth 401(k) directly to your net worth statement on a dollar-for-dollar basis without adjusting for future taxes, provided you are past the age where qualified distributions can be made without penalty.
Two Approaches to Adding Your 401(k) to Net Worth
Personal finance practitioners generally debate two distinct methodologies for incorporating a traditional 401(k) into a net worth statement: the Nominal Value Method and the After-Tax Value Method.
| Calculation Method | How It Works | Pros | Cons |
|---|---|---|---|
| Nominal Value Method | Uses the exact balance shown on your current account statement without adjustments. | Simple, fast, aligns with standard financial dashboard software. | Overstates true liquidity; ignores future tax liabilities. |
| After-Tax Value Method | Subtracts an estimated future tax rate from the total balance based on expected retirement brackets. | Highly accurate for long-term planning and estate evaluation. | Requires speculation on future tax laws and personal tax brackets. |
Method 1: The Nominal Value Approach (Most Common)
Most individuals and personal finance tracking applications (such as Empower, Monarch Money, or YNAB) use the nominal value approach.
- The Logic: Net worth is a dynamic tracking metric meant to show your financial trajectory over time. Since you cannot accurately predict tax policy changes 20 or 30 years into the future, using today's raw account balance provides a consistent baseline for tracking growth percentages.
- Implementation: Look at your 401(k) portal balance on the final day of the month and add that exact number to your total assets.
Method 2: The After-Tax Adjustment Approach (Conservative)
Financially conservative individuals or those planning for early retirement (FIRE movement) often prefer discounting their traditional 401(k) balances to reflect future tax obligations.
- The Logic: Pretending you own 100% of a traditional 401(k) is a slight illusion. If your effective tax rate in retirement is projected to be 20%, you effectively own 80% of the account balance.
- Implementation: Take your traditional 401(k) balance and multiply it by $(1 - \text{Estimated Tax Rate})$. For example, if you have $400,000 and expect a blended federal and state tax rate of 20%, you would count $320,000 toward your net worth asset column.
Step-by-Step Guide to Calculating Your Net Worth with a 401(k)
To execute a precise net worth calculation that properly integrates your workplace retirement accounts, follow this structured sequential process.
Step 1: Gather All Asset Balances
Log into all financial institutions where you hold assets.
- Check checking and savings accounts.
- Log into your brokerage accounts for taxable investments.
- Check your current workplace 401(k) portal.
- Locate any legacy traditional or Roth IRAs from previous employers.
- Estimate the current market value of physical assets like real estate or vehicles using conservative comparable sales or valuation tools like Zillow or Kelley Blue Book.
Step 2: Categorize Your 401(k) Funds
Separate your retirement balances by tax classification. If you hold both traditional pre-tax contributions and Roth after-tax contributions within the same employer plan (which many modern 401(k) plans allow via designated Roth accounts), review your account summary to find the sub-account balances for each.
Step 3: Choose Your Valuation Standard
Decide whether you will track your traditional 401(k) at nominal value or apply a standardized tax discount. Consistency is more important than the specific method chosen; pick a standard and stick to it month-over-month or year-over-year so your historical tracking charts remain meaningful.
Step 4: Aggregate All Liabilities
Compile every outstanding debt. Pull statements for:
- Primary mortgage and secondary home equity loans.
- Auto loans and leases.
- Student loans (federal and private).
- Credit card balances (use the full statement balance if you pay in full monthly, or total revolving debt if you carry a balance).
- Personal or business loans guaranteed in your name.
Step 5: Compute the Final Net Worth Figure
Subtract your total liabilities from your total adjusted assets. Keep a dedicated spreadsheet or use an automated financial aggregator to update these figures on a fixed schedule (such as the last day of every month).
Common Mistakes to Avoid When Tracking Net Worth
Miscalculating net worth can lead to poor financial decisions, false confidence during retirement planning, or unnecessary anxiety. Watch out for these common errors:
- Treating Early Withdrawal Penalties as Standard Taxes: If you are calculating net worth for day-to-day tracking, do not subtract the 10% IRS early withdrawal penalty unless you are actively planning to liquidate the account right now to fund an expense. Net worth assumes you are holding the asset until retirement age.
- Ignoring Vesting Schedules: If your employer offers matching contributions, verify whether those matching funds are fully vested. Unvested employer contributions do not legally belong to you yet if you were to quit your job today, and they should be excluded from your net worth calculation.
- Failing to Update Asset Values Regularly: While 401(k) balances fluctuate daily with the stock market, real estate and vehicle values do not. Re-evaluating illiquid assets too frequently or failing to update retirement balances can skew your tracking data.
- Confusing Liquid Net Worth with Total Net Worth: Your 401(k) is an illiquid asset due to tax rules and age restrictions. Do not mistake your total net worth (which includes your 401(k)) for your emergency liquidity or cash-flow availability.
Frequently Asked Questions
Should I include my 401(k) in my net worth if I am far from retirement age?
Yes. Your 401(k) represents a major component of your long-term wealth. Even if you cannot access the funds without penalty today, they represent future purchasing power that accumulates over your working years. Excluding retirement accounts severely understates your true financial progress.
How do I handle employer matching funds that are not yet vested?
You should only include the vested portion of your employer match in your net worth calculation. Check your 401(k) provider's summary plan description to find your vesting schedule. Unvested money is conditional and subject to forfeiture if you leave the company prematurely.
Does changing jobs affect how I calculate my 401(k) in my net worth?
No. Changing jobs does not change the underlying value of the account. If you leave your job, your old 401(k) remains an asset whether you leave it with the previous employer's plan administrator, roll it over into a Traditional IRA, or roll it into your new employer's 401(k) plan.
Is it better to use nominal or after-tax net worth for retirement planning?
For general net worth tracking, the nominal value method is standard because it matches financial dashboard aggregators. However, when performing retirement drawdown simulations or calculating safe withdrawal rates, financial advisors almost always switch to after-tax net worth to account for future tax liabilities accurately.
Next Steps for Financial Tracking
To maintain a clear and accurate financial picture, establish a routine monthly audit of your accounts. Log your assets and liabilities on the same day each month, keeping a separate notation for your pre-tax and post-tax retirement funds if you prefer conservative tracking. By maintaining consistency in how you handle your 401(k) balances, you will cultivate a reliable dataset that accurately reflects your journey toward financial independence.