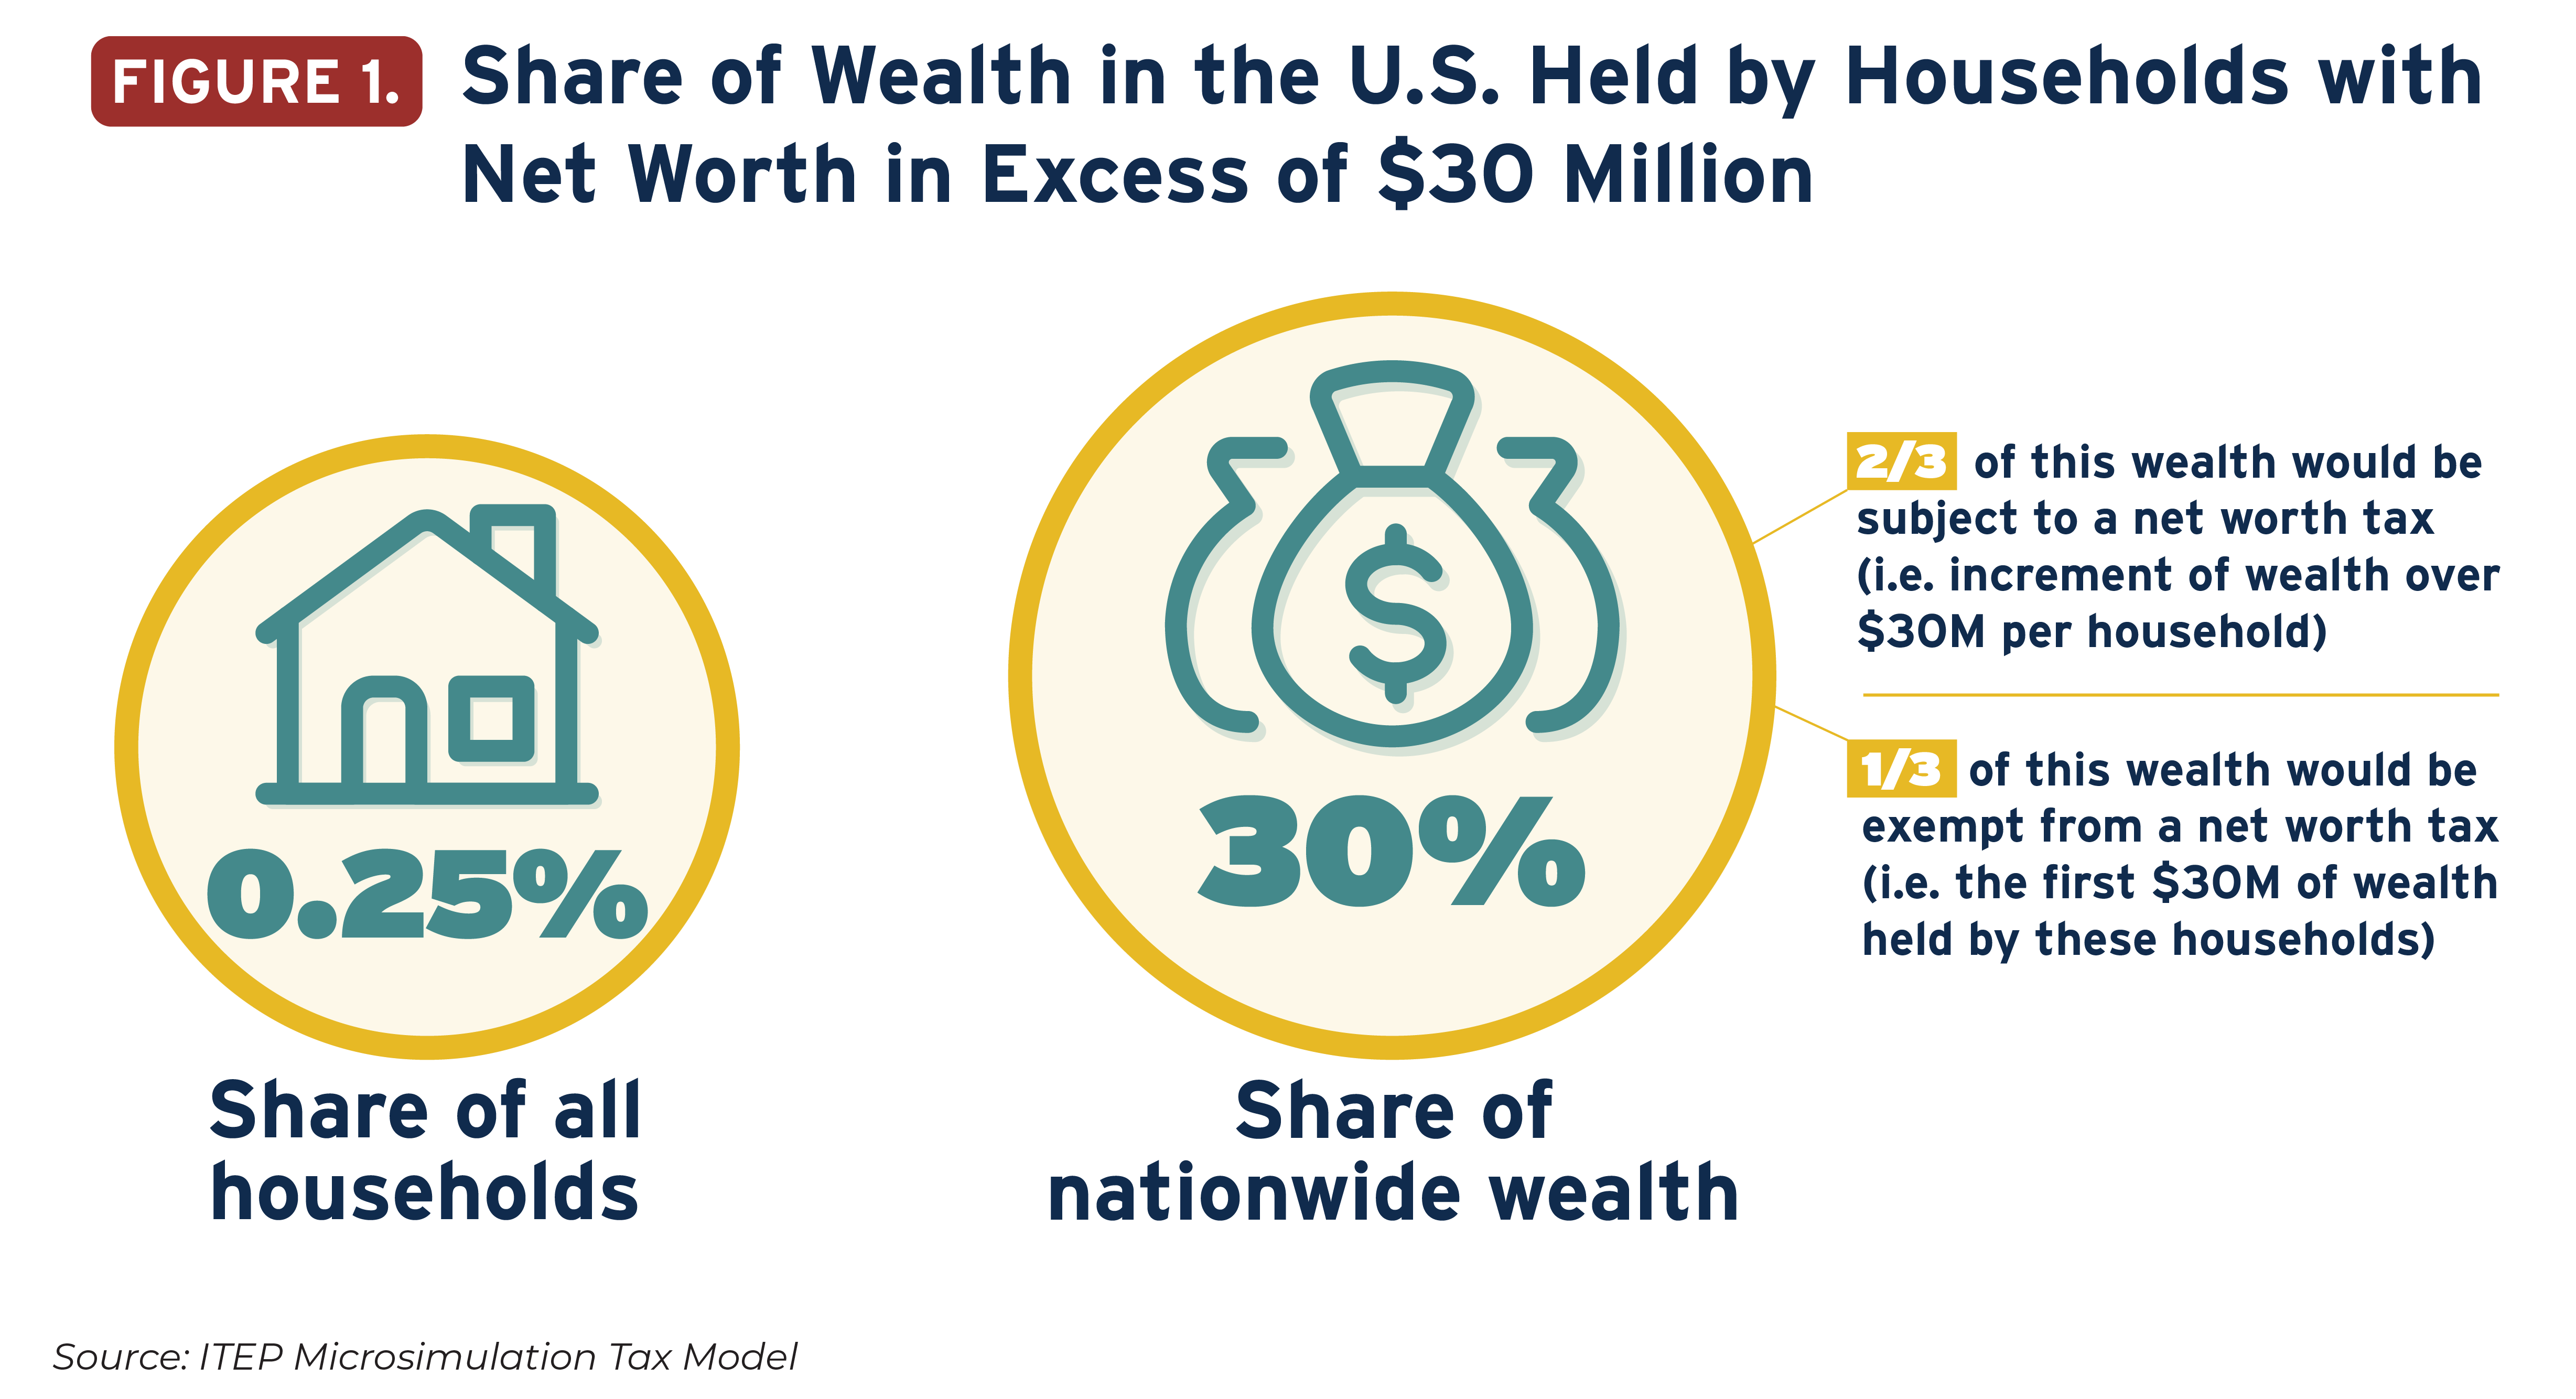
While a $6 million net worth represents extraordinary financial success, it no longer secures a place in the top 1% of American households in 2026. Due to sustained asset inflation and significant gains in equity markets, the current threshold for the top 1% has climbed to approximately $13.7 million, placing $6 million earners in the top 3% to 5% instead.
The Evolution of the Top 1% Threshold
The definition of "wealthy" is frequently moving, driven by economic shifts, currency devaluation, and the concentrated growth of capital assets. As of 2026, the gap between the upper-middle class and the ultra-wealthy has widened significantly. For decades, a net worth of a few million dollars was the quintessential benchmark for the "American Dream." However, when we analyze the most recent data from the Federal Reserve’s Survey of Consumer Finances and adjusted wealth reports from institutions like Knight Frank, the numbers tell a different story.
In the early 2020s, the entry point for the top 1% hovered around $11 million. By 2026, several factors have pushed this number toward the $14 million mark. A household with $6 million is undoubtedly in a position of high financial security, but they are categorized as "High Net Worth Individuals" (HNWIs) rather than the "Ultra High Net Worth" (UHNW) tier that typically populates the top 1%. This distinction is not merely semantic; it reflects a massive disparity in purchasing power, investment access, and tax strategy.
Drivers of Wealth Inflation Between 2020 and 2026
To understand why $6 million has been "relegated" to the top 5% rather than the top 1%, we must look at the specific economic engines that accelerated wealth at the top of the pyramid.
Equity Market Concentration
Over the last five years, the stock market has seen unprecedented growth in specific sectors, particularly technology, artificial intelligence, and energy. Because the top 1% of households own more than 50% of all individually held equities, they have captured the lion's share of this growth. While a $6 million portfolio is substantial, it does not compound with the same velocity as a $50 million or $100 million portfolio managed by family offices with access to private equity, venture capital, and exclusive hedge funds.
Real Estate Appreciation in Tier-1 Cities
In the primary markets—New York, San Francisco, Miami, and Los Angeles—real estate prices have decoupled from local income levels. A primary residence in these areas can easily consume $3 million to $5 million of a $6 million net worth. When a significant portion of wealth is locked in personal real estate, the liquid capital available for reinvestment is limited. In contrast, those in the top 1% often hold diversified real estate portfolios across multiple jurisdictions, allowing them to benefit from both rental income and capital appreciation without compromising liquidity.
Business Valuations
Small to mid-sized business owners represent a large portion of the "multi-millionaire" class. However, the 2026 economy favors scale. Large-scale enterprises have seen their valuations soar, while smaller operations face higher borrowing costs and labor challenges. This has created a "barbell" effect where the owners of the largest companies have entered the top 1%, while successful local business owners with a $6 million valuation find themselves in the broader affluent class.
Quantifying the Wealth Gap: 2026 Percentiles
To provide context on where a $6 million net worth sits relative to the rest of the population, we must examine the distribution of wealth across various percentiles. The following table reflects estimated net worth requirements for U.S. households in 2026.
| Percentile | Minimum Net Worth Requirement (Estimated 2026) | Classification |
|---|---|---|
| Top 0.1% | $62,000,000+ | Ultra-High Net Worth (UHNW) |
| Top 1% | $13,700,000 | The Elite Wealth Class |
| Top 2% | $9,200,000 | Upper Tier HNWI |
| Top 5% | $5,800,000 | High Net Worth Individual (HNWI) |
| Top 10% | $2,600,000 | Mass Affluent |
| Median (50%) | $210,000 | Middle Class |
As the data indicates, $6 million places a household firmly within the top 5%. While this is an elite position globally and nationally, the jump from $6 million to the $13.7 million required for the 1% is a significant hurdle that usually requires either a high-level corporate exit, an inheritance, or an exceptionally high-income professional career (such as specialized medicine or senior law partnership).
Geographic Disparity: Where the 1% Threshold Varies
A critical factor in the "Top 1%" discussion is geography. The cost of living and the local concentration of wealth drastically alter what $6 million can buy and where it ranks you.
High-Cost-of-Living (HCOL) Areas
In cities like Aspen, Manhattan, or Atherton, $6 million may not even purchase a flagship property in the most desirable neighborhoods. In these micro-markets, the top 1% threshold can exceed $25 million. A person with $6 million in Palo Alto might feel "middle class" relative to their neighbors, as their net worth is largely tied up in a modest three-bedroom home and a 401(k).
Low-Cost-of-Living (LCOL) Areas
Conversely, in states like West Virginia, Mississippi, or parts of the Midwest, a $6 million net worth provides a lifestyle that is indistinguishable from the top 1%. In these regions, the local threshold for the top 1% may drop as low as $5 million or $6 million. Therefore, while $6 million does not reach the national 1% mark, it frequently exceeds the local 1% mark in many parts of the country.
The Psychology of the "Mass Affluent" vs. the "1%"
There is a distinct psychological and lifestyle difference between having $6 million and $14 million. This difference often centers on "Lifestyle Creep" and "Financial Independence."
- Work Requirements: Many individuals with a $6 million net worth still feel the need to work, particularly if they are in their 40s or 50s. They must protect their principal to ensure it lasts through a 30-year retirement while accounting for 2026 inflation rates.
- Spending Power: The top 1% (at $13.7M+) can typically sustain an annual spend of $400,000 to $500,000 indefinitely using a safe withdrawal rate. A person with $6 million is generally limited to a $200,000 to $240,000 annual budget if they wish to preserve their capital.
- Tax Sensitivity: Those at the $6 million level are often heavily impacted by ordinary income taxes and standard capital gains. The top 1% often utilize more complex legal structures, such as Family Limited Partnerships (FLPs) or charitable lead trusts, to mitigate the impact of the 2026 tax environment.
The Role of Debt and Liquidity
Net worth is a "paper" calculation: total assets minus total liabilities. In 2026, the composition of that $6 million matters more than the number itself.
A household with $8 million in assets and $2 million in mortgage/business debt has a $6 million net worth. If those assets are primarily illiquid (like a private business or a primary residence), the household may feel "cash poor."
In contrast, the top 1% typically maintains a higher "Liquid Net Worth." They hold substantial positions in cash equivalents, brokerage accounts, and government bonds. This liquidity allows them to pounce on investment opportunities during market downturns, a luxury that the $6 million household—often fully invested or "house-rich"—may not have.
Common Misconceptions About Wealth Percentiles
Many people confuse income with net worth. Being in the top 1% of earners (annual income) is different from being in the top 1% of wealth holders (accumulated net worth).
- Income vs. Wealth: In 2026, a household might earn $800,000 a year, which puts them in the top 1% of earners. However, if they have high expenses and only $2 million in the bank, they are nowhere near the top 1% of wealth.
- The "Millionaire Next Door" Effect: Because of the rise in home values, many people have become "accidental millionaires." In 2026, having $1 million is increasingly viewed as the baseline for a secure retirement, not a sign of opulence. This shift is what has pushed the 1% threshold into the double-digit millions.
Strategies for Moving from $6 Million to the Top 1%
For those currently at the $6 million mark who aspire to reach the top 1% ($13.7M+), the strategy must shift from accumulation to multiplication.
- Tax Efficiency: At this level, tax drag is the biggest enemy. Utilizing tax-loss harvesting, municipal bonds, and health savings accounts (HSAs) is no longer enough. One must look at sophisticated estate planning to avoid the sun-setting provisions of previous tax cuts.
- Alternative Investments: Moving beyond the S&P 500 into private credit, real estate syndications, and early-stage venture capital can provide the "alpha" needed to double a net worth over a 7-to-10-year horizon.
- Asset Protection: As net worth grows, the risk of litigation increases. Establishing umbrella insurance policies and asset protection trusts is a hallmark of the 1% that those at the $6 million level often overlook.
Frequently Asked Questions
Is $6 million considered "rich" in 2026?
Yes, $6 million is considered "High Net Worth" and places a household in the top 5% of the U.S. population. It allows for a high standard of living, financial independence, and the ability to retire comfortably in most parts of the country. However, it does not provide the "unlimited" lifestyle associated with the ultra-wealthy or the top 1%.
Why has the 1% threshold increased so much recently?
The threshold has increased due to several factors: the massive expansion of the money supply in the early 2020s, the outsized performance of the stock market (particularly mega-cap tech stocks), and a significant rise in residential and commercial property values. Wealth has become more concentrated at the top because those with existing assets saw those assets appreciate faster than wages grew for the rest of the population.
How much do I need to be in the top 1% globally?
The global 1% threshold is significantly lower than the U.S. threshold. In 2026, a net worth of approximately $1.5 million to $2 million is often enough to put an individual in the top 1% of the global population, as wealth is highly concentrated in Western nations and parts of Asia.
Does the top 1% include the value of a primary residence?
Yes, standard calculations of net worth (including those by the Federal Reserve) include all assets, including the equity in a primary residence. However, many financial planners prefer to look at "Investable Assets" (excluding the home) to determine true financial flexibility.
What is the average age of someone in the top 1%?
The average age typically falls between 55 and 65. Wealth accumulation is a cumulative process, and it takes decades of saving, investing, and compound interest to reach the $13.7 million threshold. It is rare for individuals under 40 to reach this level without a significant business exit or inheritance.
Practical Recommendation
If you have achieved a $6 million net worth, your primary focus should be on asset preservation and inflation protection. While you are not in the top 1%, you have achieved a level of "Financial Peace" that 95% of the population will never reach. To bridge the gap to the 1%, focus on diversifying into cash-flowing assets that outpace inflation and consulting with a specialized wealth manager to optimize your tax strategy for the 2026 fiscal environment. Do not let the "moving goalposts" of the 1% diminish the reality of your financial success; instead, use your current capital to build a legacy that is resilient to market volatility.