AARP life insurance is generally considered a high-quality option for seniors who prioritize convenience and brand stability over the lowest possible price. While AARP itself is not an insurance company, its policies—underwritten by the highly-rated New York Life—offer simplified enrollment without medical exams, making them accessible to members with moderate health issues.
Determining whether AARP is a "good" life insurance company requires looking beyond the famous name to the actual underwriter, the specific policy terms, and how the costs compare to the broader 2026 insurance market. AARP life insurance products are designed specifically for the needs of individuals aged 50 to 80, focusing on ease of access rather than high-limit coverage.
Understanding the AARP and New York Life Partnership
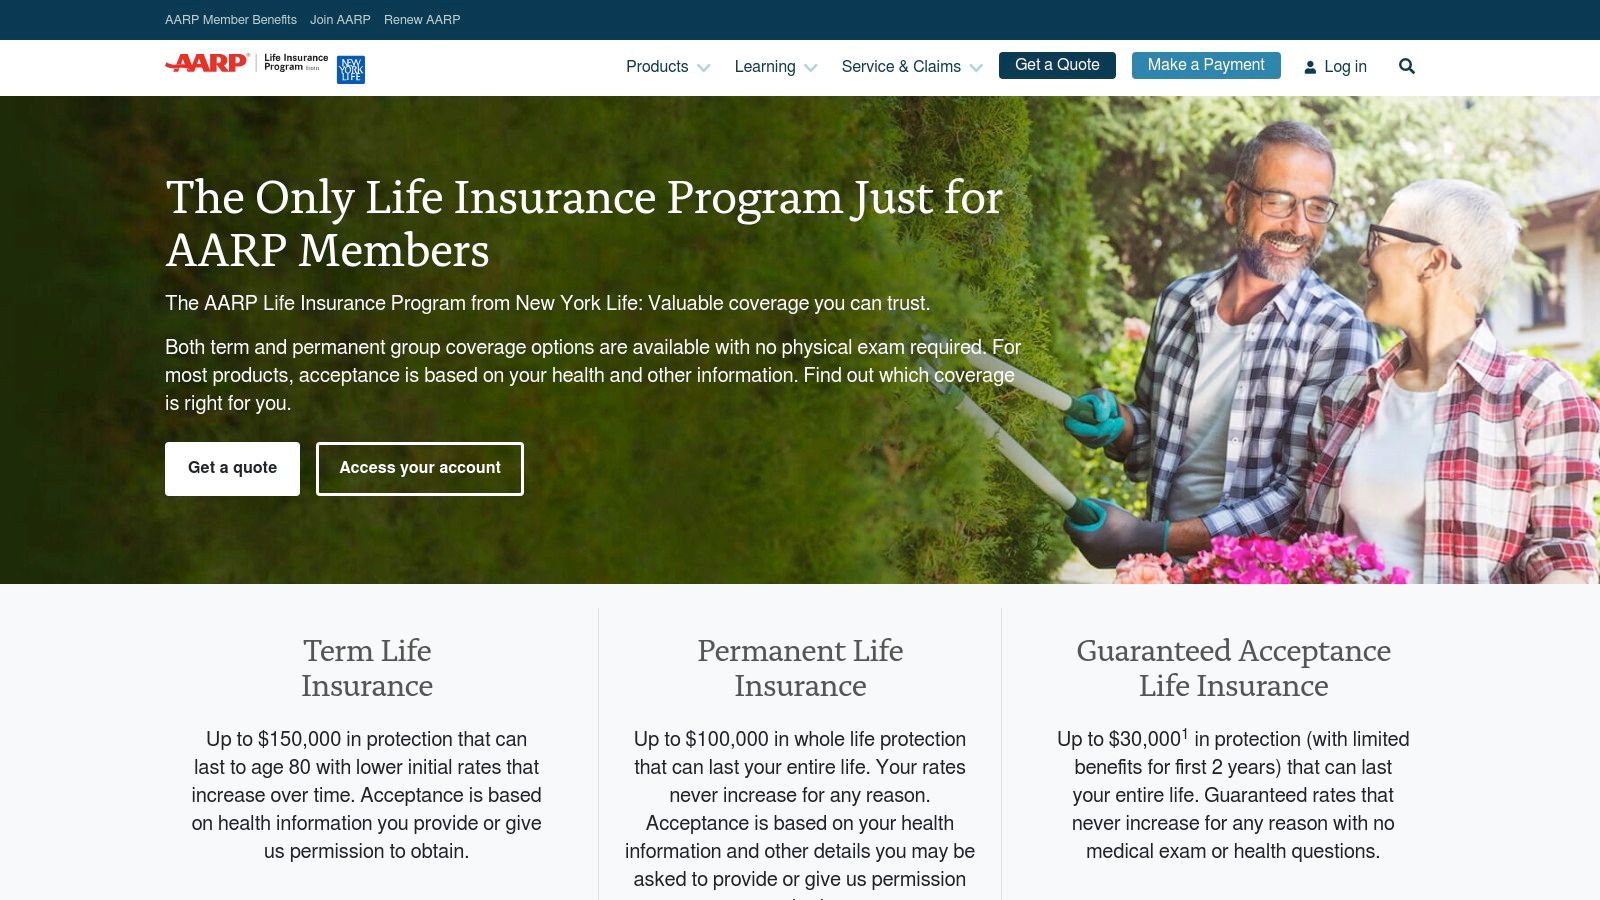
A common misconception is that AARP (formerly the American Association of Retired Persons) is the insurance carrier. In reality, AARP acts as a massive group policyholder and marketing partner. The actual insurance policies are issued and managed by New York Life Insurance Company.
As of 2026, New York Life remains one of the oldest and most financially stable mutual life insurance companies in the United States. This partnership is a significant factor in why many consider AARP life insurance to be a "good" choice. When you purchase an AARP policy, you are backed by a company that consistently receives the highest possible financial strength ratings from major agencies like A.M. Best (A++), Fitch (AAA), and Moody’s (Aaa).
This financial stability is crucial in life insurance. It provides policyholders with the assurance that the company will have the liquidity to pay out death benefits decades into the future. For seniors looking for a reliable "final expense" solution, the institutional strength of New York Life is a major selling point that mitigates the risk of company insolvency or unpaid claims.
Types of Life Insurance Policies Offered by AARP
To evaluate if AARP is the right fit, one must understand the three primary products they offer to members. Each serves a different financial goal and caters to different health profiles.
AARP Term Life Insurance
The AARP Term Life Insurance program is designed for members who need coverage for a specific period, such as until a mortgage is paid off or until children are financially independent. Unlike many commercial term policies that require a physical exam, AARP's version typically uses simplified underwriting. This means applicants answer a few health questions rather than undergoing blood draws or medical tests.
However, there is a specific structure to AARP’s term premiums that applicants must understand. These premiums are not level for the entire duration of the policy. Instead, they are set in five-year age bands. As you move from one age bracket to the next (e.g., from 64 to 65), your monthly premium will increase. The coverage generally ends when the policyholder reaches age 80.
AARP Permanent Life Insurance (Whole Life)
AARP’s Permanent Life Insurance is a whole life product intended to provide coverage for the remainder of the insured’s life. Unlike the term policy, the premiums for this plan are guaranteed to stay the same for as long as you keep the policy.
This policy also builds cash value over time. This is a small portion of your premium that grows on a tax-deferred basis and can be borrowed against if you need funds during your lifetime. Because it is a permanent policy, the death benefit is guaranteed to be paid to your beneficiaries as long as premiums are up to date. This is the preferred choice for those looking to cover funeral costs or leave a modest legacy.
AARP Guaranteed Acceptance Life Insurance
For seniors with significant health challenges who cannot qualify for term or whole life coverage, AARP offers a Guaranteed Acceptance plan. As the name implies, you cannot be turned down for this coverage due to health reasons, provided you are within the eligible age range. No health questions are asked.
The trade-off for this guaranteed entry is a graded death benefit. If the insured dies of natural causes within the first two years of the policy, the beneficiaries will not receive the full face value. Instead, they typically receive the premiums paid plus a small percentage of interest (often 10%). After the initial two-year period, the full death benefit is active. This structure protects the insurance company from individuals who are terminally ill when they apply.
The Pros and Cons of AARP Life Insurance
Evaluating AARP requires a balanced look at where the company excels and where it falls short compared to independent insurance brokers or other senior-focused brands.
Advantages
- Ease of Application: The removal of the medical exam is a massive benefit for seniors who have minor health issues that might complicate a traditional underwriting process.
- Brand Trust: Dealing with a household name and a top-tier underwriter (New York Life) reduces the anxiety associated with smaller, less-established carriers.
- Living Benefits: Many AARP policies include an "accelerated death benefit" rider at no extra cost. This allows you to access a portion of the death benefit if you are diagnosed with a terminal illness, helping to cover end-of-life medical costs.
- No Waiting Period (Mostly): Unlike many final expense plans, the AARP Term and Permanent (non-guaranteed) plans offer full coverage from day one.
Disadvantages
- Pricing for the Healthy: If you are in excellent health, you will almost certainly find lower premiums by going through a fully underwritten process with a different carrier. AARP's "one-size-fits-most" pricing tends to overcharge the healthy to account for the risk of the less healthy.
- Low Coverage Limits: AARP policies generally cap out at $100,000 for term and $50,000 for permanent life. If you need a $500,000 policy to replace income or protect a large estate, AARP is not the right provider.
- Increasing Term Costs: The five-year price jumps in the term policy can make it prohibitively expensive as you reach your 70s.
- Membership Required: You must pay the annual AARP membership fee to be eligible for these insurance products.
Eligibility Requirements and Membership Benefits
To apply for AARP Life Insurance in 2026, the primary requirement is active AARP membership. Membership is available to anyone aged 50 and over. However, spouses of members can often apply for coverage starting as young as age 45.
The age limits for new applications are strictly defined:
- Term Life: Available for members aged 50 through 74.
- Permanent Life: Available for members aged 50 through 80.
- Guaranteed Acceptance: Available for members aged 50 through 80 (with slightly different limits in New York).
One benefit of the AARP program is that once you are accepted, your coverage cannot be canceled as long as you pay your premiums. Even if you decide to cancel your AARP membership later, New York Life generally allows you to maintain the life insurance policy, though you should verify the specific terms of your contract as policies can evolve.
Cost Analysis: AARP vs. The Market
In 2026, the cost of life insurance is highly competitive. AARP's rates are often described as "middle-of-the-road." They are rarely the cheapest, but they are also far from the most expensive, especially when compared to other "no-exam" mail-order policies.
| Feature | AARP Term Life | AARP Whole Life | AARP Guaranteed Acceptance |
|---|---|---|---|
| Max Coverage | Up to $100,000 | Up to $50,000 | Up to $25,000 |
| Medical Exam | No | No | No |
| Health Questions | Yes (Simplified) | Yes (Simplified) | No |
| Premium Structure | Increases every 5 years | Fixed for life | Fixed for life |
| Cash Value | No | Yes | No |
| Full Benefit | Day one | Day one | After 2 years |
Note: Coverage limits and availability may vary by state. Always refer to the specific New York Life disclosures for your jurisdiction.
Comparing AARP with Other Senior Providers
When deciding if AARP is "good," it is helpful to compare it to competitors like Mutual of Omaha, Globe Life, and Colonial Penn.
Mutual of Omaha often competes directly with AARP on whole life and final expense insurance. Their pricing is frequently lower than AARP's for those who can pass a few more health questions. However, AARP’s application process is often perceived as more user-friendly.
Globe Life is famous for its "$1 for the first month" offer. While this sounds appealing, Globe Life's premiums, like AARP's term plan, increase every five years based on your age. For long-term permanent coverage, AARP’s whole life plan often provides better long-term value because the rate is locked in.
Colonial Penn is the primary competitor for the Guaranteed Acceptance market. They use a "unit" system where the price stays the same ($9.95 per unit), but the amount of coverage you get per unit decreases as you get older. AARP’s guaranteed plan is often more transparent, allowing you to choose a specific dollar amount of coverage rather than calculating "units."
The Claims Process and Customer Service Reputation
A life insurance policy is only as good as its claims department. Because the AARP program is managed by New York Life, the claims process is generally streamlined and professional.
Beneficiaries can initiate a claim online or via a dedicated AARP-New York Life service line. Documentation requirements typically include a certified copy of the death certificate and a completed claim form. Because many of these policies are simplified-issue, New York Life has a vested interest in maintaining a quick turnaround to uphold their reputation within the AARP community.
Customer service ratings for the AARP life insurance program are generally positive, though common complaints often center around the rate increases in the term product. Many seniors do not fully realize that their term rates will jump every five years, leading to "sticker shock" later in life. This is why it is essential to read the premium schedule provided at the time of application.
Frequently Asked Questions
Does AARP life insurance require a physical exam?
No. All current AARP life insurance products underwritten by New York Life are "no-medical-exam" policies. You will either answer a few health questions (Simplified Issue) or no health questions at all (Guaranteed Acceptance).
Can I keep my AARP life insurance after age 80?
If you have a Permanent (Whole Life) or Guaranteed Acceptance policy, your coverage continues for as long as you live, provided premiums are paid. If you have the Term Life policy, the coverage typically expires once you reach age 80, regardless of how long you have paid into it.
Is the AARP life insurance payout taxable?
Generally, no. In the United States, life insurance death benefits are typically paid to beneficiaries free of federal income tax. However, if the payout is part of a very large estate, it could potentially be subject to estate taxes, and interest earned on the payout is taxable. You should consult a tax professional for specific 2026 tax guidance.
What happens if I miss a premium payment?
Most AARP policies have a 31-day grace period. If you pay the premium within this window, your coverage remains intact. For whole life policies with sufficient cash value, the "automatic premium loan" feature might use the cash value to pay the premium to prevent the policy from lapsing.
Is AARP life insurance better than what I can get at work?
Usually, no. Group life insurance through an employer is often subsidized and very inexpensive. However, work-based insurance usually ends when you retire. AARP is a "good" option for those who are retired or want a policy they can take with them regardless of employment status.
Final Verdict and Next Steps
Is AARP a good life insurance company? Yes, it is a reputable and secure choice, particularly for seniors who want a fast, no-hassle application process and the peace of mind that comes with a New York Life policy. It is an excellent fit for covering final expenses, small debts, or providing a modest cushion for a spouse.
However, it is not the best choice for everyone. If you are in excellent health and need a significant amount of coverage (over $100,000), you should look into a fully underwritten term policy from an independent broker. Likewise, if you are looking for the absolute lowest price for a small final expense policy, shopping around and comparing AARP's rates with Mutual of Omaha or State Farm is a wise financial move.
Next Steps for Readers:
- Assess Your Needs: Calculate your funeral costs and any remaining debts. If they total under $50,000, AARP Whole Life is a strong candidate.
- Verify Your Health: If you have no major health issues, ask an independent agent for a "fully underwritten" quote to compare against AARP's simplified rates.
- Check the Term Schedule: If considering the term plan, request the full schedule of premium increases so you can see what the policy will cost you when you are 70 or 75.
- Review Beneficiaries: Ensure your AARP membership and contact information are current to make the application process seamless.
Note: This article provides general information and does not constitute financial or legal advice. Insurance regulations and policy terms can vary by state and individual circumstances.