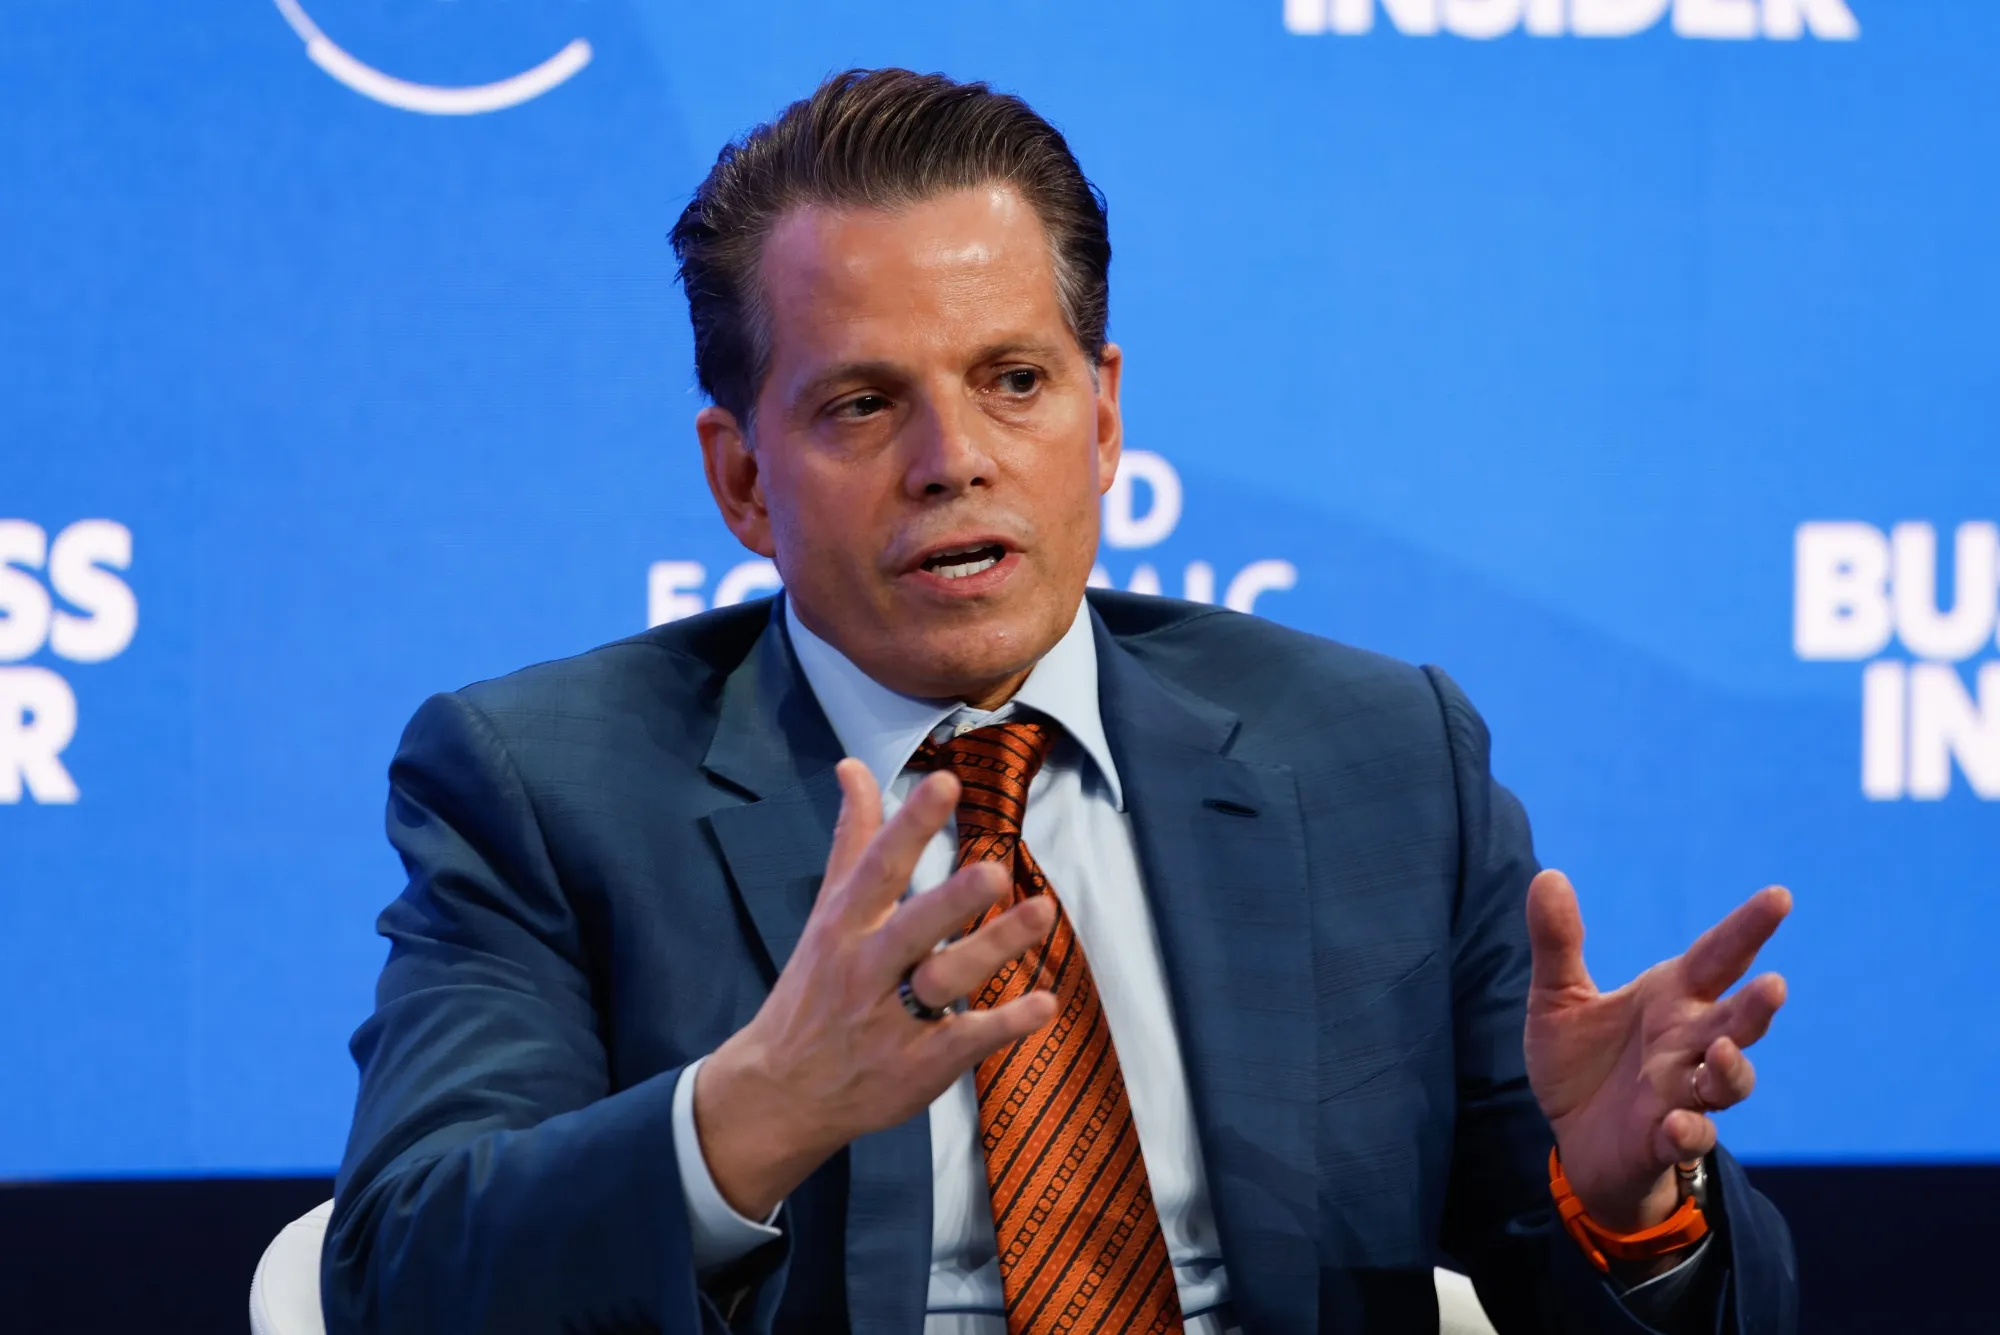
Estimating Anthony Casa’s net worth in 2024 requires a detailed analysis of his primary asset, UMORTGAGE, and his historical influence within the wholesale mortgage sector. While private equity figures are not public, industry benchmarks and company growth suggest a net worth ranging between $15 million and $30 million in 2024, tied largely to enterprise value.
Understanding the Financial Profile of Anthony Casa
Anthony Casa is a prominent, and often polarizing, figure in the American mortgage industry. His financial standing is not merely a reflection of a personal bank balance but is inextricably linked to the shifts in the mortgage "broker vs. retail" landscape. Unlike corporate executives with transparent salary disclosures, Casa’s wealth is built on the foundation of entrepreneurship, platform scaling, and industry advocacy.
By 2024, the mortgage industry had undergone a significant transformation. Following the pandemic-era refi-boom and the subsequent interest rate hikes of 2022 and 2023, the survivors in the space were those who could pivot to purchase-money transactions. Casa’s primary vehicle for wealth during this period was UMORTGAGE, a platform designed to provide independent brokers with the infrastructure of a large company while maintaining the autonomy of the wholesale channel.
To understand his net worth, one must look at the valuation of mortgage companies during a "higher-for-longer" interest rate environment. In 2024, mortgage originators were valued less on pure volume and more on their ability to maintain margins and recruit high-producing loan officers. Casa’s role as a recruiter and visionary for the broker channel has been his most significant "intangible asset," driving the tangible value of his corporate holdings.
The Evolution of UMORTGAGE and Its Impact on Valuation
The centerpiece of Anthony Casa’s financial portfolio in 2024 is UMORTGAGE. Founded with the intent to disrupt the traditional retail mortgage model, UMORTGAGE operates as a national mortgage platform. Its valuation is the primary driver of Casa's net worth.
The Platform Model vs. Traditional Brokerages
Unlike a standard "mom-and-pop" mortgage shop, UMORTGAGE was built to scale. In the financial world, companies that offer a "platform" for others to do business are typically valued at higher multiples than those that simply provide a service. By 2024, UMORTGAGE had successfully recruited hundreds of loan officers across the United States.
The revenue model for such a firm is based on taking a small percentage of every loan closed (basis points) in exchange for providing technology, compliance, branding, and lead generation. As the company’s total loan volume increased toward 2024, the enterprise value—the price the company would fetch if sold—rose significantly.
Market Conditions and Equity Value
In 2024, the mortgage market was challenging. However, firms that focused on the "wholesale" side, like UMORTGAGE, often saw better growth prospects because they could offer consumers lower rates than traditional retail banks. Casa’s equity in this private firm represents the lion's share of his wealth. Financial analysts typically value healthy, growing mortgage firms at 3x to 5x their annual EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization). If UMORTGAGE was generating millions in annual profit by 2024, the company’s paper value would easily sit in the tens of millions.
Historical Career Context: From AIME to Entrepreneurship
The trajectory of Anthony Casa’s net worth cannot be understood without looking back at his role in the Association of Independent Mortgage Experts (AIME). Although Casa stepped down from his leadership role at AIME in 2020 following a highly publicized legal and social controversy, his work there laid the groundwork for his 2024 financial status.
The BRAWL Movement
Casa was a founding force behind the "Brokers Rallying Against Whole-tail Lending" (BRAWL) movement. This movement was instrumental in shifting market share from large retail lenders like Quicken Loans (now Rocket Mortgage) to wholesale lenders like United Wholesale Mortgage (UWM). By championing the broker channel, Casa positioned himself as a thought leader. This reputation allowed him to pivot into UMORTGAGE with an immediate following of loyal loan officers and industry partners.
Personal Rebranding and Financial Recovery
The period between 2020 and 2022 was a transitional phase. While legal settlements and the loss of a formal role at AIME might have been a financial setback, the subsequent founding and rapid scaling of UMORTGAGE allowed for a significant financial rebound. By 2024, the "brand" of Anthony Casa had shifted from industry activist to high-growth CEO, which is a far more lucrative position for long-term wealth accumulation.
Estimating the Components of Net Worth in 2024
Net worth is the sum of all assets minus liabilities. For a private entrepreneur like Casa, we categorize his wealth into four main buckets:
- Corporate Equity (UMORTGAGE): This is the largest component. Given the recruitment numbers and estimated loan volumes reported by the company in late 2023 and early 2024, this asset likely accounts for 70-80% of his total net worth.
- Real Estate Holdings: Like many high-net-worth individuals in the mortgage space, Casa has historically invested in residential and potentially commercial real estate. These assets provide a hedge against the volatility of the mortgage market.
- Advisory and Speaking Fees: While perhaps minor compared to his business equity, Casa remains a sought-after speaker at industry events. These engagements, along with any consulting work for tech vendors in the mortgage space, provide liquid cash flow.
- Liquid Assets: Cash and diversified stock market investments.
The Challenge of Liquidity
It is important to note that a significant portion of a $20M+ net worth in this context is "on paper." Until an "exit event"—such as an Initial Public Offering (IPO), a merger, or a buyout by a private equity firm—the value of UMORTGAGE remains illiquid. In 2024, with the M&A (Mergers and Acquisitions) market for mortgage companies being somewhat cool due to interest rate uncertainty, the emphasis for Casa was likely on internal growth rather than a quick sale.
The Mortgage Industry Landscape in 2024
To explain why Casa's net worth is a point of interest, one must understand the economic environment of 2024. The housing market was characterized by low inventory and high mortgage rates compared to the previous decade.
In this environment, "Retail" mortgage companies with high overhead costs (physical branches, large middle-management layers) struggled. Conversely, "Wholesale" models like the one Casa promotes were better positioned to capture the limited number of buyers by offering more competitive pricing. This structural shift in the industry directly benefited Casa’s financial trajectory.
| Feature | Retail Mortgage Model | Wholesale/Broker Model (UMORTGAGE Style) |
|---|---|---|
| Overhead | High (Branches/Staff) | Low (Tech-centric/Lean) |
| Consumer Rates | Generally Higher | Often Lower/More Options |
| Scalability | Slow (Physical expansion) | Fast (Digital/Recruitment-led) |
| Valuation Multiple | Lower (Asset heavy) | Higher (Platform/Tech-enabled) |
| Control | Centralized | Decentralized/Broker-centric |
The table above illustrates why the model Casa chose for UMORTGAGE is designed for wealth creation. By choosing a low-overhead, high-scalability model, he maximized the potential "EBITDA" of his primary asset.
Financial Risks and Future Outlook
No net worth analysis is complete without considering the risks. In 2024, Anthony Casa faced several industry-wide risks that could impact his valuation:
- Interest Rate Volatility: If rates stayed high for an extended period, the overall volume of the mortgage industry would remain suppressed, limiting the growth of UMORTGAGE.
- Regulatory Changes: The Consumer Financial Protection Bureau (CFPB) frequently updates rules regarding how mortgage brokers are compensated. Any drastic change in "LO Comp" (Loan Officer Compensation) rules could alter the profitability of his business model.
- Competition: As more companies try to replicate the "platform" model, the cost of recruiting top talent increases, potentially squeezing margins.
Despite these risks, Casa’s aggressive focus on the "purchase" market—helping buyers find new homes rather than just helping existing homeowners refinance—provided a stable floor for his company's revenue in 2024.
Expert Analysis: The "Casa Factor" in Valuation
In the mortgage world, some leaders possess a "Key Person" value. Anthony Casa is widely considered a "Key Person" for UMORTGAGE. His ability to use social media, podcasts, and public appearances to recruit loan officers is a specific skill set that adds a premium to his company's valuation.
If we look at his net worth through the lens of a senior SEO and financial editor, we see a profile built on personal branding. In 2024, the intersection of influence and finance is where the most significant wealth is created. Casa didn't just build a mortgage company; he built a brand that attracts the "tools" (loan officers) necessary to generate revenue. This "Recruitment as a Service" (RaaS) element is what likely pushed his net worth into the upper echelons of industry earners by 2024.
Frequently Asked Questions
What is Anthony Casa’s primary source of wealth?
His primary source of wealth is his ownership stake in UMORTGAGE, a national mortgage platform. He generates income through the company’s profits and the growing enterprise value of the firm, which scales based on the number of loan officers and total loan volume processed through the platform.
Was Anthony Casa’s net worth affected by his exit from AIME?
While his departure from AIME in 2020 was a professional pivot, it did not necessarily result in a long-term financial decline. Instead, it allowed him to focus entirely on the private sector and the development of UMORTGAGE, which has a much higher ceiling for personal wealth creation than a non-profit leadership role.
How does UMORTGAGE make money?
UMORTGAGE operates on a basis point (bps) model. They provide the licensing, technology, and backend support for mortgage brokers. In exchange, the company retains a portion of the commission from every loan closed. This recurring revenue stream, scaled across hundreds of employees, creates significant corporate value.
Is Anthony Casa a billionaire?
No. While he is highly successful within the mortgage industry, his net worth is estimated to be in the multi-million dollar range (approx. $15M–$30M). Achieving billionaire status in the mortgage industry typically requires taking a company public or owning a massive wholesale lending institution like UWM or Rocket Mortgage.
How did the 2024 mortgage market affect his net worth?
The 2024 market was challenging due to high interest rates. However, because Casa’s model focuses on the "independent broker" channel—which gained market share from big banks in 2024—his personal net worth likely remained stable or grew as his company successfully recruited brokers looking for better options in a tough market.
Practical Recommendation for Industry Observers
For those tracking the financial success of industry figures like Anthony Casa, the best next action is to monitor quarterly recruitment data and total loan volume reports for UMORTGAGE. In the private mortgage sector, "headcount is health." As long as Casa continues to attract high-producing loan officers to his platform, the enterprise value of his holdings—and thus his personal net worth—will continue to follow an upward trajectory. Additionally, staying informed on CFPB rulings regarding mortgage broker compensation is vital, as these regulations are the "legal floor" upon which his business model is built.