Allstate’s "Mayhem" campaign uses personification to illustrate unpredictable risks that standard or cut-rate auto insurance may not fully cover. By identifying potential gaps—ranging from environmental hazards to human error—the campaign emphasizes the importance of comprehensive coverage and personalized policy limits to protect drivers against significant, unexpected financial losses in 2026.
The Evolution of Mayhem: From Marketing Concept to Risk Philosophy
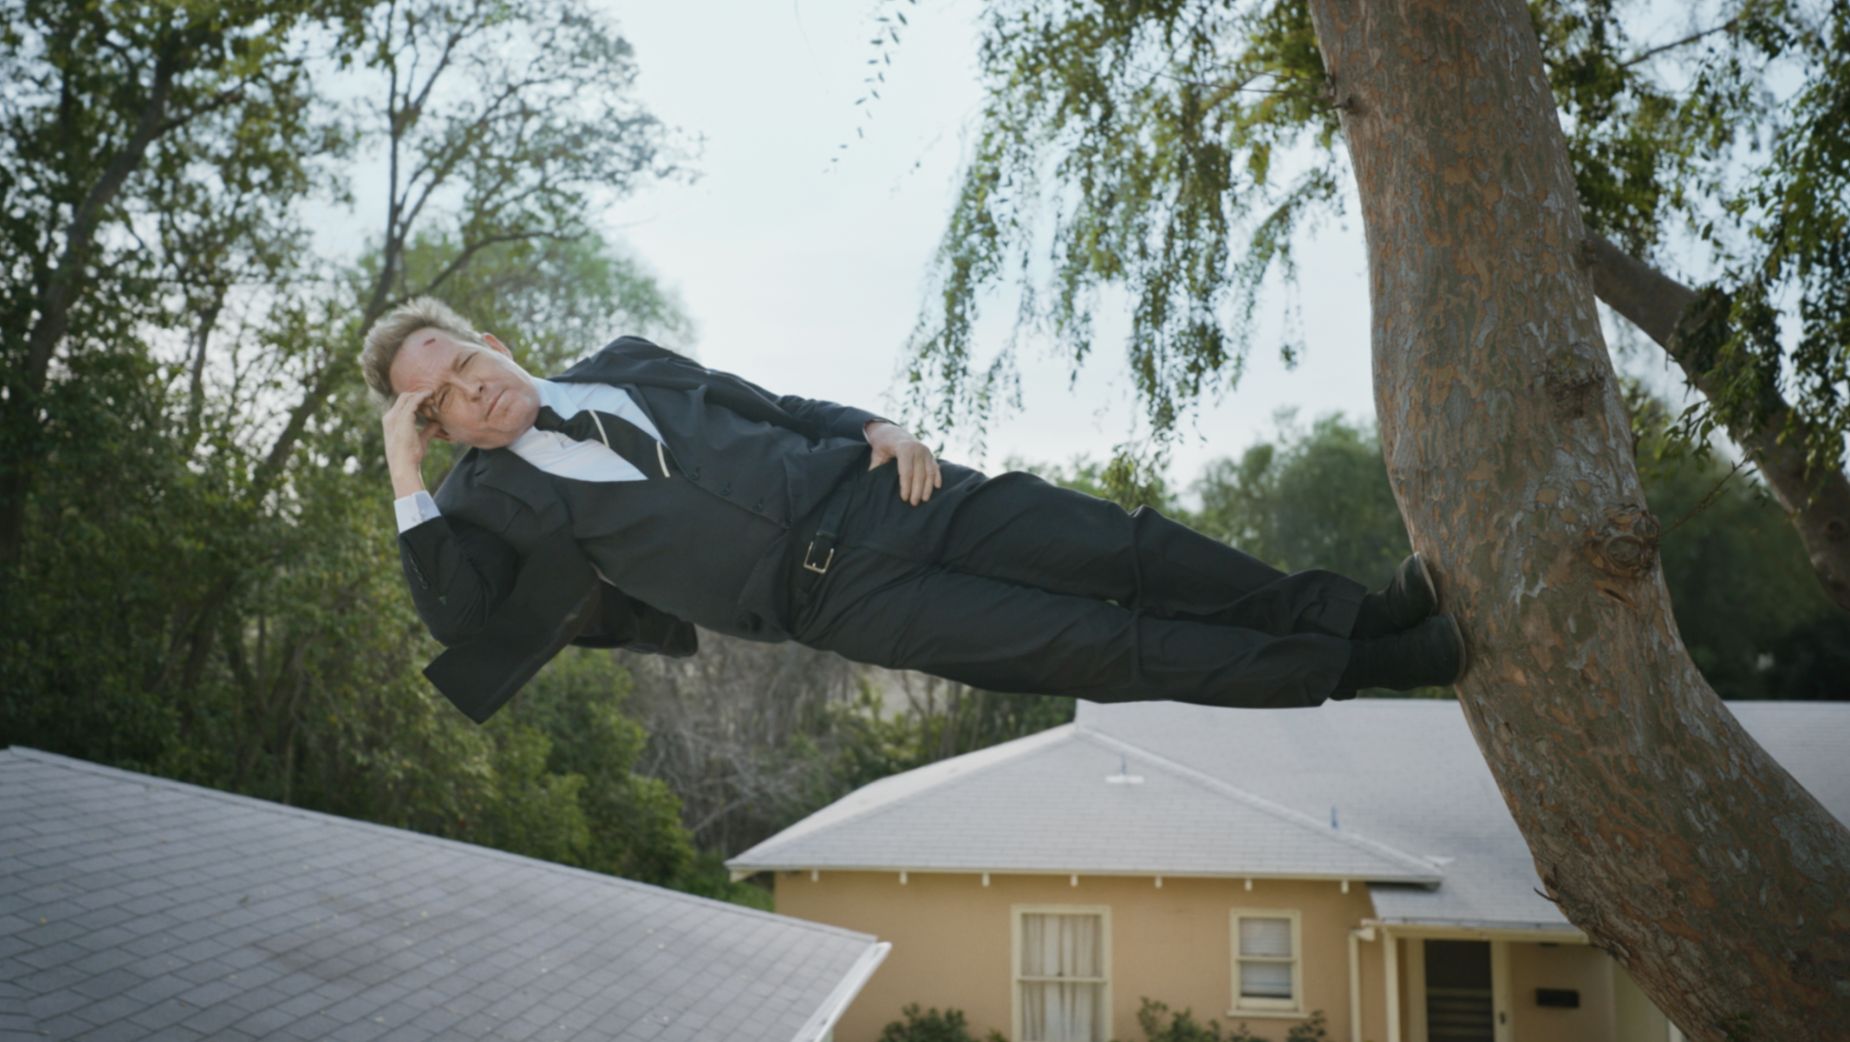
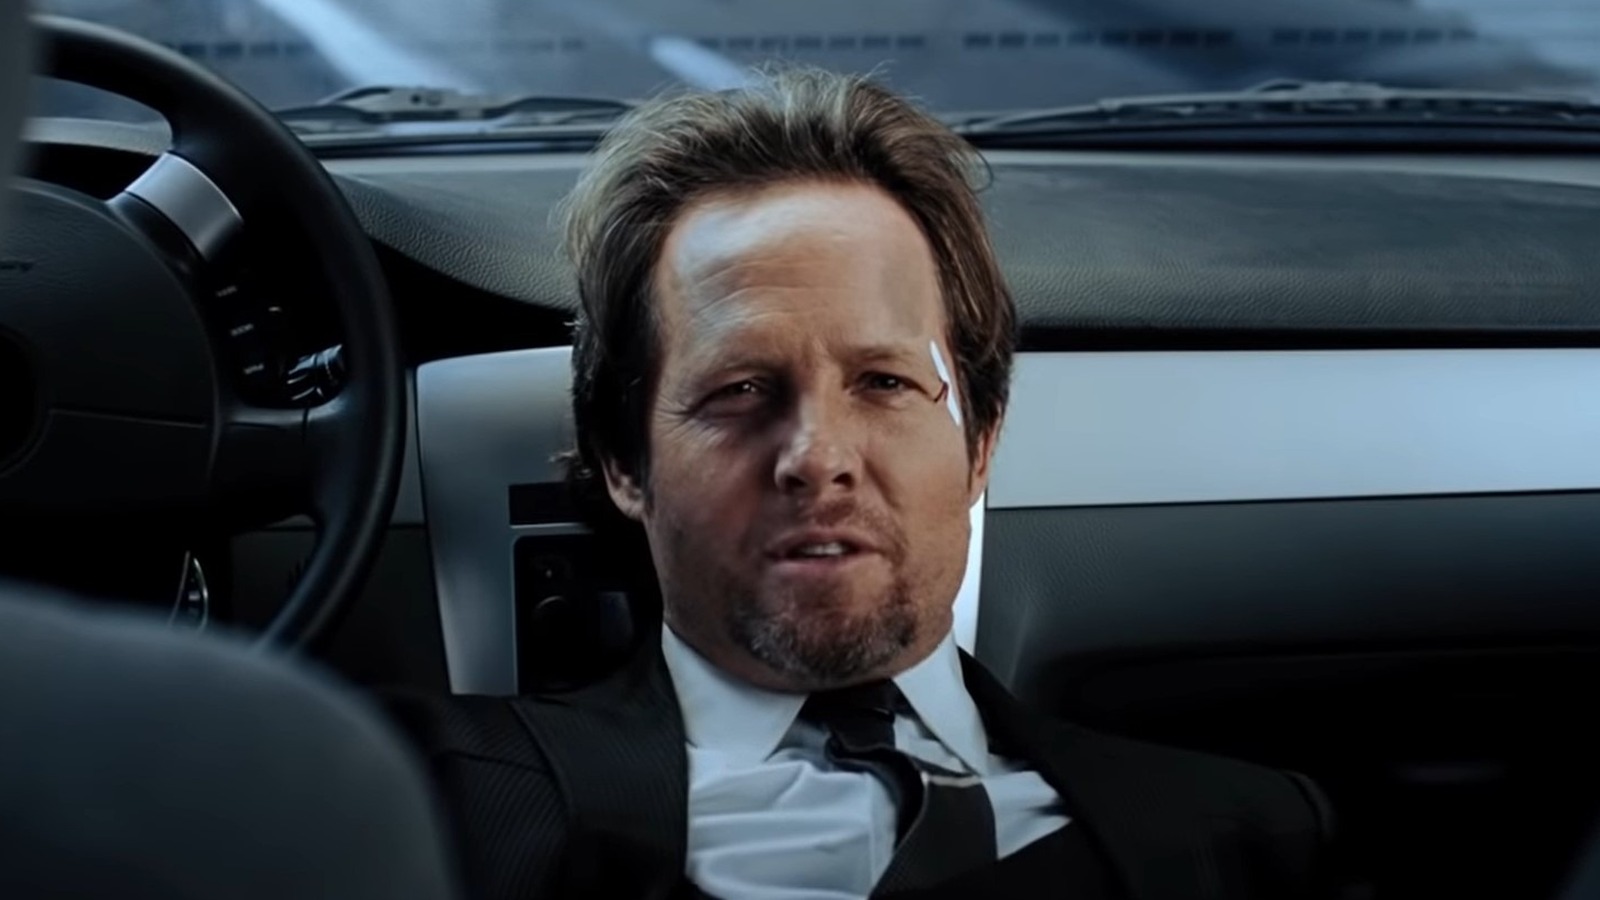
Since its inception in 2010, the Allstate "Mayhem" campaign, featuring actor Dean Winters, has transformed from a series of clever commercials into a core philosophy for the company’s risk management strategy. In 2026, the character of Mayhem remains a cultural touchpoint, representing the chaotic, unpredictable nature of the world. The campaign was originally designed by the agency Leo Burnett Chicago to combat the rise of "price-focused" insurance advertising that dominated the early 2000s. While competitors focused almost exclusively on saving consumers "15 percent or more," Allstate pivoted to focus on value and the catastrophic costs of being underinsured.
The "Mayhem" character embodies various hazards—a teenage driver’s blind spot, a heavy snowload on a roof, or a distracted driver looking at a smartphone. By the mid-2020s, this personification has evolved to include modern threats, such as sophisticated cyber-attacks on vehicle software and the unique risks associated with electric vehicle (EV) battery failures. The primary goal of the campaign is to remind consumers that while a "cut-rate" policy might save money on monthly premiums, it often leaves the policyholder vulnerable when "Mayhem" strikes.
In the current 2026 insurance landscape, Allstate utilizes the Mayhem branding to differentiate its high-touch agent model from digital-only insurers. The campaign argues that a professional agent can help identify where Mayhem is most likely to appear in a customer's specific life stage, whether that involves a new driver in the household or a move to a region prone to climate-related events.
Identifying Coverage Gaps: What "Mayhem" Teaches Policyholders
The genius of the Mayhem campaign lies in its ability to translate complex insurance jargon into relatable scenarios. To understand the technical depth of auto insurance in 2026, one must look at how these scenarios map to specific policy components. Allstate’s strategy is to highlight the distinction between "state minimum" coverage and "comprehensive protection."
Comprehensive vs. Collision Coverage
Many drivers confuse these two essential components. In the world of Mayhem, Collision coverage applies when the "Mayhem" character represents another vehicle or a stationary object you hit. For example, if Mayhem is a "large deer" that you swerve to avoid but end up hitting a guardrail, Collision coverage handles the damage to your car.
Comprehensive coverage, on the other hand, covers events that are "other than collision." This includes Mayhem personified as a branch falling from a tree due to a windstorm, a hailstone the size of a golf ball, or even a thief stealing your catalytic converter. In 2026, with the rising costs of vehicle parts and labor, Allstate emphasizes that having a low deductible on comprehensive coverage is vital for financial stability.
Liability Limits and Asset Protection
One of the most sobering Mayhem scenarios involves the "distracted driver" who causes a multi-car pileup. This illustrates the necessity of high Liability limits. Most states require a minimum amount of liability insurance, but these limits are often insufficient to cover the medical bills and property damage resulting from a major accident. If you are found at fault and your limits are exhausted, your personal assets—including your home and savings—could be at risk. Allstate uses the Mayhem campaign to push for "Umbrella Policies," which provide an extra layer of liability protection above and beyond standard auto and homeowners' limits.
Modern Mayhem: New Risks in the 2026 Automotive Landscape
As vehicle technology has advanced, so has the nature of risk. In 2026, auto insurance is no longer just about mechanical failures or physical collisions; it is increasingly about software and connectivity. Allstate has adapted the Mayhem campaign to reflect these 21st-century dangers.
Software Vulnerabilities and Cyber Risk
Modern vehicles are essentially computers on wheels. In 2026, a new form of Mayhem involves "The Hacker." While traditional auto insurance covers physical theft, Allstate has introduced specialized endorsements to handle cyber-related incidents. If a vehicle's infotainment system or autonomous driving sensors are compromised, the resulting "Mayhem" could lead to a collision. Allstate’s current offerings aim to bridge the gap between traditional physical damage and digital liability.
Electric Vehicles and Battery Infrastructure
The shift toward electric vehicles (EVs) has introduced unique risks that the Mayhem campaign has highlighted. Mayhem might portray an aging charging station that shorts out, causing damage to the vehicle's sensitive electrical architecture. These repairs are significantly more expensive than those for internal combustion engines. Allstate has structured its 2026 EV policies to account for these higher replacement costs, often including "New Car Replacement" coverage to ensure that an EV total-loss doesn't leave the driver with a massive loan balance and no car.
Comparing Allstate’s Value-Based Model to Cut-Rate Insurers
To help consumers decide if the Allstate approach is right for them, it is necessary to compare the features typically offered by Allstate against the "cut-rate" competitors that the Mayhem campaign warns against.
| Feature | Allstate "Mayhem-Proof" Policy | Typical "Cut-Rate" Policy |
|---|---|---|
| Claim Satisfaction Guarantee | Often included; allows premium credits if dissatisfied. | Rarely offered; focus is on lowest cost. |
| New Car Replacement | Available for first few model years. | Typically only covers Actual Cash Value (ACV). |
| Accident Forgiveness | Available (rates won't rise after one accident). | Rates usually spike immediately after a claim. |
| Deductible Rewards | $100 off deductible for every year of safe driving. | Fixed deductibles regardless of driving history. |
| Agent Support | Dedicated local agent for personalized advice. | Call center or AI-only support. |
| Telematics Integration | Drivewise® provides real-time coaching/discounts. | May have limited or no telematics options. |
Prerequisites for Securing Comprehensive Coverage with Allstate
Before approaching Allstate to build a policy that guards against Mayhem, consumers should prepare specific documentation and understand their own risk profile. In 2026, the underwriting process is more data-driven than ever.
- Vehicle Identification and Usage: You will need the VIN for all vehicles. In 2026, Allstate also asks for the estimated annual mileage dedicated to "gig work" (like ride-sharing or delivery), as this requires a specific commercial endorsement.
- Driving History (The MVR): Have your Motor Vehicle Record (MVR) ready. While Allstate offers accident forgiveness, initial quotes are heavily influenced by the last three to five years of driving history.
- Current Policy Declarations: To ensure you aren't leaving gaps, provide your current "Dec Page." This allows an agent to show you exactly where "Mayhem" could currently get through your defenses.
- Home/Auto Bundling Info: Allstate remains a leader in "bundling." Having your homeowner's or renter's information ready can lead to significant multi-policy discounts, often offsetting the cost of higher liability limits.
Troubleshooting Common Policy Issues
Even with the best marketing and agent support, policyholders sometimes face challenges. Understanding how to navigate these is part of being "Mayhem-ready."
- Rate Increases Despite Clean Records: In 2026, many drivers see rate hikes due to "inflationary pressures" on parts and labor. If your rate increases, ask your agent about Drivewise. This telematics program monitors braking, speed, and time of day to provide discounts based on actual driving behavior rather than general demographic statistics.
- Denied Claims for Custom Equipment: If you have added custom wheels, specialized paint, or high-end tech to your vehicle, standard policies might not cover them. You must verify that you have an "Optional Equipment" endorsement. Mayhem loves to target the parts of your car that aren't listed on the factory manifest.
- Issues with Gap Coverage: If you owe more on your car loan than the car is worth, you need Gap coverage. Many drivers assume this is automatic; it is not. Without it, Mayhem could leave you paying off a loan for a car that is currently sitting in a scrap yard.
Frequently Asked Questions
Who is the actor in the Allstate Mayhem commercials?
Dean Winters has portrayed "Mayhem" since the campaign's launch in 2010. Known for his roles in 30 Rock, Oz, and Law & Order: Special Victims Unit, Winters brings a "lovable but dangerous" energy to the character, which is essential for personifying risk without being overly macabre.
Does Allstate Mayhem coverage cost more than other companies?
Allstate is generally positioned as a premium insurer. While premiums may be higher than "budget" brands, the Mayhem campaign argues that the total cost of ownership is lower because Allstate policies typically provide better financial protection during a claim. The goal is to avoid the "out-of-pocket" disaster that occurs when a cheaper policy reaches its limits.
What is the "Mayhem" philosophy regarding teen drivers?
Allstate views teen drivers as a high-risk category (often portrayed by Mayhem as a distracted or emotional teen). To mitigate this, Allstate offers specific tools for parents, including teen-parent driving contracts and GPS-based monitoring, intended to educate the driver and reduce the likelihood of an accident before it happens.
How does Allstate handle climate-related Mayhem in 2026?
With the increase in extreme weather events, Allstate has refined its comprehensive coverage to include faster claims processing via drone inspections and AI-assisted damage assessment. This ensures that when Mayhem takes the form of a hurricane or wildfire, policyholders receive funds for repairs or replacement more rapidly than traditional manual inspections allowed.
Can I get a discount for being "Mayhem-free"?
Yes. Allstate offers various safe-driving bonuses and "Deductible Rewards." For every year you go without a claim (remaining "Mayhem-free"), Allstate may reduce your deductible or provide a check for a percentage of your premium, depending on your specific policy and state regulations.
Practical Recommendation for 2026 Drivers
To effectively protect yourself from "Mayhem" in 2026, do not simply accept the default limits suggested by online quote generators. Schedule a comprehensive review with a licensed Allstate agent specifically to discuss Life-Stage Risks.
Ask the agent to run a "What-If" analysis: "What if my car is totaled by an uninsured driver?" or "What if a tree falls on my car during a storm?" If the answer involves you paying more than your deductible out of pocket, you have a gap. Adjust your Comprehensive and Uninsured Motorist coverage accordingly. Finally, enroll in a telematics program like Drivewise to ensure your premiums are based on your actual safety habits, providing a financial buffer against the rising costs of insurance.