When a household possesses a net worth of less than zero, its total financial liabilities—such as mortgages, student loans, credit card balances, and auto loans—exceed the total value of its assets, including cash savings, real estate, and investments. This state of negative net worth affects a significant share of the population, particularly younger demographics facing high education costs and housing barriers, highlighting the critical role of asset accumulation and debt management in long-term economic stability.
Defining Negative Household Net Worth
Net worth serves as a primary indicator of financial health, calculated simply by subtracting total liabilities from total assets. When this equation yields a negative number, a household is technically insolvent on paper, even if its members earn a steady income and pay their bills on time. Understanding this dynamic requires examining how assets and liabilities interact across different stages of life and economic cycles.
Assets encompass everything of monetary value that an individual or family owns. These include liquid accounts like checking and savings, tangible property such as homes and vehicles, and long-term holdings like retirement accounts and investment portfolios. Conversely, liabilities represent all outstanding debts and financial obligations. While some liabilities fund appreciating assets—such as a mortgage backing a residential property—others finance consumption or education, which may not yield immediate tangible returns.
The prevalence of negative net worth is not distributed evenly across the population. Economic studies from institutions like the Federal Reserve indicate that younger households, particularly those headed by individuals under the age of 35, frequently experience negative or near-zero net worth. This phenomenon is largely structural rather than a sign of reckless behavior; it stems from the timing of major financial milestones. Young adults often accumulate substantial student loan debt before they have had time to secure high-paying employment, purchase homes, or build retirement funds.
Primary Drivers of Negative Net Worth
Several distinct financial mechanisms contribute to a household falling into a negative net worth position. Recognizing these drivers helps distinguish between temporary, strategic debt and chronic financial distress that threatens long-term security.
Educational Debt and Human Capital
Student loans represent one of the largest categories of non-mortgage debt for households. While higher education is widely viewed as an investment in future earning potential—often referred to as human capital—the immediate accounting reality is a large liability with no matching liquid asset. A recent college graduate might carry tens of thousands of dollars in student loans while having virtually zero savings, creating a negative net worth that can persist for years despite a stable entry-level salary.
Housing Market Dynamics and Mortgages
Purchasing a home typically involves taking on a large liability in the form of a mortgage. In the early years of homeownership, the remaining loan balance often exceeds the market value of the property, especially when buyers make small down payments and account for closing costs and real estate transaction fees. While this negative equity position is often temporary as the principal is paid down and the property appreciates, market downturns can trap households in a state of negative net worth for extended periods.
Consumer Debt and Emergency Expenses
Unsecured debt, including credit cards, personal loans, and medical bills, contributes directly to liabilities without acquiring any corresponding asset. When households rely on high-interest credit to cover daily living expenses, unexpected medical emergencies, or vehicle repairs due to a lack of emergency savings, their debt burdens compound rapidly. This form of negative net worth is particularly precarious because it incurs high carrying costs that erode disposable income.
Financial and Psychological Impacts
Carrying a negative net worth carries both practical economic consequences and psychological weight. While the numbers on a balance sheet tell a specific story, the lived experience of financial insolvency varies widely depending on the composition of the debt and the household's cash flow.
From a financial perspective, negative net worth limits borrowing capacity and increases the cost of capital. Lenders evaluate net worth and debt-to-income ratios when underwriting loans for housing, vehicles, or business ventures. A household with negative net worth may face higher interest rates, stricter terms, or outright denial of credit, making it more difficult to achieve traditional milestones like homeownership. Furthermore, servicing high-liability balances diverts cash flow away from wealth-building activities such as investing in retirement accounts or building emergency funds.
Psychologically, financial insolvency can generate chronic stress and anxiety. Societal expectations often equate net worth with personal success, leading individuals to internalize their balance sheet status. This stress can impact decision-making, sometimes leading to avoidance of financial planning or falling prey to predatory financial services promising quick relief from debt.
| Debt Category | Typical Asset Counterpart | Liquidity Level | Impact on Early Net Worth |
|---|---|---|---|
| Student Loans | Future Earning Potential (Human Capital) | Non-liquid | High negative impact |
| Mortgages | Residential Real Estate | Illiquid | Moderate to high negative impact |
| Auto Loans | Depreciating Vehicles | Semi-liquid | Moderate negative impact |
| Credit Cards | Consumer Goods / None | Liquid | High negative impact (high cost) |
Strategies for Reversing Negative Net Worth
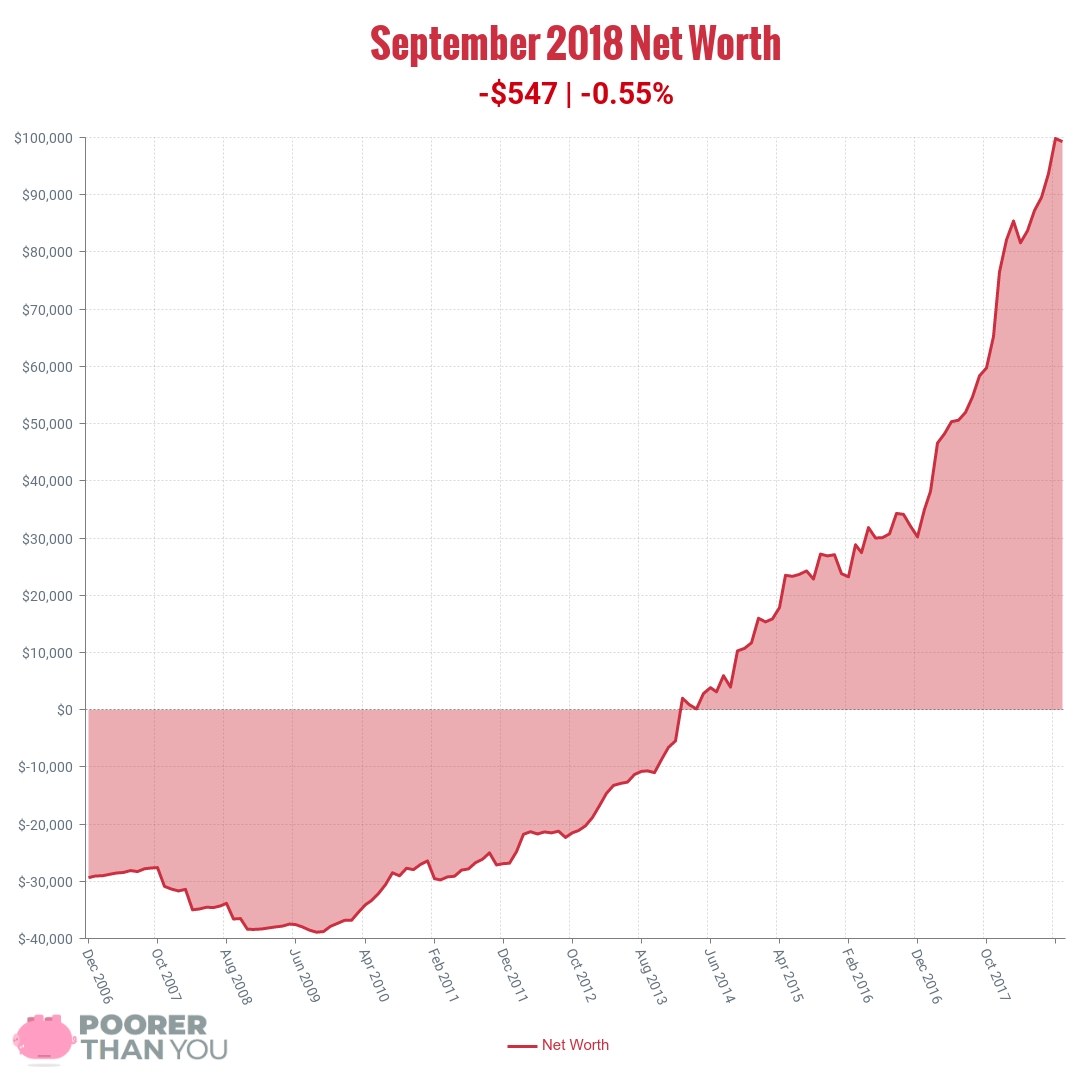
Transitioning from a negative net worth to a positive one is a gradual process focused on two primary levers: reducing liabilities and building assets. Because net worth is a cumulative metric, small, consistent changes compounded over time yield significant structural improvements.
The first step in financial rehabilitation is establishing a clear inventory of all assets and liabilities. Many households operate without a precise accounting of their total financial position, making it difficult to target high-cost debt effectively. By listing every account, loan balance, and property value, individuals can calculate their baseline net worth and monitor progress on a quarterly or annual basis.
Debt reduction strategies generally follow one of two popular frameworks: the debt avalanche method, which prioritizes paying off debts with the highest interest rates to minimize total interest paid, or the debt snowball method, which focuses on clearing the smallest balances first to build psychological momentum. For unsecured consumer debt, exploring consolidation options or negotiating with creditors can lower interest rates and accelerate repayment timelines.
Simultaneously, households must focus on asset accumulation, even while paying down debt. Establishing an emergency fund in a high-yield savings account prevents reliance on credit cards when unexpected expenses arise. Additionally, contributing to employer-sponsored retirement plans, especially up to any matching contribution threshold, captures an immediate return on investment that accelerates the growth of the asset side of the balance sheet.
Frequently Asked Questions
Is a negative net worth always a sign of financial trouble?
No. For young adults, recent graduates, or individuals who have recently purchased a home with a mortgage, negative net worth is often a normal phase of the financial lifecycle. As long as the household maintains positive cash flow to service its debts and the underlying liabilities fund appreciating assets or human capital, negative net worth can be a temporary and strategic stepping stone.
How long does it typically take to move from negative to positive net worth?
The timeline varies widely based on individual circumstances, income levels, and the composition of debt. For a college graduate with student loans, it may take five to ten years of consistent career progression, debt repayment, and modest saving to cross into positive net worth. For those weighed down by high-interest consumer debt, the timeline depends heavily on disciplined budgeting and aggressive debt reduction.
Does having a high income guarantee a positive net worth?
Income and net worth are distinct financial measures. High-income earners can still have a negative net worth if their consumption and debt payments outpace their earnings and asset accumulation. Lifestyle inflation—the tendency to increase spending as income rises—frequently prevents high earners from building substantial net worth if they fail to invest or pay down liabilities.
How do student loans affect mortgage eligibility when net worth is negative?
Mortgage lenders look primarily at monthly debt-to-income ratios rather than total net worth alone. While student loan debt increases total liabilities, lenders evaluate whether the household's monthly income is sufficient to cover housing costs alongside existing debt obligations. However, a significant negative net worth driven by delinquent accounts or high credit card balances will negatively impact credit scores and mortgage terms.
What is the most effective way to start tracking net worth?
Tracking net worth requires updating a simple spreadsheet or utilizing reputable financial aggregation software on a regular schedule, such as every month or quarter. The process involves summing all cash, investments, and estimated property values, then subtracting all outstanding loan balances and credit card liabilities to monitor the net trajectory over time.
Conclusion and Next Actions
Navigating a household net worth of less than zero requires distinguishing between structural investments in the future and detrimental consumer debt. Households facing negative net worth should prioritize stabilizing cash flow, protecting themselves against unexpected emergencies, and systematically reducing high-interest liabilities while slowly nurturing asset growth through disciplined saving and investing.