A 529 plan serves as a powerful tool for estate planning because it allows an account owner to remove assets from their taxable estate while maintaining control over the funds. By utilizing special gift tax rules, individuals can contribute significant amounts to these accounts to reduce their total estate value, potentially minimizing future federal estate taxes for their heirs.
Understanding the 529 Plan Mechanism in Estate Planning
A 529 plan, formally known as a Qualified Tuition Program, is traditionally viewed as an educational savings vehicle. However, its unique tax treatment under the Internal Revenue Code makes it a sophisticated asset-transfer instrument. When an individual contributes to a 529 plan, the money is considered a completed gift to the beneficiary for federal gift tax purposes. Crucially, the account owner retains the legal right to change the beneficiary or withdraw the funds, despite the assets no longer being legally part of their taxable estate.
This decoupling of legal control from estate tax inclusion is the cornerstone of 529 estate planning. By moving assets into a 529 account, you effectively "freeze" the value of those assets for estate tax purposes, shielding any future growth from being counted toward your lifetime estate tax exemption.
Leveraging the Five-Year Gift Tax Averaging Rule
The most significant benefit for estate planners is the "superfunding" provision, formally known as gift tax averaging. Under federal guidelines as of 2026, you may contribute up to five times the annual gift tax exclusion amount to a single beneficiary’s 529 plan in a single year without incurring a federal gift tax.
For example, if the annual gift tax exclusion is $19,000, an individual could contribute $95,000 in one year. This amount is treated as if it were made in equal installments over five years. If you survive the five-year period, the entire amount is removed from your taxable estate. If you pass away during this five-year window, the portion of the gift allocated to the remaining years is recaptured and added back to your taxable estate.
Strategic Advantages for High-Net-Worth Individuals
For individuals whose estates may exceed the federal estate tax exemption, the 529 plan offers a way to transfer wealth to younger generations while simultaneously addressing their education costs. Because 529 plan growth is tax-free when used for qualified higher education expenses, the effective value of the gift compounds significantly over time compared to assets held in a taxable brokerage account.
Furthermore, these plans are not limited to immediate family. Many estate planners use them to benefit grandchildren or even future generations. By contributing to a 529 plan, you ensure that the wealth remains earmarked for specific educational purposes, providing you with a level of oversight that an outright gift of cash or securities does not offer.
Comparing Traditional Gifting to 529 Plan Contributions
| Feature | Outright Cash Gift | 529 Plan Contribution |
|---|---|---|
| Estate Tax Removal | Immediate | Immediate |
| Control of Assets | None (given away) | Retained by Account Owner |
| Tax-Deferred Growth | No | Yes |
| Gift Tax Averaging | Not applicable | Available (5-year rule) |
| Asset Earmarking | None (recipient's choice) | Educational use required |
Navigating Successor Ownership
A critical, often overlooked aspect of 529 estate planning is the designation of a successor owner. If the account owner dies, the assets in the 529 plan could be pulled back into the owner's estate if there is no clear successor owner designated, depending on the state’s specific administrative rules and the plan's participation agreement.
You should designate a successor owner to ensure that control of the account passes seamlessly to the intended person—usually a spouse or a parent of the beneficiary. This prevents the account from becoming part of your probate estate, which could lead to complications in account management and potentially create unnecessary tax liabilities. Always verify the process for updating your successor owner within your specific plan’s portal, as these records should be reviewed periodically during your broader estate planning sessions.
Potential Pitfalls and Limitations
While 529 plans are highly effective, they are not a panacea for all estate planning challenges. There are several risks and limitations to consider:
- Recapture Risk: As mentioned, if you utilize the five-year gift tax averaging rule and die within that five-year window, the prorated portion of the gift for the remaining years must be reported on your estate tax return.
- Qualified Expense Limits: If the beneficiary does not use the funds for qualified education expenses, the earnings portion of a non-qualified withdrawal is subject to federal income tax plus a 10% penalty. This can undermine the goal of wealth transfer if the funds are mismanaged by the recipient.
- State-Level Taxes: While federal law governs the estate tax status, state-level estate or inheritance taxes may treat 529 assets differently. It is essential to consult with a professional familiar with your state’s specific tax statutes.
- Ownership Disputes: Because the account owner has total control, a divorce or creditor claim against the account owner could potentially put the 529 assets at risk, depending on state law.
Integrating 529s into Your Broader Estate Plan
An effective estate plan is holistic. A 529 plan should not exist in a vacuum. It should be coordinated with your revocable living trust, your last will and testament, and your overall gifting strategy.
If you are using a trust to hold assets, check the governing documents to determine if the trustee is permitted to open and fund a 529 plan on behalf of a beneficiary. Some trusts are specifically drafted to provide for educational expenses, and a 529 plan can be an excellent way to fulfill the trustee's fiduciary duty while maximizing tax efficiency.
Frequently Asked Questions
Does the 529 account owner have to be a family member? No, but the owner must be a person or a qualified entity. The beneficiary must be a family member of the owner or a designated member of the family, but the owner retains full control regardless of their personal relationship to the beneficiary.
Can I contribute to a 529 plan if I am already at my lifetime gift tax limit? If you have exhausted your lifetime federal gift tax exemption, contributions to a 529 plan may be subject to gift taxes. However, the five-year averaging rule can still be used to spread the gift over multiple years, potentially staying within the annual exclusion limits for each of those years.
What happens to the 529 account if the beneficiary dies? In the event of a beneficiary's death, you generally have the option to change the beneficiary to another family member without tax consequences, or you can withdraw the funds. If you withdraw the funds, you will pay income tax on the earnings, though the 10% penalty is usually waived in the event of the beneficiary's death.
Does a 529 plan count as an asset for my children's financial aid? If the 529 plan is owned by a parent or a dependent student, it is generally treated as a parental asset for federal financial aid purposes, which has a much smaller impact on aid eligibility than assets held directly by the student. If the account is owned by a grandparent, it traditionally had no impact on federal aid, though reporting requirements have evolved.
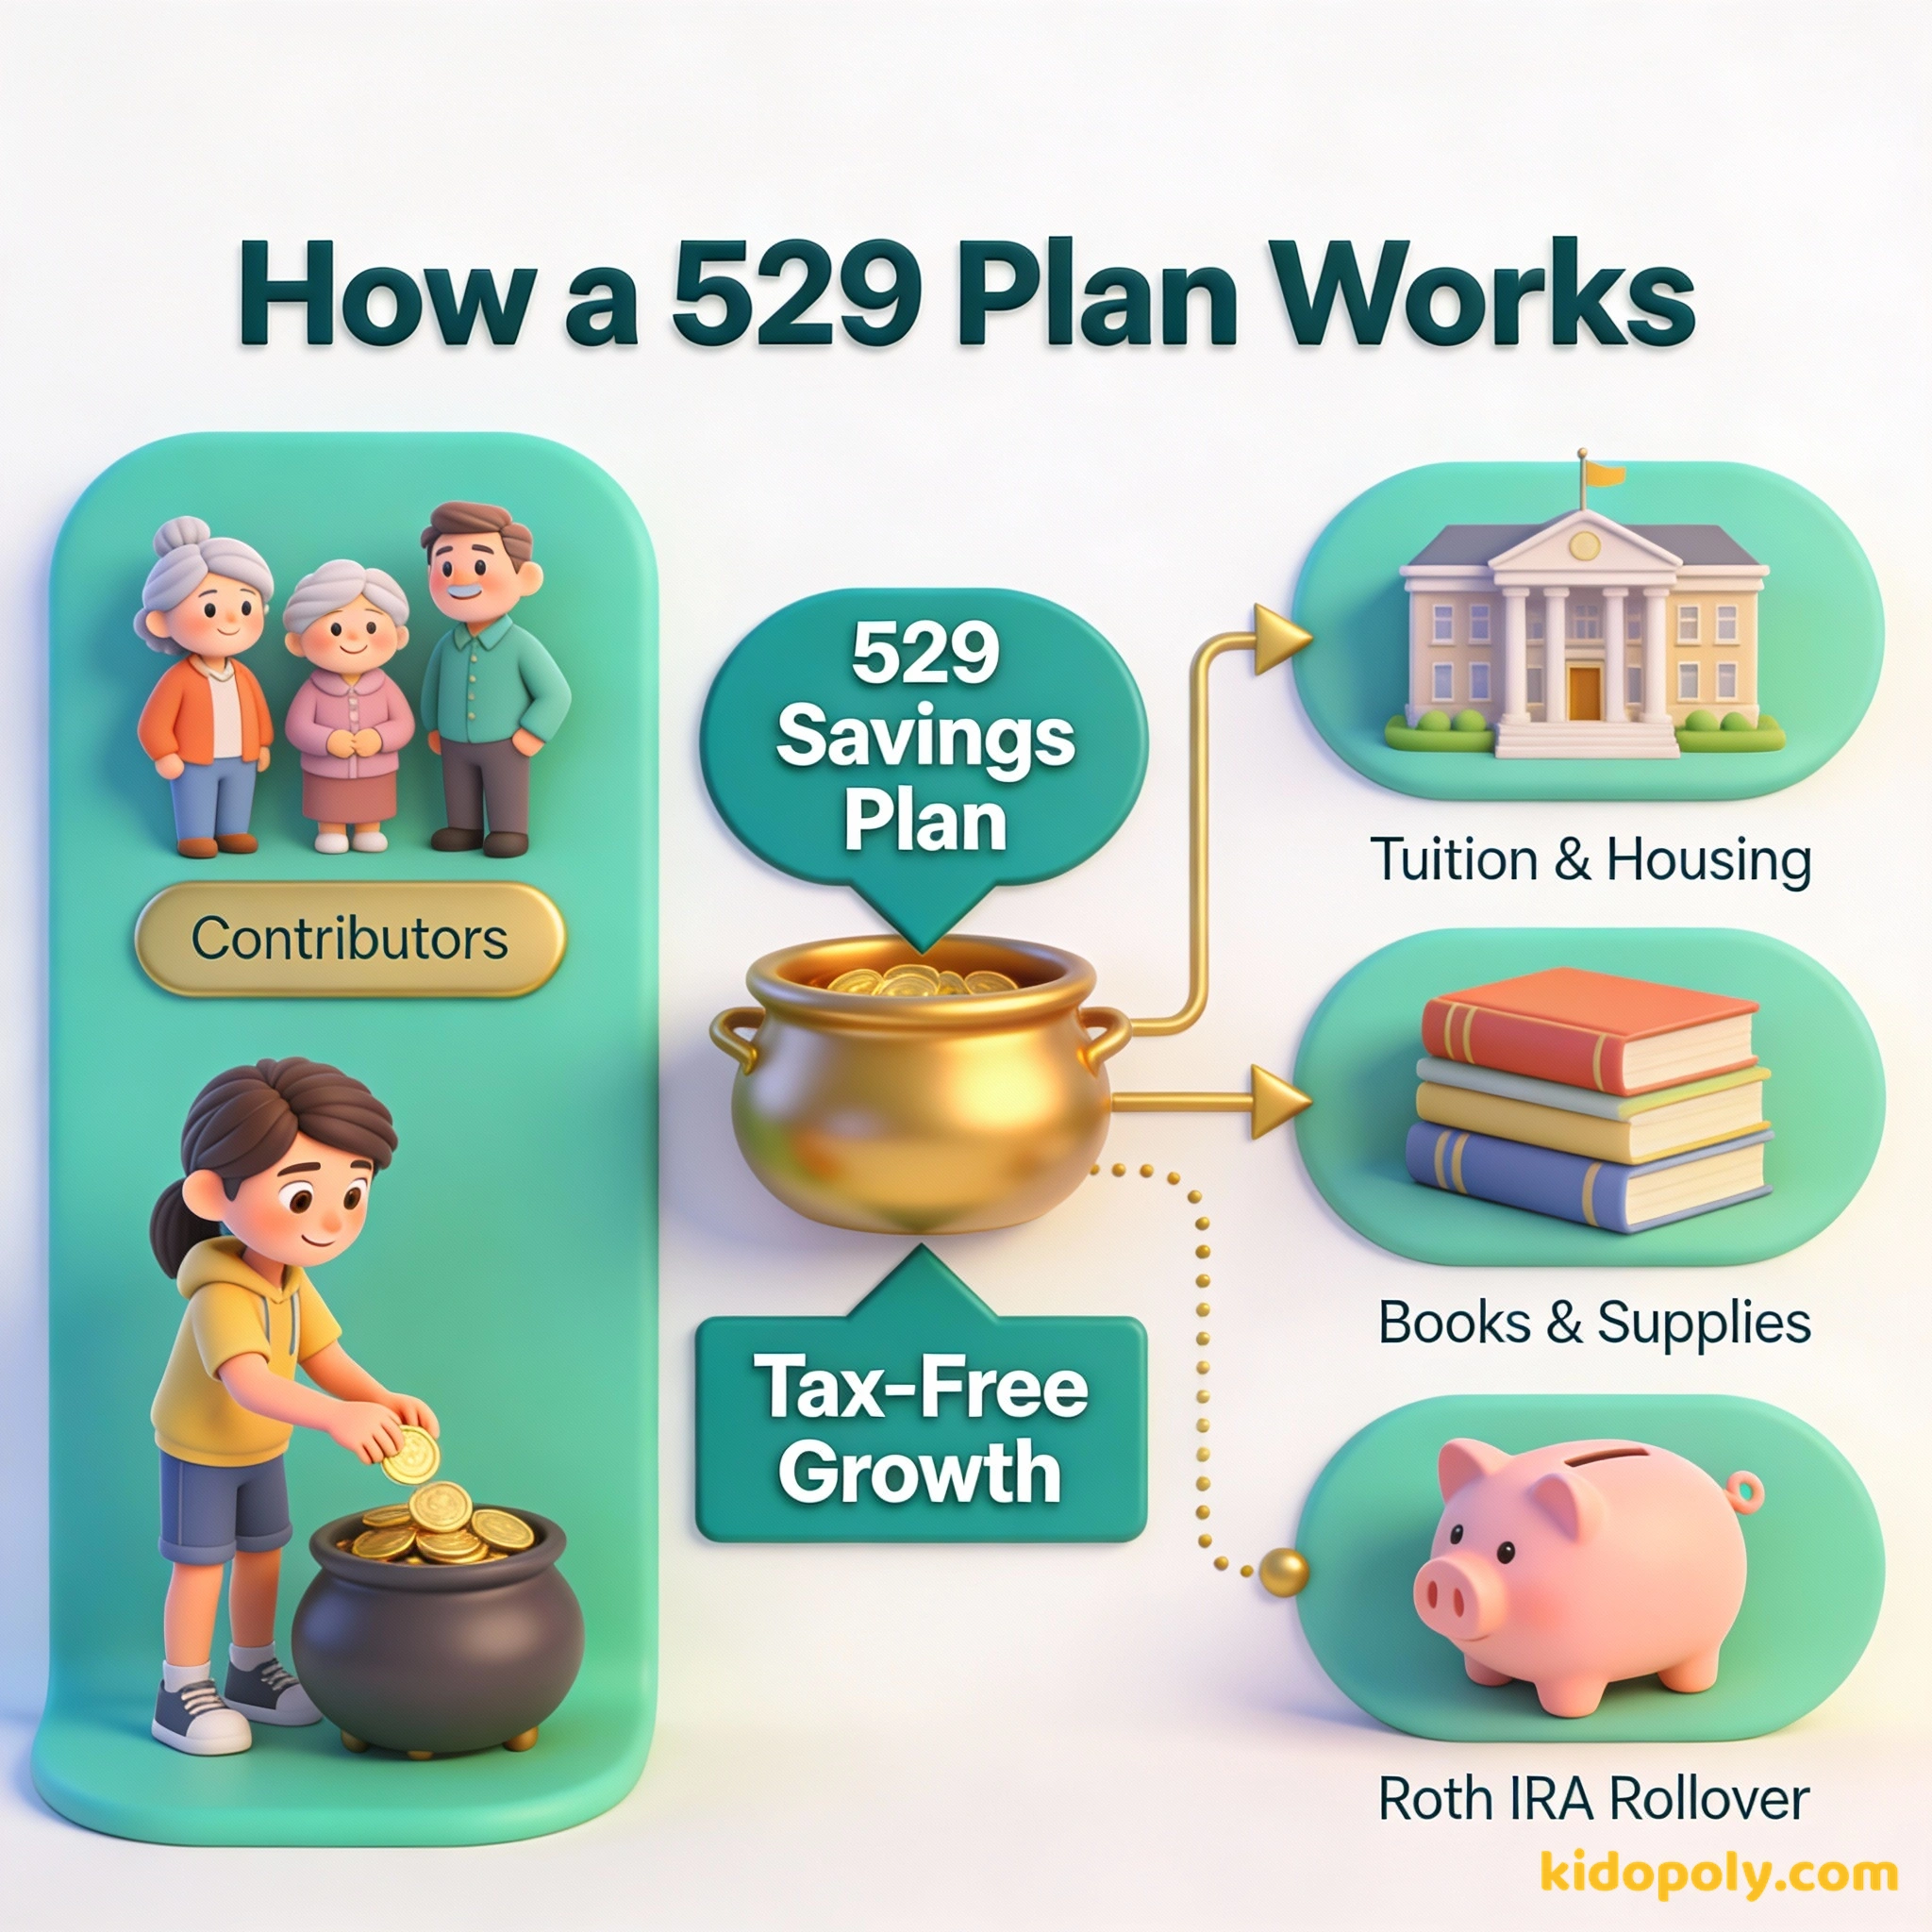
Can I use a 529 plan to pay for anything other than tuition? Yes, qualified expenses include tuition, fees, books, supplies, and equipment required for enrollment. It also includes room and board for students enrolled at least half-time, as well as certain computer-related expenses and internet access. Always maintain documentation of these expenses.
Next Steps for Implementation
To begin integrating 529 plans into your estate strategy, take the following steps:
- Review your current estate plan: Identify the total value of your assets and determine if reducing your taxable estate is a priority.
- Consult a tax professional: Discuss the interplay between your specific estate size and the potential for 529 "superfunding."
- Select a plan: Research plans based on your state of residence, as many states offer state income tax deductions for contributions.
- Update beneficiaries and successors: Ensure all your 529 plan accounts have designated successor owners updated as of 2026.
Disclaimer: This information is for educational purposes only and does not constitute legal or financial advice. Estate tax laws are complex and subject to change; always consult with a qualified attorney or tax professional regarding your specific financial situation.