Determining if Cason Home Loans is the best choice depends on your priority: personalized service or the lowest possible digital rate. Cason excels in providing tailored, local expertise and a diverse range of loan products—including FHA, VA, and Jumbo loans—making them an excellent choice for first-time buyers and those valuing human guidance over automated algorithms.
The mortgage landscape in 2026 remains complex, with fluctuating interest rates and a competitive housing inventory that demands quick, reliable pre-approvals. In this environment, the "best" lender isn't just the one with the lowest advertised APR, but the one that can actually close your loan on time without hidden hurdles. Cason Home Loans has built a reputation as a regional powerhouse that bridges the gap between massive national banks and small local credit unions.
Understanding the Cason Home Loans Value Proposition
Cason Home Loans operates primarily as a retail mortgage lender. Unlike "big box" banks that offer checking accounts, credit cards, and auto loans, Cason focuses exclusively on home financing. This specialization is a significant factor when evaluating if they are the right fit for you. When a company’s entire revenue model depends on successful mortgage originations, their staff is typically more attuned to the nuances of property appraisals, title issues, and specific state-level lending regulations.
In 2026, many borrowers find themselves frustrated by the "black box" experience of large online lenders where they are treated as a file number rather than a person. Cason leans into a high-touch service model. This means you are usually assigned a dedicated loan officer who manages your file from pre-qualification through to the closing table. For a first-time homebuyer or someone with a complex financial history—such as self-employment income or a recent career change—this human element is often the difference between an approval and a denial.
Comprehensive Loan Product Availability
To decide if Cason is the best choice, you must look at their product shelf. A lender is only as good as the options they provide to meet your specific financial profile.
Conventional Mortgages
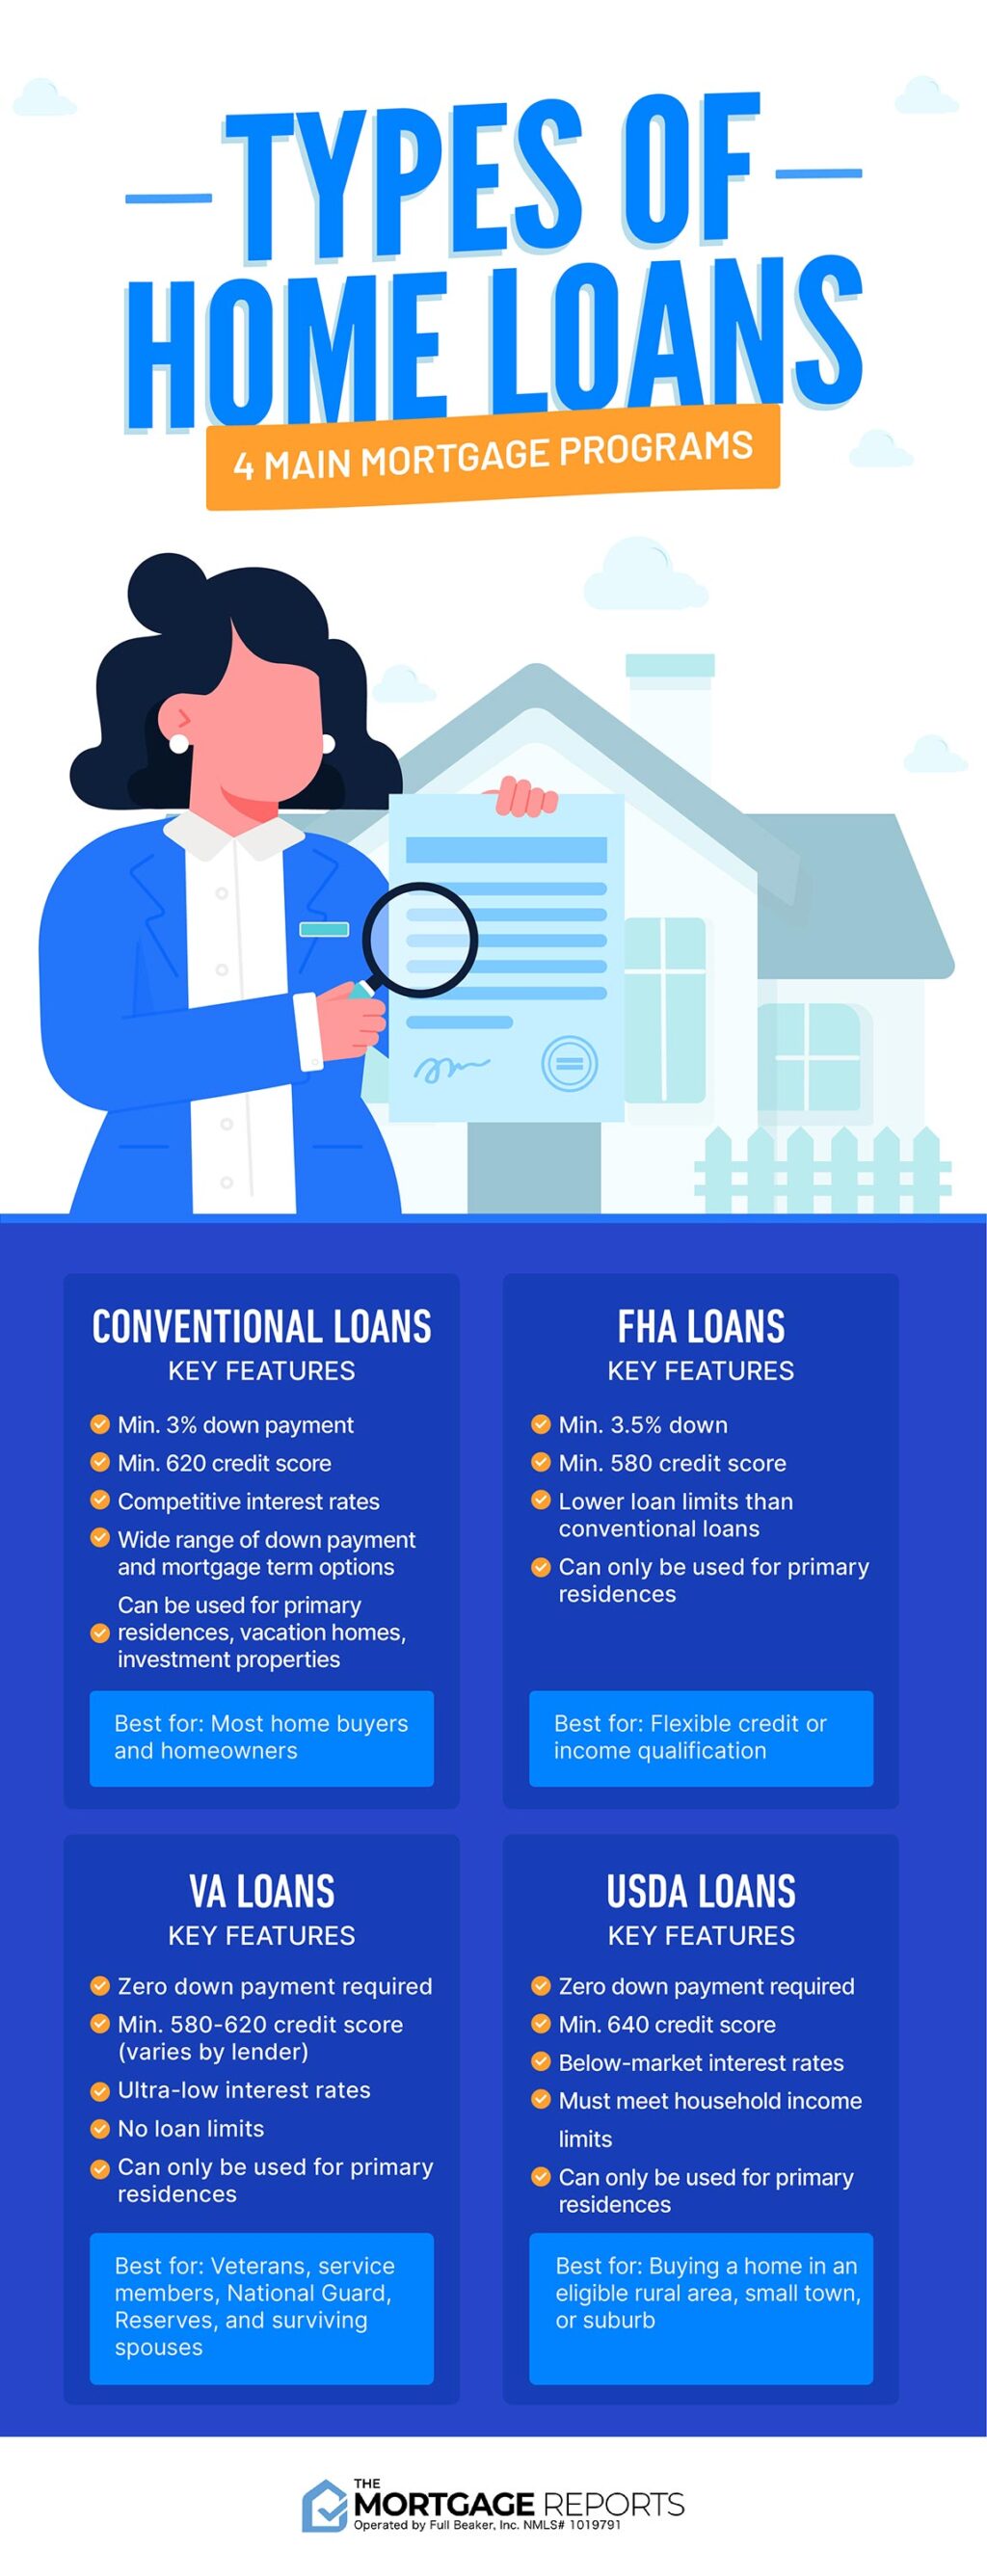
Cason offers standard conventional loans that adhere to the guidelines set by Fannie Mae and Freddie Mac. In 2026, these remain the most popular choice for borrowers with credit scores above 620 and at least a 3% down payment. Cason’s advantage here lies in their ability to price these loans competitively while offering flexible terms, such as 15, 20, or 30-year fixed rates, as well as adjustable-rate mortgages (ARMs) for those planning to move within a few years.
FHA Loans
For borrowers who may have a lower credit score or limited cash for a down payment, Cason provides Federal Housing Administration (FHA) loans. These require as little as 3.5% down. Cason’s underwriters are experienced in navigating the specific FHA appraisal requirements, which can sometimes be more stringent regarding the condition of the home. This expertise helps prevent "deal-killers" late in the escrow process.
VA and USDA Financing
Cason is a strong supporter of military members and rural homebuyers. VA loans offer 0% down payment options for eligible veterans and active-duty service members, often with lower interest rates than conventional products. USDA loans are also available for homes in designated rural areas, providing another zero-down option for low-to-moderate-income families. Cason’s ability to handle these government-backed programs in-house speeds up the verification process significantly.
Jumbo Loans
As property values in many regions have continued to rise through 2026, many homes now exceed the conforming loan limits set by the FHFA. Cason offers Jumbo loans to accommodate these high-value purchases. These loans require higher credit scores and larger down payments (typically 10-20%), but Cason’s individualized underwriting allows for a more holistic view of a borrower’s assets compared to the rigid automated systems of larger competitors.
Analyzing Costs: Rates, Fees, and Transparency
When asking if a lender is the "best," the conversation inevitably turns to the bottom line. Cason Home Loans is a mortgage banker, meaning they fund their own loans but eventually sell them on the secondary market or to investors. This allows them to set their own pricing to an extent.
Interest Rates Cason’s rates are generally competitive with other mid-sized regional lenders. They may not always beat the "loss-leader" rates advertised by massive online lenders who use low rates as marketing bait, but Cason’s quoted rates are often more "real." This means the rate you are quoted after a credit pull is more likely to be the rate you actually get, without the last-minute additions of "discount points" that many national lenders use to inflate their profit margins.
Origination and Closing Costs Every lender charges fees to process and underwrite a loan. These can include application fees, credit report fees, and origination charges. Cason is known for transparent Fee Worksheets. In 2026, savvy borrowers should look for a "Loan Estimate" (LE) early in the process. Cason’s commitment to transparency means their LEs rarely fluctuate significantly by the time you reach the "Closing Disclosure" (CD) phase, provided the property appraisal and your credit profile remain stable.
The Application and Digital Experience in 2026
While Cason emphasizes human interaction, they have not ignored the digital shift. By 2026, their "Digital Mortgage" portal has become a central hub for the borrowing experience.
- Digital Document Upload: Borrowers can securely link their bank accounts and payroll providers to automatically import W-2s, pay stubs, and bank statements. This reduces the manual "paperwork chase" that traditionally plagued the mortgage process.
- Mobile Accessibility: The ability to check your loan status, upload a missing document via a smartphone camera, and communicate with your loan officer via secure chat is standard.
- Hybrid Closings: Cason supports e-closings where allowed by state law. This allows you to sign the majority of your closing documents digitally from home, with only a brief meeting with a notary for the final deed signatures.
This hybrid approach—high-tech backend with high-touch frontend—is why many consider them a "best choice" candidate. You get the efficiency of a fintech company with the accountability of a local professional.
Comparing Cason Home Loans to the Competition
To provide a clear picture, it is helpful to see how Cason stacks up against the different types of lenders available in the 2026 market.
| Feature | Cason Home Loans | National "Big Box" Banks | Online-Only Lenders |
|---|---|---|---|
| Personalized Guidance | High: Dedicated Loan Officer | Low: Call center environment | Very Low: Primarily automated |
| Product Variety | Broad: Conventional, FHA, VA, USDA, Jumbo | Moderate: Often favor conventional | Broad: High variety of niche products |
| Speed to Close | Fast: Focused on purchase market | Slow: Bureaucratic delays common | Fast: Algorithm-driven |
| Interest Rates | Competitive / Market Average | Moderate to High | Often Lowest (Initial Quote) |
| Local Market Knowledge | High: Understanding of local taxes/regs | Low: Standardized national policies | Low: Zero local presence |
| Ease of Application | Hybrid: Digital portal + Human help | Traditional: Often requires in-person | High: Fully digital/DIY |
Technical Prerequisites for Borrowing with Cason
To ensure your experience with Cason is successful, you should meet certain technical financial benchmarks. While they are flexible, the 2026 lending environment still adheres to "Ability to Repay" standards.
- Debt-to-Income (DTI) Ratio: For conventional loans, Cason typically looks for a DTI of 43% or lower, though they may go up to 50% with compensating factors (like high cash reserves). For FHA loans, this can sometimes be stretched further.
- Credit Score Requirements: While 620 is the standard floor for conventional, a score of 740+ will secure the best possible pricing. Cason does work with borrowers in the 580-620 range specifically through FHA programs.
- Employment Stability: You will generally need a two-year history in the same industry. Cason is particularly adept at handling "non-W2" income, but you will need to provide at least two years of federal tax returns to verify "stable and predictable" earnings.
Common Pitfalls to Avoid During the Process
Even with a top-tier lender like Cason, the mortgage process can be derailed by borrower actions. To maintain your "best choice" status with the lender, avoid these mistakes:
- Opening New Credit Lines: Do not buy a new car or apply for a furniture store credit card after you have been pre-approved. This changes your DTI and can trigger a loan denial just days before closing.
- Large Undocumented Deposits: If you receive a gift for your down payment, it must be documented with a "gift letter" and a paper trail. Moving large sums of cash between accounts without documentation creates red flags for anti-money laundering audits.
- Changing Jobs: Even if it is a promotion or a higher-paying role, changing jobs during the mortgage process requires new verification and can delay your closing by weeks. Always consult your Cason loan officer before making a career move during escrow.
Who is Cason Home Loans Not Best For?
No lender is perfect for everyone. Cason might not be your best choice if:
- You are a "rate shopper" who only cares about the lowest possible basis point and is willing to sacrifice service and communication to get it.
- You prefer a completely anonymous, 100% DIY digital experience where you never have to speak to a human being.
- You are looking to bundle your mortgage with other banking products like high-yield savings or complex investment portfolios for a "relationship discount" that only the largest global banks provide.
FAQ
What states does Cason Home Loans operate in for 2026? Cason Home Loans is primarily a regional lender with a strong presence in the Midwest (headquartered in Michigan) and surrounding states. However, they have expanded their licensing to cover many states across the U.S. It is always best to check their current NMLS (Nationwide Multistate Licensing System) registry or their official website to see if they are licensed in your specific state.
How long does it typically take to close a loan with Cason? In the current 2026 market, Cason aims for a "purchase-ready" timeline of 21 to 30 days. Because they handle most of the processing and underwriting in-house, they can often move faster than large commercial banks, which may take 45 to 60 days. Refinances can sometimes take slightly longer depending on appraisal turn-times in your area.
Does Cason Home Loans offer down payment assistance programs? Yes, Cason frequently participates in state and local down payment assistance (DPA) programs. Because these programs vary significantly by county and state, your Cason loan officer will need to run a search based on your specific location and income level to see which grants or forgivable second mortgages you might qualify for.
Can I get pre-approved by Cason before I find a house? Absolutely, and in 2026, this is highly recommended. Cason offers a robust pre-approval process that goes beyond a simple "pre-qualification." A Cason pre-approval usually involves a preliminary review of your credit and income documents, giving you a "Verified Approval" letter that carries significantly more weight with sellers and real estate agents.
What happens if my appraisal comes in lower than the purchase price? If the appraisal is low, Cason’s team will work with you and your real estate agent to explore options. This may include requesting a "Reconsideration of Value" if there are better comparable sales available, or restructuring the loan (such as increasing your down payment or asking the seller to drop the price). Having a local lender who understands regional property values is a major advantage in these scenarios.
Practical Recommendation
If you are a homebuyer who values clear communication, predictability, and expert guidance, Cason Home Loans is one of the best choices available in 2026. They are particularly well-suited for first-time buyers who need their hands held through the process, as well as move-up buyers who are dealing with the complexities of selling and buying simultaneously.
To get started, your next step should be to request a formal Loan Estimate from a Cason loan officer. Compare this estimate—specifically the "Box A" origination charges and the interest rate—against one national bank and one online-only lender. This "rule of three" comparison will confirm if Cason’s service-oriented model also aligns with your financial goals for your 2026 home purchase.