Arizona group auto insurance is a specialized benefit program where employers, credit unions, or professional associations partner with carriers to provide discounted car insurance to their members. In 2026, these programs offer Arizona residents a way to leverage collective buying power, typically resulting in premiums 5% to 15% lower than individual retail policies, often coupled with the convenience of automated payroll deductions.
Understanding Group Auto Insurance in the Arizona Market
Group auto insurance, often referred to as "voluntary benefits" or "worksite marketing" in the insurance industry, functions differently than the standard individual policies most drivers procure. In Arizona, these plans are not "true group" insurance in the way health insurance is (where one master policy covers everyone with identical rates); instead, they are mass-marketed individual policies. Each member receives their own policy and is rated based on their specific risk profile, but they benefit from a "group deviation"—a pre-approved discount filed by the insurer with the Arizona Department of Insurance and Financial Institutions (DIFI).
As we navigate 2026, the Arizona insurance landscape has become increasingly sophisticated. High population growth in the Phoenix-Mesa-Chandler metro area has led to increased traffic density, which traditionally drives up individual premiums. Group insurance serves as a critical buffer against these rising costs. By grouping thousands of employees or members together, insurers see a lower "acquisition cost" (the marketing expense to get a new customer), and they pass those savings directly to the policyholders in the form of lower base rates.
Eligibility and Prerequisites for Arizona Group Plans
To access group auto insurance in Arizona, an individual must typically belong to a qualifying organization. These organizations act as the "sponsor" for the plan. The eligibility requirements are generally straightforward but vary depending on the nature of the group.
Employer-Sponsored Groups
The most common way to access these rates is through an employer. Many of Arizona’s largest employers, including technology firms in the "Silicon Desert," healthcare systems, and government agencies, offer group auto insurance as part of their voluntary benefits package. To be eligible, you usually need to be a full-time or permanent part-time employee. In 2026, many companies have extended these benefits to 1099 contractors if they have long-term service agreements, reflecting the evolving nature of the Arizona workforce.
Professional and Alumni Associations
If your employer does not offer a group plan, you may find eligibility through professional organizations. Groups such as the Arizona Education Association (AEA), state bar associations, or medical societies often provide access to group-rated insurance. Furthermore, alumni associations for the University of Arizona, Arizona State University, and Northern Arizona University frequently have partnerships with major carriers that provide "alumni discounts" which function similarly to group rates.
Credit Unions and Labor Unions
Arizona has a robust network of credit unions and labor unions (such as those representing first responders or construction trades). These entities often negotiate specific group rates for their members. Unlike employer-sponsored plans, these memberships are often "portable," meaning if you change jobs but remain a member of the credit union, you can typically keep your group-discounted insurance policy.
Arizona Minimum Coverage Requirements in 2026
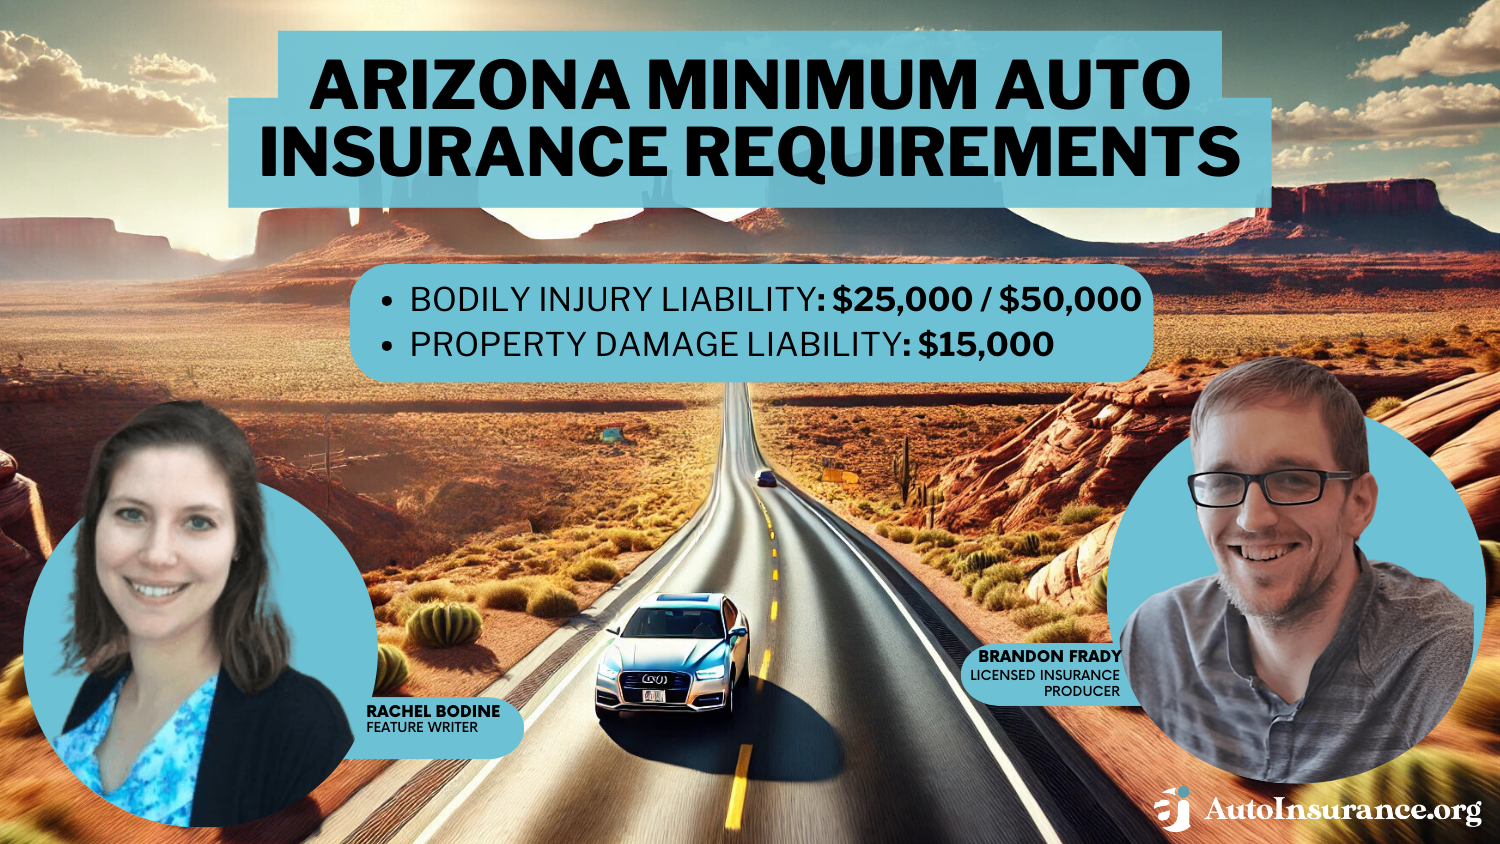
Regardless of whether you purchase insurance through a group or individually, every driver in Arizona must adhere to state-mandated minimum liability limits. As of 2026, these requirements remain consistent with the most recent legislative updates designed to protect drivers against the rising costs of medical care and vehicle repairs.
When enrolling in a group plan, it is vital to ensure your coverage meets or exceeds these Arizona standards:
- Bodily Injury Liability: $25,000 per person and $50,000 per accident. This covers medical expenses, lost wages, and legal fees for other parties if you are at fault in an accident.
- Property Damage Liability: $15,000 per accident. This covers repairs to the other driver’s vehicle or damage to structures (like fences or buildings).
- Uninsured/Underinsured Motorist (UM/UIM): While not strictly mandatory to carry, Arizona law requires insurers to offer it in writing. Given that Arizona historically has a higher-than-average rate of uninsured drivers, most group plans strongly recommend or automatically include these coverages unless specifically waived.
In 2026, experts generally advise that the state minimums are insufficient for most drivers. Group plans often make it more affordable to "buy up" to higher limits, such as 100/300/100, which provides a much more robust financial safety net in high-traffic areas like Scottsdale or Tucson.
Key Benefits of Group Auto Insurance for Arizona Drivers
The primary draw of group auto insurance is financial, but the advantages extend into administrative ease and unique policy features that are rarely available on the open market.
Significant Cost Savings
The "group deviation" discount is the cornerstone of these policies. Because the insurer is gaining access to a large pool of potential customers without expensive advertising campaigns, they can lower the premium. In Arizona, where the heat can lead to increased vehicle wear and unique road hazards (such as monsoons and dust storms), any reduction in the base premium is a significant advantage.
Payroll Deduction and Flexible Budgeting
For employer-sponsored plans, the ability to pay premiums via payroll deduction is a major convenience. This ensures that payments are never missed, eliminating the risk of policy lapses. Many Arizona employers also allow these deductions to be taken out of each paycheck (bi-weekly or weekly), which helps employees manage their cash flow better than a large monthly or semi-annual lump sum payment.
Simplified Underwriting
While group auto insurance in Arizona is still underwritten (meaning they check your driving record), the "appetite" of the insurer for a group is often broader than for an individual. Some group plans offer "guaranteed issue" periods during initial enrollment or "relaxed underwriting" for members who have been with the organization for a certain amount of time. This can be a lifeline for drivers who might struggle to find affordable rates on the individual market due to minor past infractions.
Portability and Continuity
A common concern is what happens if you leave the group. Most Arizona group auto policies are "portable." If you leave your employer, you can usually keep the policy, although you may lose the specific group discount or the payroll deduction option. This prevents a "gap" in insurance coverage, which is a factor that Arizona insurers use to determine future rates.
Comparing Group vs. Individual Insurance: A 2026 Analysis
It is a common misconception that a group rate is always the lowest rate. Because Arizona uses a "file and use" system for insurance rates, individual carriers are constantly adjusting their prices based on real-time data.
| Feature | Group Auto Insurance | Individual Auto Insurance |
|---|---|---|
| Pricing Basis | Pre-negotiated group deviation/discount. | Standard retail rates based on individual risk. |
| Payment Options | Payroll deduction, EFT, or direct bill. | EFT, credit card, or direct bill. |
| Eligibility | Must be a member of a specific organization. | Open to the general public. |
| Underwriting | Often simplified or more inclusive. | Standard underwriting (strict adherence to tiers). |
| Convenience | Integrated into employee benefit portals. | Managed independently by the policyholder. |
| Customization | Standardized packages with optional riders. | Highly customizable from the ground up. |
| Rate Stability | Rates often remain stable for the group year. | Rates can fluctuate at each 6-month renewal. |
Factors Influencing Group Rates in Arizona
Even within a group plan, your individual premium will be influenced by several factors specific to the Arizona environment. Insurers in 2026 use highly granular data to determine risk.
- Garaging Location: A driver in a rural area like Cochise County will likely pay less than a driver in a high-theft or high-traffic ZIP code in Phoenix or Glendale. Group plans still account for where the vehicle is parked overnight.
- Daily Commute: With the rise of hybrid work in Arizona, many group plans now offer "low-mileage" discounts. If you work from home three days a week and only commute to an office in Tempe twice a week, your group rate will reflect that lower risk.
- Vehicle Type: Arizona's rugged terrain often leads residents to purchase SUVs and trucks. While these are durable, they can be more expensive to insure than sedans due to their higher repair costs and potential for causing more damage in an accident.
- Telematics Integration: By 2026, almost all Arizona group insurance providers have integrated telematics (tracking driving behavior via a smartphone app or plug-in device). Members who opt into these programs can often stack a "safe driver" discount on top of their "group" discount.
How to Implement or Enroll in a Group Plan
For HR Managers and Business Owners
If you are an employer looking to add group auto insurance to your benefits package, the process involves partnering with a voluntary benefits broker or a direct carrier. In Arizona, you must ensure the carrier is licensed by DIFI. You will need to provide anonymized census data (number of employees, general locations) so the carrier can calculate the potential group discount. There is typically no cost to the employer to offer this; the primary "cost" is the administrative setup for payroll deduction.
For Employees and Members
To enroll, you should first check your organization’s benefits portal or contact your HR representative. Most Arizona group plans have a dedicated landing page where you can enter your information and receive an instant quote. You will need:
- Your current policy's "Declarations Page" to compare coverages.
- The Vehicle Identification Number (VIN) for all cars.
- Driver’s license numbers for all household members.
- An estimate of your annual mileage.
Common Pitfalls to Avoid
While group auto insurance is generally a positive, there are specific mistakes Arizona residents should avoid.
Assuming it's always the cheapest option: If you have a flawless driving record, a high credit score, and qualify for multiple niche discounts (like a "home/auto bundle" with an individual carrier), that individual rate might still beat the group rate. Always get a quote from your group plan, but compare it against one or two individual carriers.
Ignoring the "Bundle" Factor: Many group plans only offer auto insurance. If you own a home in a high-value area like Paradise Valley, the discount you get by bundling your home and auto with an individual carrier might outweigh the group discount on auto alone.
Neglecting to Update Information: In the heat of Arizona, many people move frequently or change vehicles. Failing to update your "garaging address" with your group provider can lead to claim denials if an accident occurs at a location not listed on the policy.
The Role of Technology in 2026 Arizona Group Insurance
In 2026, technology has fundamentally changed how group insurance is serviced. AI-driven chatbots now handle most of the initial quoting process for Arizona groups, allowing members to get coverage in minutes. Furthermore, "active claim monitoring" is now common. If a monsoon-related hail storm hits a specific part of Mesa, group insurers can proactively reach out to members in that ZIP code to initiate claims, providing a level of service that was previously reserved for high-net-worth individual policies.
Frequently Asked Questions
Can my spouse or children be covered under my Arizona group auto policy?
Yes. Group auto insurance policies in Arizona generally allow you to include household members on the policy. As long as the primary policyholder meets the eligibility requirements of the group (e.g., being an employee), the spouse and any resident children can be listed as covered drivers. The group discount applies to the entire policy, not just the primary member's portion.
What happens to my group insurance if I am laid off or retire?
If you leave your group due to retirement or a layoff, you can usually transition the policy to an individual account. This is known as "portability." While you may lose the specific group discount and the ability to pay via payroll deduction, the carrier will typically allow you to maintain the coverage at their standard retail rates. It is important to notify the carrier immediately to set up a new payment method and avoid a lapse in coverage.
Does a group policy in Arizona cover "Gap Insurance" for new car loans?
Many group auto insurance providers in 2026 offer Gap Insurance as an optional endorsement. Given that Arizona has a high volume of new vehicle sales, this is a popular addition. It covers the "gap" between what you owe on your car loan and the actual cash value of the car if it is totaled. Group plans often offer this at a lower rate than what a dealership would charge at the time of purchase.
If the group has a high number of accidents, will my individual rate go up?
Generally, no. In Arizona, group auto insurance is "experience rated" at the individual level, not the group level. While the "group discount" itself might be adjusted by the carrier during the annual contract renewal with your employer, your specific premium increases are typically tied to your own driving record, your location, and statewide rate adjustments approved by the DIFI, rather than the driving habits of your coworkers.
Are there specific discounts for hybrid or electric vehicles in Arizona group plans?
Yes. By 2026, nearly all major Arizona group insurance carriers offer "Green Vehicle" discounts. With the proliferation of EVs in urban centers like Phoenix and the expansion of charging infrastructure across the state, insurers incentivize the use of these vehicles. These discounts can often be "stacked" on top of the base group discount.
Final Recommendation for Arizona Residents
If you have access to a group auto insurance plan through your employer or an association in Arizona, your first step should be to request a quote. The potential for double-digit savings and the ease of payroll deduction makes it a formidable option in the 2026 insurance market. However, do not assume the group rate is the absolute floor. Use the group quote as a benchmark, then spend 15 minutes getting a quote from a traditional carrier that allows you to bundle home or renters insurance. This ensures you are maximizing your savings while maintaining the robust coverage necessary for Arizona's unique driving conditions.