Aion life insurance provides comprehensive financial protection through digital-first term life and credit life policies. Primarily integrated with Aion Bank’s ecosystem, these products offer streamlined application processes, flexible coverage amounts, and debt-protection features designed to safeguard beneficiaries from the financial impact of the policyholder’s death or disability.
Understanding the Aion Life Insurance Model
Aion’s approach to life insurance is rooted in the "bancassurance" model, where banking institutions partner with established insurance underwriters to provide seamless financial services. In the context of Aion, the insurance products are typically managed through a partnership with NN Insurance Services Belgium, an entity of the NN Group. This allows Aion to leverage its high-tech mobile interface while providing the financial security of a legacy insurance provider.
As of 2026, the Aion ecosystem has transitioned into a fully mature digital landscape where insurance is no longer a separate, paperwork-heavy product but a modular component of a user’s broader financial health. The platform targets a digitally native audience that prioritizes speed and transparency. Unlike traditional life insurance models that may require weeks of medical exams and agent consultations, Aion utilizes digital health questionnaires and algorithmic underwriting to provide immediate or near-immediate coverage decisions.
This overview focuses on the two primary pillars of Aion’s life insurance suite: Protect Your Life (standard term life insurance) and Protect Your Loan (credit life insurance). While both fall under the "Aion Life" umbrella, they serve distinct financial purposes and cater to different risk profiles.
Detailed Breakdown of Aion Life Insurance Products
Protect Your Life (Term Life Insurance)
Protect Your Life is a pure term life insurance product. Its primary objective is to pay out a predefined capital sum to designated beneficiaries in the event of the insured person's death. This capital is intended to replace lost income, cover funeral expenses, or provide a long-term inheritance for family members.
The policy is flexible, allowing users to select a coverage amount that aligns with their current lifestyle and future obligations. In 2026, the digital interface allows for "dynamic sum adjustment," where policyholders can request increases or decreases in the insured capital as their family situation changes (e.g., the birth of a child or the completion of a major financial milestone).
Protect Your Loan (Credit Life Insurance)
Protect Your Loan is a specialized form of life insurance often referred to as mortgage protection or credit life insurance. It is specifically designed to cover outstanding debt. If the policyholder passes away before a personal loan or mortgage is repaid, the insurance provider pays the remaining balance directly to the lender (Aion Bank or a partner institution).
This product is crucial for individuals who do not want to leave their heirs with significant debt. The premium for "Protect Your Loan" is often calculated based on the decreasing balance of the loan, meaning as the debt is paid down, the amount of coverage needed (and sometimes the cost) adjusts accordingly.
Eligibility and Enrollment Prerequisites
To access Aion life insurance products in 2026, applicants must meet several baseline criteria. Because Aion operates primarily as a digital bank within the European Economic Area (EEA), the eligibility requirements are strictly enforced through the app’s KYC (Know Your Customer) protocols.
- Residency: Applicants must generally be legal residents of the country where the Aion service is officially registered (typically Belgium or Poland).
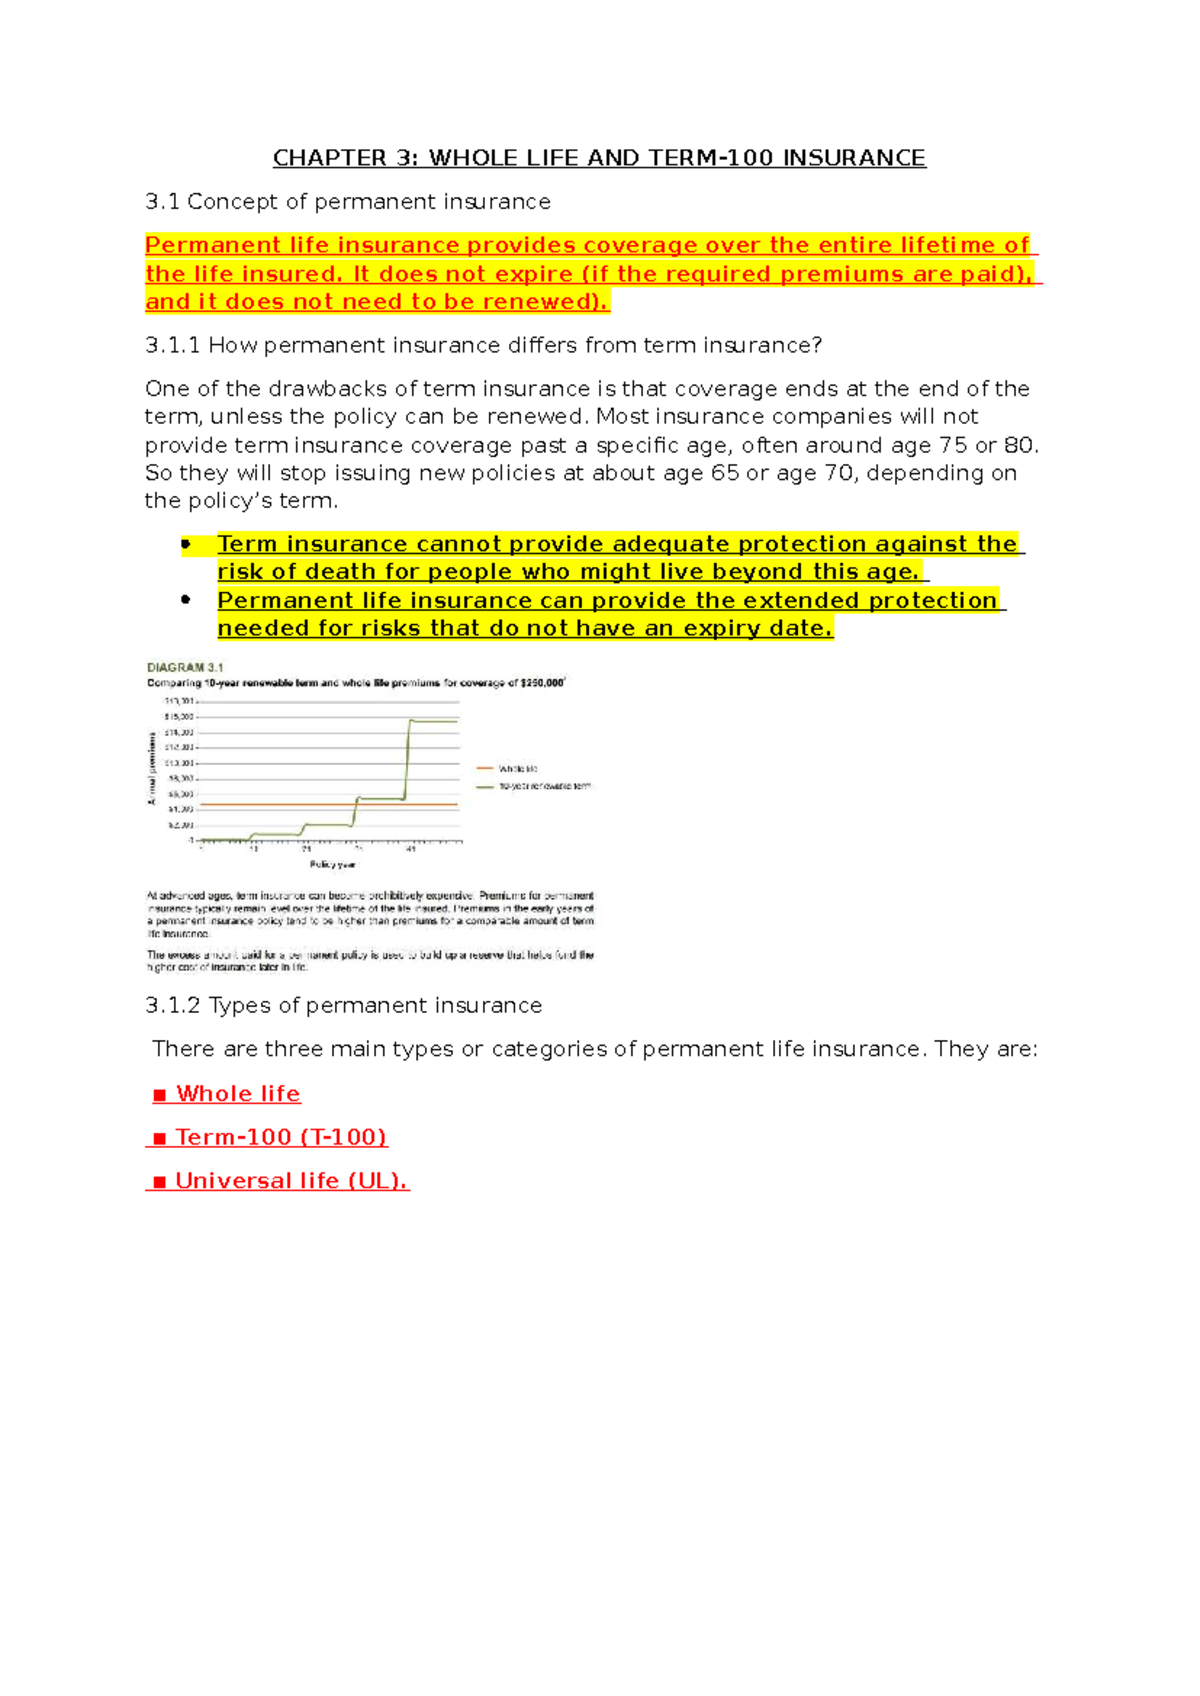
- Age Limits: Coverage is usually available to individuals between the ages of 18 and 64. It is important to note that most policies expire once the insured reaches age 65 or 70, depending on the specific terms of the underwriter.
- Aion Bank Membership: In most cases, having an active Aion Bank account (either a Premium or Light membership) is a prerequisite for accessing the insurance portal within the mobile application.
- Health Status: While many policies do not require a physical medical exam, applicants must complete a digital health declaration. This includes questions regarding chronic illnesses, tobacco use, and surgical history.
The Digital Underwriting Process in 2026
The hallmark of Aion life insurance is the speed of its underwriting. Traditional life insurance often involves "manual underwriting," where a human officer reviews medical records. Aion employs automated underwriting engines that analyze the data provided during the application process against actuarial tables in real-time.
For the majority of healthy applicants, this results in an "instant issue" policy. This means that from the moment the digital health questionnaire is submitted, the policy can be active within minutes. However, if the algorithm flags certain risk factors—such as high-risk hobbies (paragliding, scuba diving) or pre-existing conditions—the application may be moved to a manual review tier. In 2026, even these manual reviews are significantly faster than historical standards, often completed within 48 to 72 hours via secure digital document uploads.
Premium Structures and Cost Considerations
The cost of Aion life insurance is not static; it is highly personalized based on the risk profile of the applicant. Understanding how these premiums are calculated is essential for long-term financial planning.
Factors Influencing Premiums
- Age: As with all life insurance, younger applicants enjoy significantly lower premiums.
- Sum Assured: The higher the payout amount, the higher the monthly or annual premium.
- Smoking Status: Smoker rates remain substantially higher than non-smoker rates due to the statistical increase in mortality risk.
- Duration of Coverage: For term life policies, the length of the "term" (e.g., 10, 20, or 30 years) dictates the risk spread.
Aion typically uses a fixed premium model for the duration of the term, meaning once you are locked in at a certain rate, your monthly payment will not increase even as you age, provided the coverage amount remains the same.
Comparison Table: Aion Life Insurance vs. Traditional Brokerages
| Feature | Aion (Digital Bancassurance) | Traditional Insurance Broker |
|---|---|---|
| Application Time | 5–15 Minutes | 2–4 Weeks |
| Medical Exam | Digital Declaration (Standard) | Often Required (Physical) |
| Management | Mobile App / Self-Service | Agent / Paper-based |
| Flexibility | High (Instant adjustments) | Moderate (Requires endorsements) |
| Product Range | Streamlined (Term/Credit) | Diverse (Whole, Universal, etc.) |
| Cost Transparency | Instant Quote in App | Quote provided after consultation |
Claims Management and Beneficiary Payouts
One of the most sensitive aspects of life insurance is the claims process. In 2026, Aion has simplified the notification of "death events" through a dedicated beneficiary portal.
When a policyholder passes away, the beneficiary (who should be informed of the policy's existence and the location of the digital "Policy Key") initiates the claim. The process involves:
- Notification: Submitting a digital claim form via the Aion interface or the underwriter’s (NN Insurance) portal.
- Documentation: Uploading a certified copy of the death certificate and a medical certificate stating the cause of death.
- Verification: The underwriter verifies the claim against policy exclusions.
- Disbursement: Once approved, funds are typically transferred via SEPA (Single Euro Payments Area) instant credit to the beneficiary’s bank account.
It is important to note that Aion’s involvement is primarily as the distributor and platform provider. The actual payment of the claim is guaranteed by the underwriter, such as NN Insurance Services Belgium, which is regulated by the National Bank of Belgium and the Financial Services and Markets Authority (FSMA).
Critical Exclusions and Policy Limitations
No life insurance overview is complete without an analysis of what is not covered. Aion life insurance policies contain standard industry exclusions that policyholders must review to avoid a claim denial.
- Suicide Clause: Most policies will not pay out if the insured commits suicide within the first two years (24 months) of the policy's effective date.
- Illegal Acts: If death occurs during the commission of a crime or as a result of participation in a riot, the claim may be voided.
- War and Terrorism: While some modern policies have evolved, many still exclude deaths resulting from active participation in war or acts of terrorism, though passive victims are often covered.
- Misrepresentation: If the digital health questionnaire was answered dishonestly (e.g., hiding a known heart condition), the underwriter has the right to refuse the payout and cancel the policy retroactively.
- High-Risk Activities: Unless specifically disclosed and a higher premium paid, deaths resulting from professional sports or extreme hobbies may be excluded.
Practical Recommendations for Applicants
For those considering Aion life insurance in 2026, the following steps ensure the best coverage experience:
- Audit Your Debt: Before selecting a sum, calculate your total outstanding liabilities (mortgages, car loans, credit cards). Your "Protect Your Loan" policy should, at a minimum, match this total.
- Income Replacement Calculation: For "Protect Your Life," a common rule of thumb is to insure for 7 to 10 times your annual salary.
- Review Beneficiary Designations: Ensure your beneficiaries are correctly named in the app. Life events like marriage or divorce do not automatically update your insurance policy.
- Be Transparent on Health: Given the algorithmic nature of Aion’s underwriting, discrepancies between your declaration and medical records (which may be accessed during a claim) can lead to total claim denial.
- Check for Overlap: If you have life insurance through your employer (Group Life), determine if Aion is a necessary supplement or a redundant cost.
Frequently Asked Questions
Is Aion life insurance available to non-EU residents?
Generally, no. Aion Bank and its insurance partners operate under EEA regulations. Applicants typically must be tax residents of Belgium, Poland, or other specific jurisdictions where Aion is authorized to provide financial services. In 2026, check the "Eligibility" section of the Aion app for the most current list of supported countries.
Can I cancel my Aion life insurance policy at any time?
Yes, term life and credit life policies through Aion are usually flexible. You can terminate the contract through the app. However, keep in mind that "Protect Your Loan" may be a requirement of your loan agreement; canceling it without a replacement could put you in breach of your loan terms. There is usually a "cooling-off" period (often 30 days) after the initial purchase where you can cancel and receive a full refund of any premiums paid.
What happens to my insurance if I close my Aion Bank account?
Because the insurance is a contract between you and the underwriter (e.g., NN Insurance), the coverage might technically continue, but managing it becomes significantly more difficult. In many cases, the "Aion" version of these products is contingent on an active membership. If you plan to close your bank account, you must contact the insurance provider directly to arrange for an alternative payment method and management portal.
Does Aion life insurance cover disability or critical illness?
Aion's primary products focus on "Death" and "Total and Permanent Disability" (TPD). While some variants of "Protect Your Loan" include coverage for involuntary unemployment or temporary disability, these are often optional add-ons rather than standard features of the core life insurance product. Always review the "Special Conditions" document in your Aion app for specific illness coverage.
How are premiums paid?
Premiums are automatically deducted from your Aion Bank current account on a monthly or annual basis. This ensures that the policy remains active without the risk of missed manual payments. If the account has insufficient funds, the insurer typically provides a grace period (often 15 to 30 days) before the policy lapses.