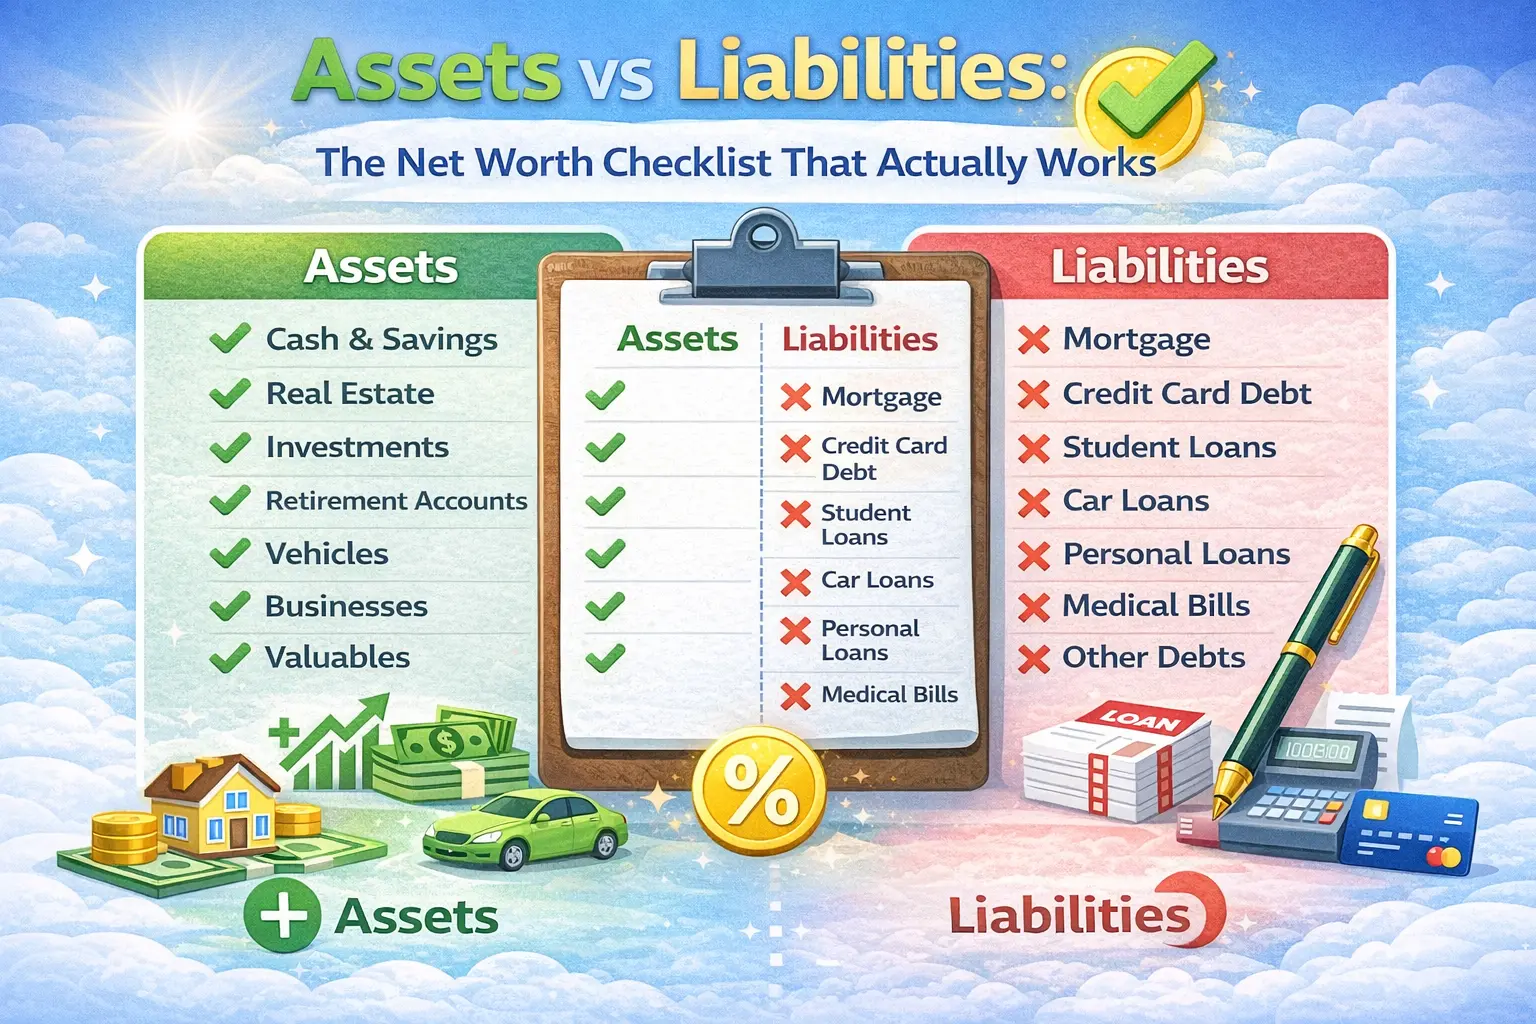
The accounting equation, where assets equal the sum of liabilities and net worth, is the foundational principle of all modern financial reporting. This balance ensures that every resource owned by an individual or business (assets) is financed either by borrowing money (liabilities) or by the owner's own funds (net worth).
Understanding the Fundamental Accounting Equation
In the world of finance and accounting, the equation Assets = Liabilities + Net Worth (also known as Owner's Equity) is much more than a mathematical curiosity; it is a structural necessity. This formula represents the double-entry bookkeeping system, which dictates that every financial transaction has an equal and opposite effect in at least two different accounts.
As we navigate the economic landscape of 2026, the complexity of our financial tools has grown—ranging from digital currencies to fractional real estate ownership—yet this core equation remains the unchanging bedrock of fiscal health. To understand how this works in practice, we must first define the three components with precision.
Defining Assets: What You Own
Assets are resources with economic value that an individual, corporation, or country owns or controls with the expectation that it will provide a future benefit. In 2026, assets are generally categorized into two groups:
- Current Assets: These include cash, cash equivalents, accounts receivable, and inventory—items expected to be converted into cash within one year.
- Non-Current (Fixed) Assets: These are long-term investments, such as real estate, machinery, intellectual property, and even long-term digital asset holdings.
The value of an asset is not just its purchase price but its current market value or its depreciated book value, depending on the accounting standard being applied, such as the Financial Accounting Standards Board (FASB) guidelines.
Defining Liabilities: What You Owe
Liabilities are obligations or debts owed to external parties. They represent a claim against your assets by creditors. Just like assets, they are categorized by their timeframe:
- Current Liabilities: Debts due within a year, such as credit card balances, utility bills, or short-term business loans.
- Long-term Liabilities: Obligations that extend beyond twelve months, such as mortgages, student loans, or corporate bonds.
In a healthy financial scenario, liabilities are used strategically to acquire assets that appreciate in value or generate income, such as a low-interest mortgage for a home.
Defining Net Worth: Your True Financial Stake
Net worth, often referred to as equity in a business context, is the residual interest in the assets after deducting liabilities. It is essentially what would be left over if you sold all your assets and paid off all your debts.
- For an individual, net worth is a primary measure of wealth.
- For a business, it represents the owner’s or shareholders' investment plus any retained earnings (profits not distributed as dividends).
The goal of financial planning is almost always to increase net worth over time by either increasing asset value or decreasing liabilities.
The Mechanics of Balance: Double-Entry Bookkeeping
The reason assets always equal liabilities plus net worth is due to the "dual aspect concept." Every time a transaction occurs, the equation must remain in balance. If you increase an asset, you must either decrease another asset, increase a liability, or increase your net worth.
For example, if you receive a $5,000 windfall and put it in the bank, your assets (Cash) increase by $5,000. To balance this, your net worth also increases by $5,000. If you instead used that $5,000 to pay off a credit card, your assets would decrease by $5,000, but your liabilities would also decrease by $5,000, keeping the equation perfectly balanced. This constant equilibrium provides a "check and balance" system that prevents accounting errors and provides a clear snapshot of financial standing at any given moment.
Example 1: Launching a New Business Venture
Imagine an entrepreneur, Sarah, decides to open a boutique digital marketing agency in early 2026. To get the business off the ground, she needs initial capital to cover software licenses, hardware, and office space.
The Transaction:
- Sarah invests $20,000 of her personal savings into the business bank account.
- She takes out a small business loan of $10,000 from a local credit union to purchase high-end server equipment.
The Accounting Breakdown:
- Assets: Sarah’s business now has $20,000 in cash plus $10,000 worth of equipment. Total Assets = $30,000.
- Liabilities: The business owes the credit union for the loan. Total Liabilities = $10,000.
- Net Worth (Equity): Sarah’s personal contribution represents her stake in the company. Total Net Worth = $20,000.
The Equation in Action: $30,000 (Assets) = $10,000 (Liabilities) + $20,000 (Net Worth)
In this example, we see how the total resources controlled by the business ($30,000) are perfectly accounted for by the sources of those resources: $10,000 from a creditor and $20,000 from the owner. If Sarah’s agency generates a profit of $5,000 in its first month and she keeps that money in the business, her assets (Cash) would rise to $35,000, and her net worth (Retained Earnings) would rise to $25,000. The equation remains balanced.
Example 2: Financing a Residential Real Estate Purchase
Buying a home is the most common way individuals interact with the accounting equation. It provides a clear illustration of how a large asset is often "shared" between the owner (Net Worth) and a lender (Liability).
The Transaction: An individual, James, purchases a condominium for $450,000 in 2026.
- He provides a down payment of $90,000 (20%).
- He secures a mortgage for the remaining $360,000.
The Accounting Breakdown:
- Assets: The primary asset is the real estate itself, valued at the purchase price. Total Assets = $450,000.
- Liabilities: The mortgage represents a legal obligation to the bank. Total Liabilities = $360,000.
- Net Worth: This is James’s "equity" in the home. Total Net Worth = $90,000.
The Equation in Action: $450,000 (Assets) = $360,000 (Liabilities) + $90,000 (Net Worth)
As James makes monthly mortgage payments, the composition of the right side of the equation changes. Each payment consists of interest (an expense) and principal. The principal portion reduces the liability. As the liability decreases, the net worth (equity) increases by the same amount, assuming the asset's value stays the same. If the property value appreciates to $500,000 by 2027, James's assets increase by $50,000, and because his debt hasn't increased, his net worth jumps to $140,000 ($90,000 original equity + $50,000 appreciation).
Example 3: The Purchase of a Depreciating Asset (Automobile)
Not all assets maintain or increase in value. Understanding how the equation handles depreciating assets, like a vehicle, is crucial for realistic financial tracking.
The Transaction: A consumer, Maria, buys a new electric vehicle (EV) for $60,000.
- She pays $10,000 in cash.
- She finances the remaining $50,000 through an auto loan.
The Initial Accounting Breakdown:
- Assets: The vehicle is valued at $60,000. Total Assets = $60,000.
- Liabilities: The auto loan is the debt. Total Liabilities = $50,000.
- Net Worth: Maria’s initial stake is her down payment. Total Net Worth = $10,000.
The Initial Equation: $60,000 (Assets) = $50,000 (Liabilities) + $10,000 (Net Worth)
The One-Year Adjustment (Depreciation): Fast forward one year to 2027. The car has depreciated by $12,000 and is now worth $48,000. Maria has also paid off $5,000 of the loan principal.
- New Asset Value: $48,000.
- New Liability Value: $45,000.
- New Net Worth: $3,000.
The Adjusted Equation: $48,000 (Assets) = $45,000 (Liabilities) + $3,000 (Net Worth)
This example highlights a critical financial lesson: if an asset depreciates faster than the liability is paid off, net worth can become negative (often called being "underwater" on a loan). This is why tracking the balance between assets and liabilities is vital for long-term solvency.
Comparative Analysis of Asset-Liability Scenarios
The following table compares the three examples discussed above to show how different financial moves impact the components of the accounting equation.
| Scenario | Primary Asset | Initial Asset Value | Initial Liability | Initial Net Worth | Impact Over Time |
|---|---|---|---|---|---|
| Business Startup | Cash & Equipment | $30,000 | $10,000 (Loan) | $20,000 | Growth via profit increases Net Worth. |
| Home Purchase | Real Estate | $450,000 | $360,000 (Mortgage) | $90,000 | Appreciation & principal payments increase Net Worth. |
| EV Purchase | Vehicle | $60,000 | $50,000 (Loan) | $10,000 | Depreciation decreases Net Worth quickly. |
Common Misconceptions and Troubleshooting the Balance Sheet
One of the most frequent errors in personal finance is confusing "income" with "assets." While high income can lead to higher assets, the accounting equation is a "point-in-time" snapshot, not a flow of money over time.
Misconception: High Assets Equal High Wealth
An individual might own a $2 million home (Asset), but if they have a $1.9 million mortgage (Liability), their net worth is only $100,000. Someone with a $500,000 home and no mortgage is technically "wealthier" in terms of net worth. Always look at the liability side of the equation before judging a financial position.
Misconception: "Paper Wealth" is Guaranteed
As seen in Example 3, asset values fluctuate. In 2026, with the volatility of various markets, it is essential to use realistic, current market valuations for assets. Using a purchase price for an asset that has since lost value will result in an artificially inflated net worth, leading to poor financial decision-making.
Troubleshooting an Out-of-Balance Equation
If your assets do not equal the sum of your liabilities and net worth, there is usually one of three errors:
- Omission: You forgot to record a transaction (e.g., you spent cash but didn't record the decrease in assets).
- Duplication: You recorded a transaction twice on one side but not the other.
- Classification Error: You recorded a liability as a net worth entry (e.g., treating a loan from a family member as a gift).
Why This Equation Matters in 2026
In 2026, the integration of automated accounting software and AI-driven personal finance apps has made tracking this equation easier than ever. Most modern banking interfaces now provide a "Real-Time Net Worth" dashboard. However, the software is only as good as the data provided.
Understanding the why behind the numbers allows you to:
- Assess Risk: High liabilities relative to assets increase financial vulnerability during economic downturns.
- Plan for Retirement: Retirement planning is essentially the process of growing the "Net Worth" side of the equation until it can support your lifestyle without active income.
- Optimize Taxes: In many jurisdictions, interest on certain liabilities (like business loans or some mortgages) may be tax-deductible, which indirectly impacts net worth by reducing expenses.
For a deeper dive into official reporting standards for larger entities, the Securities and Exchange Commission (SEC) provides extensive resources on how public companies must balance their books.
FAQs
What happens to the equation if I spend $1,000 on a vacation?
When you spend money on a service or an experience that has no resale value (like a vacation), your assets (Cash) decrease by $1,000. Since you haven't taken on a new debt and you haven't acquired a physical asset, your net worth must decrease by $1,000 to keep the equation balanced. In accounting terms, this is an expense that reduces retained earnings.
Can net worth be a negative number?
Yes. If your total liabilities exceed your total assets, you have a negative net worth, often referred to as being "insolvent" or "underwater." This frequently happens to recent graduates with significant student loan debt or homeowners during a real estate market crash. The goal of a debt repayment plan is to move the net worth back into positive territory.
Is my salary considered an asset?
No, salary is considered income. Income is a flow of money that eventually increases your assets (when you get paid cash) and subsequently your net worth. On a balance sheet, only the cash you currently hold from that salary is counted as an asset.
How do digital assets like Bitcoin fit into this equation?
Digital assets are treated as intangible assets or investments on a balance sheet. Their value is recorded at current market rates in 2026. If the value of your Bitcoin increases, your total assets increase, and consequently, your net worth increases, provided you have not taken on debt to purchase it.
Why do banks care about my net worth?
Banks use your net worth to determine your "creditworthiness." A high net worth relative to the loan amount you are requesting suggests that you have the resources to repay the debt even if your primary income source is interrupted. It serves as a safety buffer for the lender.
Practical Recommendation: Your Next Action
To apply these concepts immediately, perform a "Financial Snapshot" for the current month of 2026. List every asset you own (bank accounts, investments, home value, car value) and every debt you owe (credit cards, student loans, mortgages).
Subtract your total liabilities from your total assets. If the resulting net worth is lower than you expected, focus your strategy on either debt acceleration (reducing liabilities) or asset acquisition (increasing holdings). Reviewing this equation once a quarter is the most effective way to ensure long-term financial stability and growth.