AIG Direct’s Return of Premium (ROP) term life insurance provides a death benefit for a specified period, typically 20 or 30 years, with a distinctive financial guarantee: if the policyholder outlives the term, the insurance company refunds 100% of the base premiums paid into the policy. This hybrid product functions as both a risk-management tool and a long-term capital preservation vehicle for qualifying individuals.
The AIG Direct brand, which operates under the umbrella of Corebridge Financial (formerly AIG Life & Retirement), continues to offer these specialized policies in 2026 to address a common consumer objection to term insurance—the idea of "wasting" money on premiums if the death benefit is never triggered. By combining the high coverage amounts of term life with a money-back feature, ROP policies serve as a middle ground between low-cost level term insurance and expensive permanent life insurance.
Understanding the Return of Premium (ROP) Mechanism
The fundamental appeal of the AIG Direct ROP policy is the survival benefit. Standard term life insurance is "pure" protection; if the policy expires while the insured is still living, the contract simply ends, and no value is returned. In contrast, an ROP policy includes an endowment-like feature.
How the Refund is Calculated
When an ROP policy reaches the end of its level-premium term (e.g., at the end of year 30), the insurer tallies the "base premiums" paid over the life of the policy. This refund typically excludes:
- Extra charges for "substandard" health ratings (table ratings).
- Fees for certain optional riders, such as the Waiver of Premium or Accidental Death Benefit.
- Policy fees and interest.
The result is a lump-sum check sent to the policy owner. Because this money is technically a return of the "cost basis" (the money you already paid in), the Internal Revenue Service (IRS) generally treats this refund as tax-free. However, it is essential to consult a tax professional regarding specific state-level nuances or changes in tax code as of 2026.
The Trade-off: Higher Premiums
The primary cost of the ROP feature is a significantly higher monthly or annual premium compared to a standard term policy. The insurance company essentially takes the extra premium and invests it. The returns on those investments fund the eventual refund of the premiums. In 2026, with shifting interest rate environments, the price gap between standard term and ROP term remains a critical factor for applicants to evaluate.
Core Features of AIG Direct ROP Policies
AIG Direct (Corebridge Financial) structures its ROP products to provide flexibility while maintaining the simplicity of term insurance. The policies are typically issued through American General Life Insurance Company (AGL) or The United States Life Insurance Company in the City of New York (US Life).
Available Term Lengths
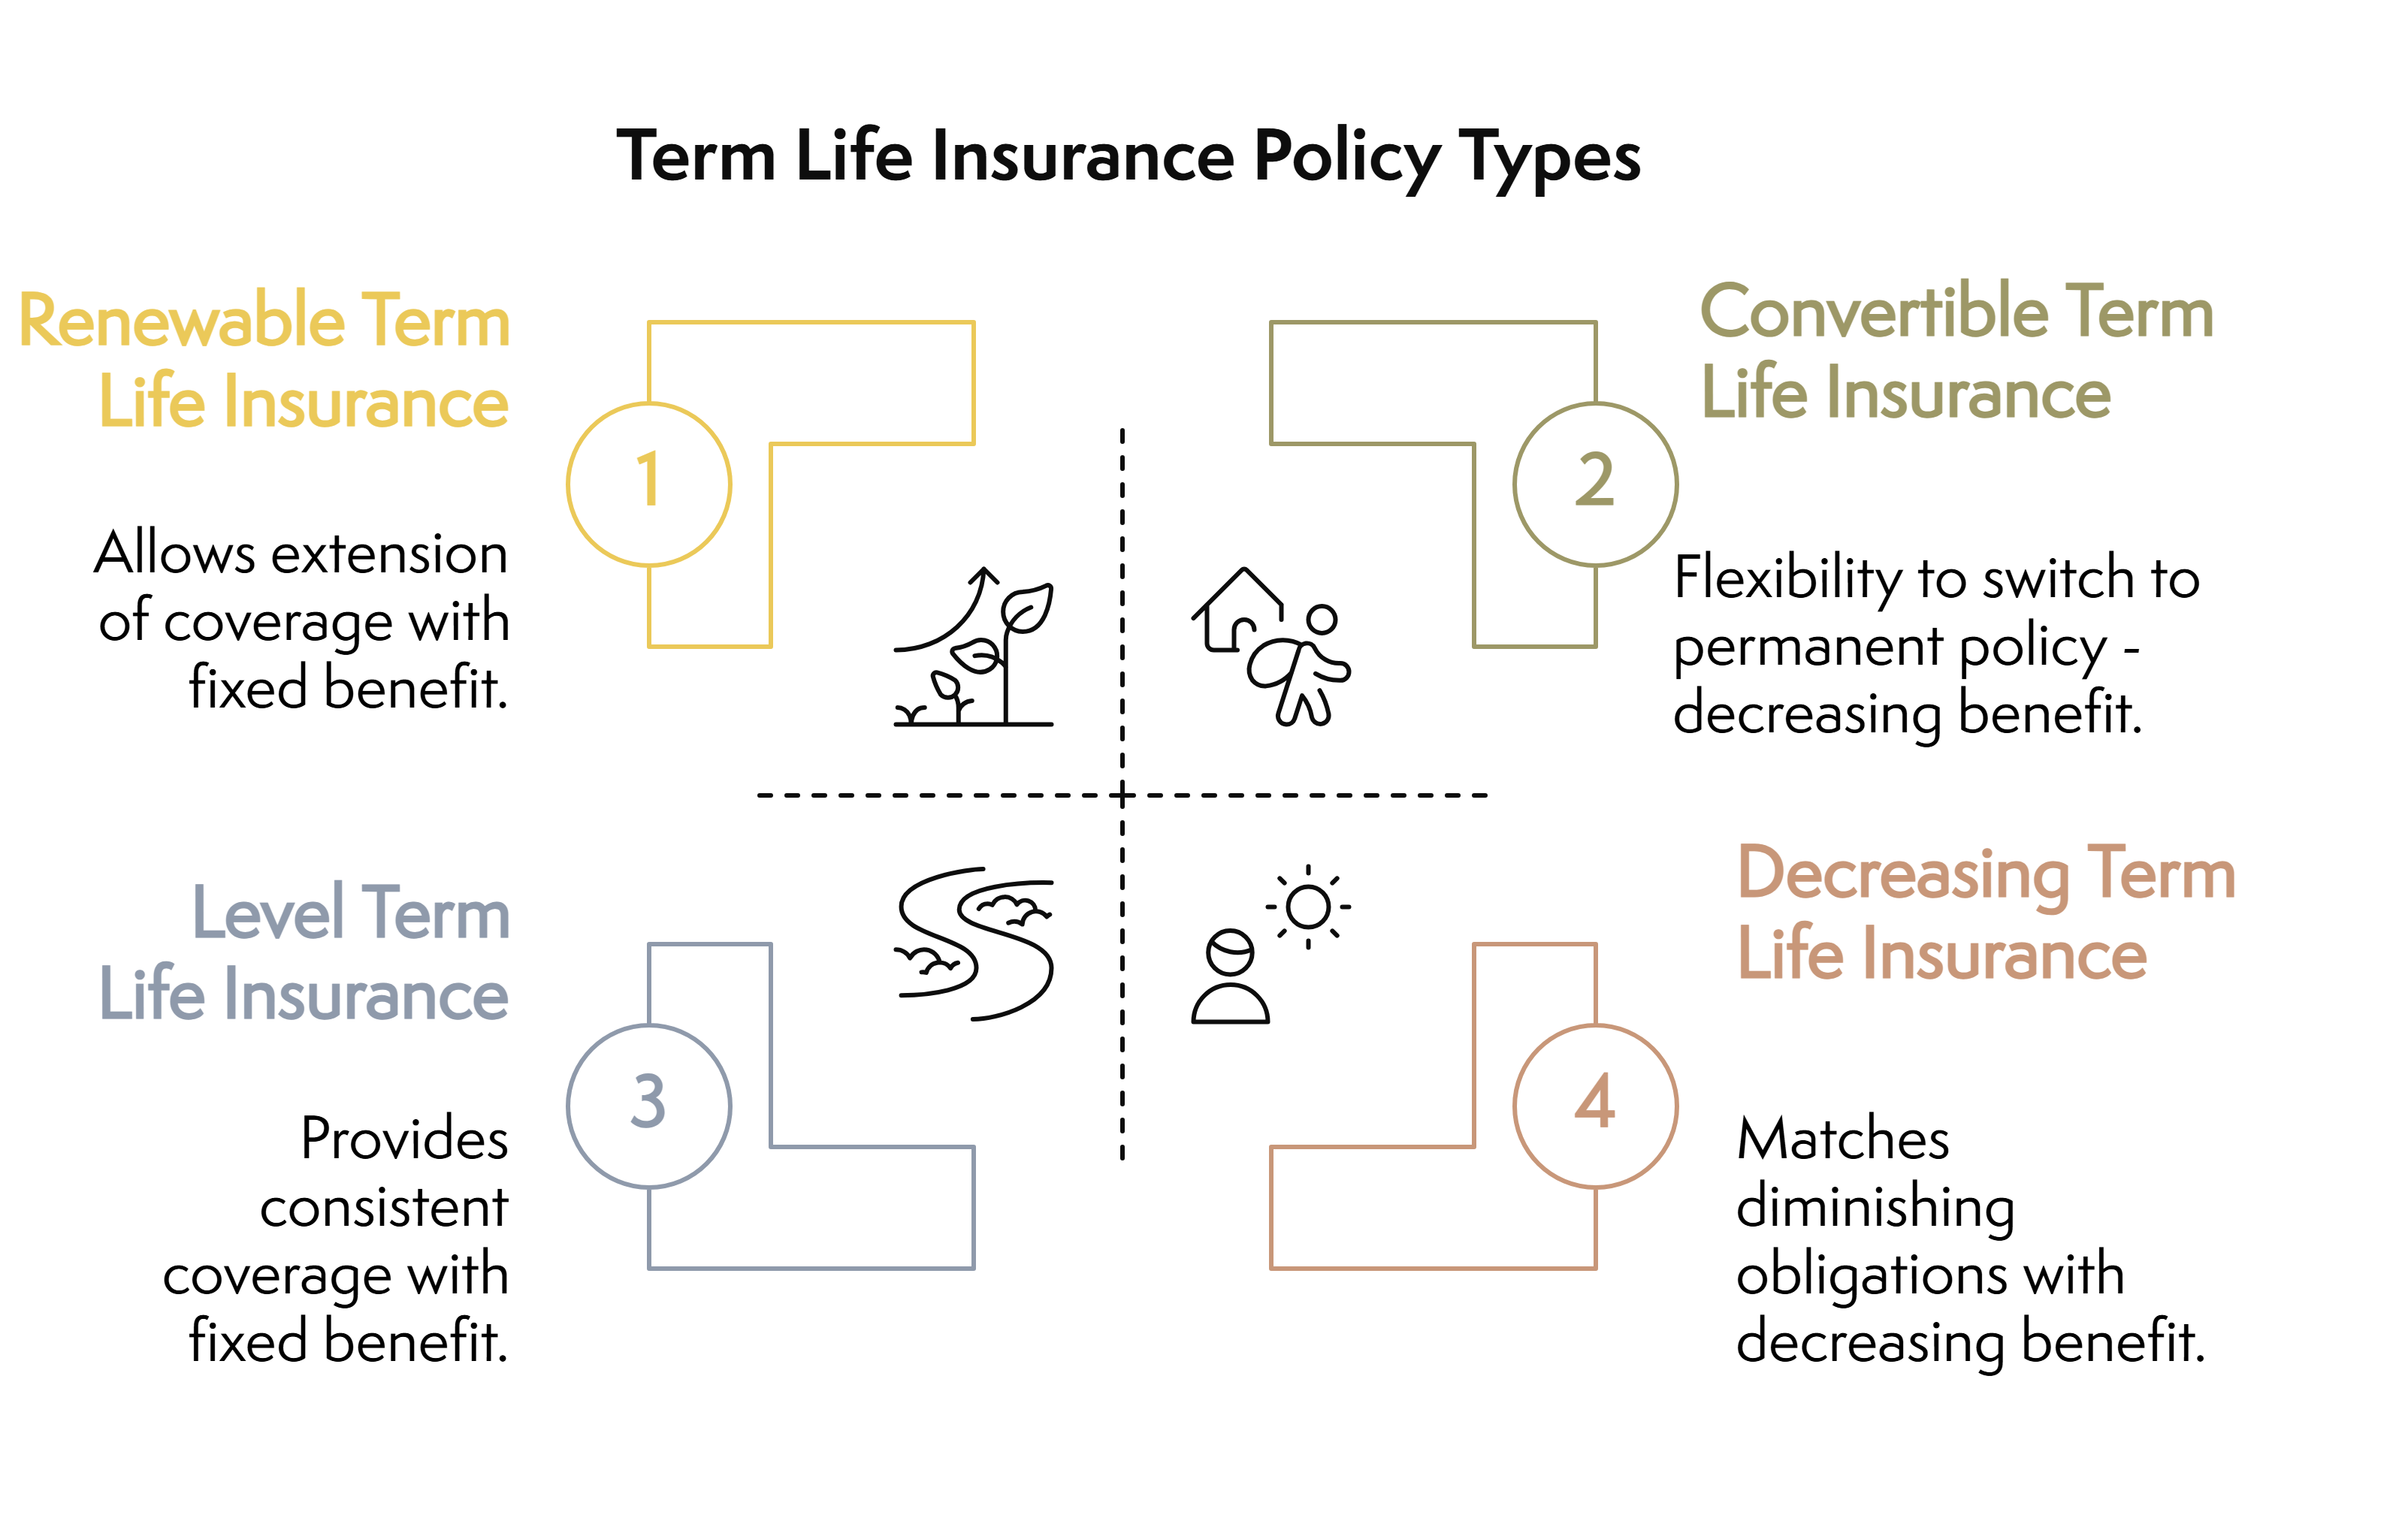
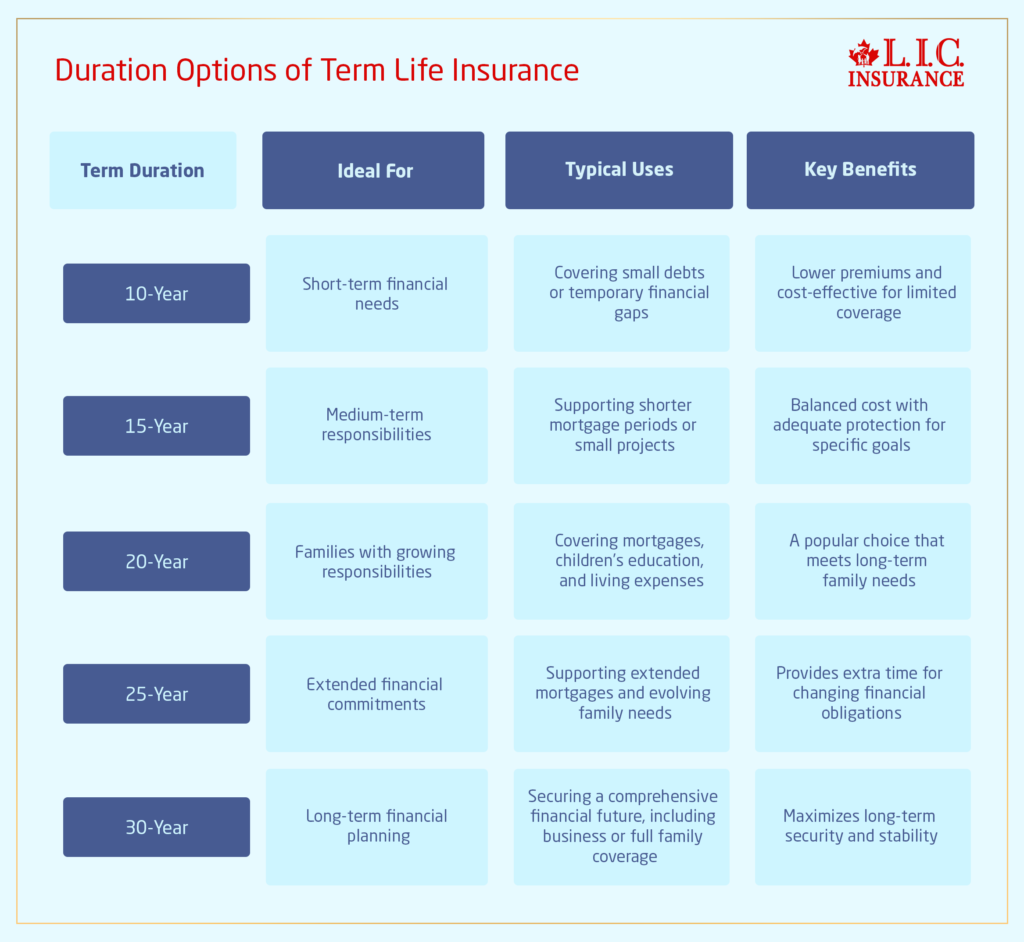
In 2026, AIG Direct primarily focuses on two term lengths for ROP products:
- 20-Year Term: Ideal for parents with young children or those mid-career who want protection until retirement.
- 30-Year Term: Often selected by younger adults or new homeowners to cover the duration of a standard mortgage while ensuring a significant "windfall" of returned premiums in their 50s or 60s.
Unlike standard term insurance, which may offer 10, 15, 25, or 35-year options, the ROP feature is usually restricted to longer durations to allow the insurer enough time to grow the capital necessary to fulfill the refund promise.
Coverage Limits and Eligibility
AIG Direct typically offers ROP coverage starting at $100,000, extending into the millions for high-net-worth individuals. Eligibility is determined by age and health:
- Issue Ages: Generally available to individuals between 18 and 50 (for 30-year terms) or up to age 60 (for 20-year terms).
- Underwriting: Applicants undergo a medical underwriting process. While "no-medical-exam" options may be available for lower face amounts or younger ages, the ROP feature often necessitates a full clinical review to ensure the long-term viability of the contract.
Advanced Policy Options and Riders
Beyond the basic death benefit and premium refund, AIG Direct ROP policies offer several "riders"—optional add-ons that customize the coverage. These riders can be critical for tailoring the policy to specific life risks.
Terminal Illness Rider (Accelerated Death Benefit)
Most AIG Direct policies include an Accelerated Death Benefit (ADB) at no or low additional cost. This allows the policyholder to access a portion of the death benefit (often up to 50% or matching a specific dollar cap) if they are diagnosed with a terminal illness with a life expectancy of 12 to 24 months. This money can be used for medical bills, hospice care, or any other final expenses.
Waiver of Premium Rider
If the insured becomes totally disabled and unable to work for a period (usually six months or longer), this rider ensures the policy remains in force without further premium payments. In the context of an ROP policy, it is important to clarify with the agent whether the "waived" premiums are still included in the final refund. Typically, only premiums actually paid out-of-pocket are returned, though some contracts may differ.
Accidental Death Benefit Rider
This provides an additional payout if the insured dies as a result of a covered accident. For example, if a policy has a $500,000 base benefit and a $250,000 Accidental Death rider, the total payout would be $750,000 in the event of a fatal car crash. This does not usually increase the amount of premium returned at the end of the term.
Child Insurance Rider
This allows the policyholder to add a small amount of term coverage for their children under the parent’s primary policy. It is a cost-effective way to ensure funeral expenses and provide a future insurability option for the child.
Comparison: ROP vs. Standard Term Life Insurance
To decide if the AIG Direct ROP policy is appropriate, it is helpful to compare it against a standard "guaranteed level term" policy.
| Feature | Standard Term Insurance | ROP Term Insurance |
|---|---|---|
| Death Benefit | Same (Guaranteed) | Same (Guaranteed) |
| Premium Cost | Lower (Pure Protection) | Higher (Includes Savings Element) |
| Cash Value | None | None (Refund only at term end) |
| End of Term Status | Policy expires; no money returned | Policy expires; 100% base premiums returned |
| Early Cancellation | No value returned | Limited or no refund (usually) |
| Tax Treatment | Death benefit generally tax-free | Death benefit and refund generally tax-free |
| Best For | Maximum coverage for lowest price | Those who want a "forced savings" mechanism |
Strategic Considerations and Performance in 2026
When evaluating AIG Direct’s ROP options in 2026, consumers must look beyond the "free insurance" marketing. While the refund makes the insurance feel "free" in retrospect, there are opportunity costs and technical limitations to consider.
The Opportunity Cost Analysis
The premium for an ROP policy might be 2 to 3 times higher than a standard term policy. For instance, if a standard term policy costs $50 per month and an ROP policy costs $130, the policyholder is essentially paying an extra $80 per month for the ROP feature.
- The ROP Perspective: After 30 years, you receive roughly $46,800 back (total premiums paid).
- The Investment Perspective: If you had bought the $50 policy and invested the $80 difference in a diversified index fund with a 7% average annual return, you might have over $90,000 after 30 years.
However, the ROP refund is guaranteed (subject to the claims-paying ability of the insurer), whereas market investments are not. For conservative individuals who struggle with consistent saving, the ROP policy acts as a "forced savings" vehicle.
Early Surrender Risks
A common mistake with ROP policies is canceling the policy early. Most AIG Direct ROP contracts do not offer a pro-rated refund if the policy is surrendered in the first few years. Some may offer a partial, graded return of premium after year 10, but the full 100% refund is almost always contingent on keeping the policy in force for the entire 20 or 30-year term. If your financial situation changes and you can no longer afford the higher ROP premiums, you may lose the "return" feature entirely.
Conversion Privileges
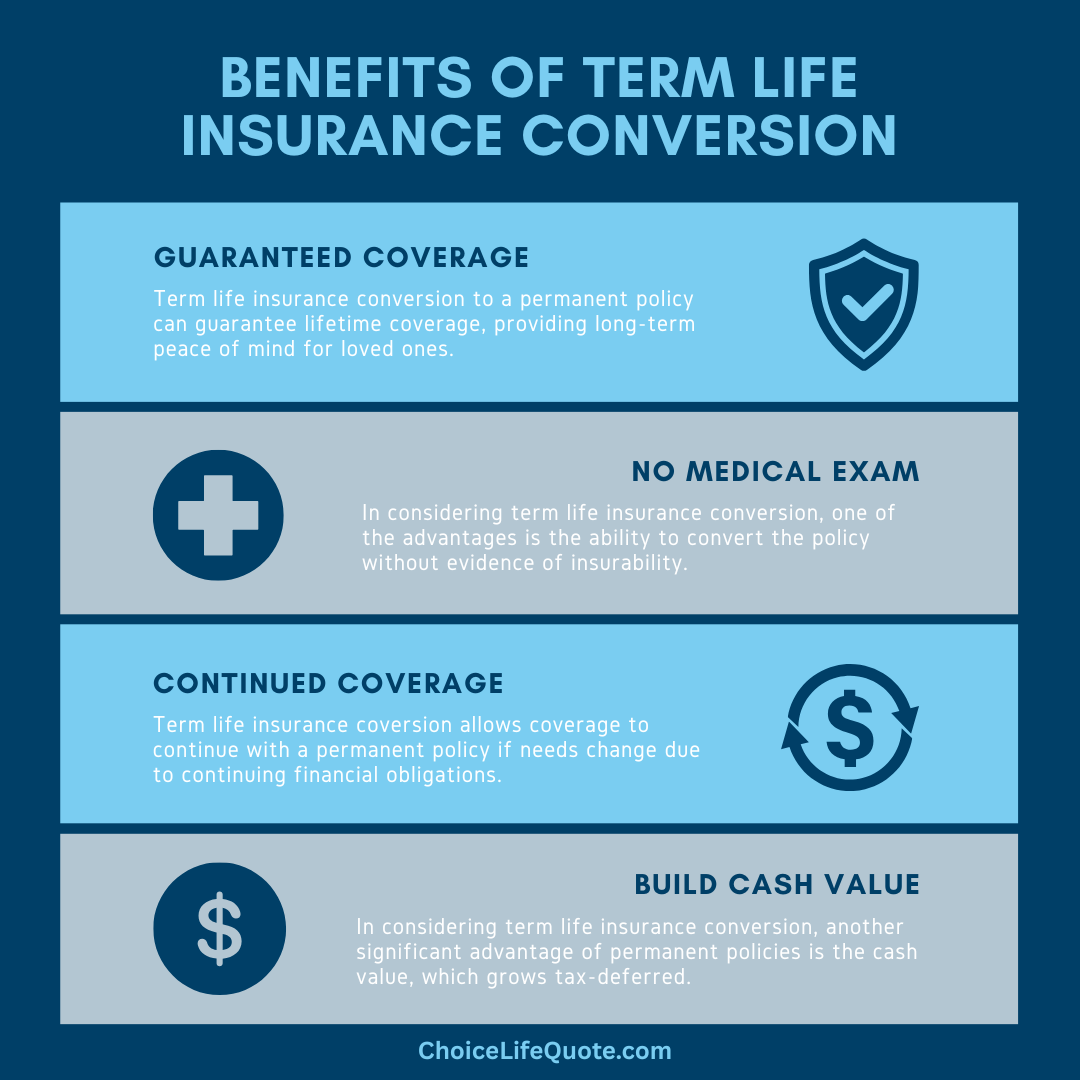
A valuable feature often included in AIG Direct ROP policies is the Conversion Option. This allows the policyholder to convert the term policy into a permanent life insurance policy (like Whole Life or Universal Life) without undergoing a new medical exam. This is a critical safety net if the insured develops a chronic health condition during the term and needs to maintain coverage indefinitely.
The Claims-Paying Ability of Corebridge Financial (AIG)
As of 2026, Corebridge Financial remains one of the largest providers of life insurance and retirement solutions in the United States. When purchasing an ROP policy, the strength of the insurer is paramount because you are trusting them to hold your money for 20 to 30 years.
Independent rating agencies provide a window into this stability:
- A.M. Best: Generally assigns "A" (Excellent) or higher ratings to the American General Life entities.
- Standard & Poor’s (S&P): Typically maintains strong investment-grade ratings.
- Fitch Ratings: Historically views the Corebridge/AIG entities as having a high capacity to meet financial commitments.
Prospective policyholders should verify the latest ratings via the National Association of Insurance Commissioners (NAIC) to ensure the company’s financial health remains robust.
Common Mistakes to Avoid
- Over-Estimating Affordability: Do not commit to an ROP premium that stretches your budget. If you lapse the policy, the "savings" component is often lost.
- Ignoring the "Base Premium" Definition: Ensure you understand that riders like the Accidental Death Benefit are often not refundable. Read the "exclusions" section of the policy illustration carefully.
- Forgetting the End Date: The refund is not automatic the second the clock strikes midnight on year 30. There is usually a short administrative process to claim the refund, though AIG Direct is known for proactive communication regarding maturing policies.
- Neglecting Inflation: $50,000 returned in 2056 (30 years from 2026) will have significantly less purchasing power than $50,000 today. ROP provides a nominal return of capital, not an inflation-adjusted return.
Frequently Asked Questions
Is the AIG Direct ROP refund taxable?
In the vast majority of cases, no. The IRS views the return of premiums as a return of the money you already paid into the contract (your cost basis). Since you are not receiving a "gain" or interest on that money, it is not considered taxable income. However, if the policy were structured in a way that paid out more than the total premiums paid, that excess would be taxable.
What happens if I die during the term of an ROP policy?
If the insured dies during the term, the beneficiaries receive the full death benefit (face amount). However, the premiums paid up to that point are generally not returned in addition to the death benefit. The ROP feature is a survival benefit, not an additional death benefit.
Can I change my ROP policy to a standard term policy later?
While you can usually cancel an ROP policy and apply for a new standard term policy, you cannot simply "switch" and get your extra premiums back. Starting a new policy would require new underwriting based on your current age and health, which would likely result in higher rates for the standard term portion than if you had bought it initially.
Does AIG Direct offer ROP for 10-year terms?
Generally, no. As of 2026, the 10-year term is usually reserved for standard level term insurance. The math required to fund a 100% refund of premiums over only 10 years would make the premiums prohibitively expensive for most consumers.
What if I want to cancel my policy in year 15 of a 30-year term?
Depending on the specific policy language in your AIG Direct contract, you might receive a partial refund. Many ROP policies have a "schedule of surrender values" that shows a graded percentage of premium return after a certain number of years. However, this is significantly less than the 100% offered at the end of the full term.
Practical Recommendation
If you are a disciplined investor who can reliably contribute to a brokerage account, a standard level term policy paired with independent investing (the "buy term and invest the difference" strategy) will likely result in higher net wealth after 20 or 30 years.
However, if you view life insurance premiums as a "lost expense" and prefer a guaranteed, tax-free lump sum at the end of your coverage period, the AIG Direct ROP Term Life Insurance policy is a viable financial tool. It is specifically recommended for:
- Homeowners who want their premiums back to pay off the remaining mortgage balance at the end of 30 years.
- Parents who want to use the refund to assist with adult children's major life events or their own retirement transition.
- Conservative individuals who prioritize the return of capital over market-based growth.
Before signing, request a full policy illustration from an AIG Direct agent. This document will detail the exact premium amounts, the projected refund value, and the specific riders included in your quote.