Earning an annual income of $13,500 places an individual significantly below the federal poverty guidelines for a single-person household in the United States, meaning that accumulating a substantial net worth on this exact figure requires navigating tight margins, leveraging public assistance, minimizing fixed expenses, and utilizing alternative wealth-building vehicles. When examining net worth under these financial constraints, understanding the fundamental difference between gross income, net income, assets, and liabilities becomes essential for realistic long-term planning.
Defining 13 50 Annually in Personal Finance
To evaluate what a 13 50 annually income means for a person's net worth, one must first break down the figures on both a monthly and weekly basis. An annual gross income of $13,500 translates to:
- Monthly Gross Income: $1,125
- Bi-weekly Gross Income: $519.23
- Weekly Gross Income: $259.62
- Hourly Equivalent (assuming 40 hours per week, 52 weeks a year): Approximately $6.49 per hour
Because the federal minimum wage in the United States has remained at $7.25 per hour since 2009—though many state and local jurisdictions have set higher minimum wage floors—an income of $13,500 annually often reflects part-time employment, seasonal work, gig economy tasks, or underemployment.
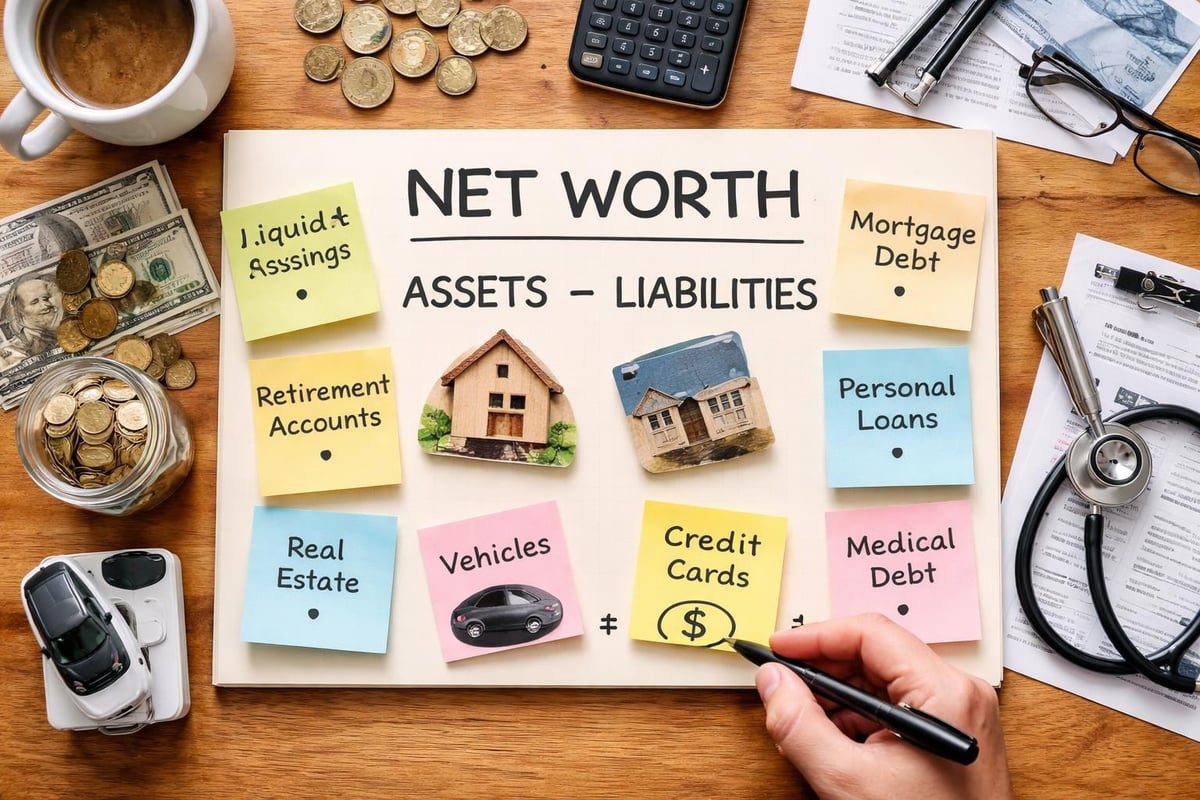
In financial literacy, income is the stream of money flowing inward, whereas net worth is the stock of wealth accumulated over time. Net worth is calculated using a straightforward formula:
$$\text{Net Worth} = \text{Total Assets} - \text{Total Liabilities}$$
Assets include cash savings, vehicle equity, investments, and personal property, while liabilities encompass credit card debt, student loans, medical bills, and personal loans. For individuals earning $13,500 annually, building positive net worth hinges entirely on controlling liabilities and capitalizing on modest asset-building opportunities, as disposable income for high-yield investments is inherently limited.
The Mechanics of Income Versus Net Worth
A common misconception in personal finance is that high income automatically equates to high net worth, or conversely, that a low income precludes any accumulation of wealth. While a higher income provides a wider margin for error and greater capacity to save, net worth is fundamentally driven by the savings rate and expense management.
The Role of Savings Rate on Low Incomes
When an individual earns $13,500 per year, traditional financial advice recommending a 15% to 20% retirement savings rate can be mathematically challenging due to basic survival costs such as food, shelter, and utilities. However, even small adjustments yield measurable changes in net worth over a multi-year horizon:
- Emergency Fund Allocation: Directing even $20 per month into a high-yield savings account creates a $240 annual increase in liquid cash assets.
- Debt Elimination: Diverting discretionary spending toward paying down high-interest credit card debt removes liabilities that erode net worth via compounding interest.
- Asset Preservation: Avoiding consumer loans prevents the accumulation of negative equity, keeping liabilities at or near zero.
Gross Versus Net Income Realities
Depending on tax filing status and standard deductions, an annual income of $13,500 may result in a federal income tax liability of zero or result in a tax refund through programs like the Earned Income Tax Credit (EITC). Understanding tax credits and deductions is vital for individuals at this income level, as tax refunds can temporarily spike liquid net worth and serve as seed capital for emergency funds or essential vehicle repairs.
Cost of Living and Budgetary Constraints at $13,500
Managing a budget on $13,500 annually requires strict allocation strategies. According to consumer expenditure data from the Bureau of Labor Statistics, housing and food consume the vast majority of low-income household budgets, frequently leaving little to no room for discretionary spending.
Housing Strategies
With a monthly gross income of $1,125, finding conventional market-rate housing independently is exceedingly difficult in most metropolitan areas. Consequently, individuals operating at this income level often rely on:
- Subsidized housing programs or Section 8 housing vouchers (subject to local waitlists and eligibility requirements).
- Roommates or multi-generational living arrangements to split utility and rent expenses.
- Rural or low-cost-of-living regions where housing costs scale down proportionally.
Food and Healthcare Support
To preserve cash flow and protect net worth from catastrophic medical debt or food insecurity, utilization of public safety net programs is common:
- SNAP (Supplemental Nutrition Assistance Program): Provides monthly benefits for eligible low-income households to purchase food.
- Medicaid: Offers free or low-cost health coverage, mitigating out-of-pocket medical expenses that are a primary driver of personal bankruptcy and negative net worth.
Comparative Wealth Scenarios at $13,500 Annually
To illustrate how net worth can vary drastically even when individuals earn the exact same annual income, consider three distinct financial profiles.
| Financial Profile | Total Assets | Total Liabilities | Resulting Net Worth | Primary Wealth Driver / Constraint |
|---|---|---|---|---|
| Profile A: Debt-Free Saver | $3,500 (Savings & reliable used car) | $0 | +$3,500 | Lives with family; aggressively saves cash; avoids all consumer debt. |
| Profile B: Break-Even | $500 (Checking account balance) | $500 (Credit card balance) | $0 | Balances everyday survival expenses with revolving credit; net zero asset accumulation. |
| Profile C: Debt-Burdened | $1,000 (Personal belongings) | $6,000 (Medical & credit debt) | -$5,000 | Facing emergency medical expenses and high-interest unsecured debt without safety nets. |
As demonstrated in the comparison table, net worth is not solely a reflection of earnings, but rather the cumulative net result of past financial decisions, debt management, and access to support systems.
Practical Steps to Improve Net Worth on a Low Income
For individuals earning 13 50 annually, accelerating net worth growth requires a dual focus on increasing earning potential and meticulously managing existing resources.
1. Focus on Skill Development and Income Growth
While budgeting is necessary, the mathematical ceiling of saving on $13,500 a year is restrictive. Exploring workforce development programs, vocational training, or adult education funded through state grants or non-profit organizations can bridge the gap toward higher-paying employment.
2. Protect Liquid Assets
Avoid predatory financial products such as payday loans, title loans, and high-interest installment loans. These products feature annualized percentage rates (APRs) that can exceed 300%, rapidly destroying net worth by compounding liabilities far beyond the borrower's capacity to repay.
3. Leverage Free Financial Counseling
Non-profit credit counseling agencies, such as those affiliated with the National Foundation for Credit Counseling (NFCC), offer free or low-cost budgeting assistance and debt management plans. Utilizing these resources helps structure debt repayment without incurring additional fees.
Frequently Asked Questions
Is $13,500 a year considered living below the poverty line?
Yes. For a single-person household in the contiguous United States, the federal poverty guidelines established by the Department of Health and Human Services (HHS) place the threshold significantly higher than $13,500, meaning this income level qualifies individuals for various federal and state assistance programs.
Can someone with a $13,500 annual income ever achieve a positive net worth?
Yes. Net worth is determined by subtracting liabilities from assets. An individual who has zero debt and owns a used car worth $2,000 alongside $500 in savings has a positive net worth of $2,500, regardless of their annual income.
How does debt impact net worth at lower income levels?
Debt has an amplified negative impact at lower income levels because servicing interest payments consumes a larger percentage of monthly cash flow, leaving fewer resources available for emergency savings or asset accumulation.
Are taxes deducted from a $13,500 annual salary?
Federal income tax liability on a $13,500 gross income is typically minimal or zero for single filers after accounting for the standard deduction. Furthermore, eligible workers may qualify for refundable tax credits like the Earned Income Tax Credit, which can result in a tax refund rather than a tax bill.
What are the best ways to protect net worth against emergencies on a tight budget?
Enrolling in applicable public assistance programs (such as Medicaid and SNAP) helps insulate personal savings from being completely depleted by unexpected healthcare and nutritional expenses. Additionally, building even a modest cash cushion prevents reliance on high-interest credit cards during emergencies.
Conclusion and Next Actions
Evaluating a net worth scenario tied to 13 50 annually highlights the reality that wealth-building is relative to individual circumstances, expense structures, and debt management. While earning $13,500 per year presents strict budgetary challenges, maintaining zero debt, protecting liquid assets, and utilizing available public safety nets establish a stable foundation. The most productive next step for anyone navigating this income bracket is to conduct a detailed monthly expense audit, identify and eliminate any high-interest debt liabilities, and explore local workforce or educational programs designed to increase long-term earning potential.