IRS Table 1 provides the official monthly cost per $1,000 of group-term life insurance protection that employers must use to calculate the taxable income for employees receiving coverage in excess of $50,000. Under Internal Revenue Code Section 79, while the first $50,000 of employer-provided group-term life insurance is tax-free, the value of any coverage exceeding that threshold is considered imputed income and is subject to FICA and income tax withholding.
Understanding Group-Term Life Insurance and Section 79
Group-term life insurance is a common fringe benefit offered by employers to provide financial protection for workers' beneficiaries. Under Section 79 of the Internal Revenue Code, Congress granted a specific tax advantage to this type of benefit: employees can exclude the cost of up to $50,000 of group-term life insurance coverage from their gross income. This exclusion applies regardless of whether the employer pays the entire premium or the employee shares in the cost.
However, when an employer provides a policy with a death benefit greater than $50,000, the tax code treats the economic value of the excess coverage as taxable compensation. Because the actual cost of insurance increases with age, the IRS developed an official valuation table—commonly known as Table 1—to standardize how employers determine this imputed income. Imputed income represents the value of a non-cash fringe benefit that must be treated as wages for tax reporting purposes. It does not mean the employee receives extra cash in their paycheck; rather, it increases their taxable gross income on their Form W-2, resulting in a higher tax liability.
How IRS Table 1 Rates Work
IRS Table 1 assigns a specific monthly cost for every $1,000 of life insurance protection based on the employee's age at the end of the tax year. These rates are not based on the actual premiums paid by the employer to the insurance carrier, nor do they reflect individual underwriting factors like smoking status, gender, or health conditions. Instead, they are statutory rates set by the Department of the Treasury.
To calculate the imputed income, the employer determines the total coverage amount, subtracts the $50,000 statutory exclusion, divides the remaining excess coverage by 1,000, and multiplies that figure by the appropriate Table 1 rate corresponding to the employee's age bracket. This calculation is performed on a monthly basis or for the specific number of months the coverage was active during the calendar year.
The Official IRS Table 1 Rate Schedule
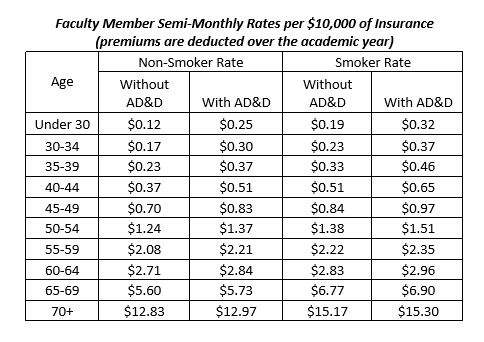
The table below outlines the current monthly cost per $1,000 of protection under IRS regulations. These rates are structured in five-year age increments, reflecting the increasing statistical probability of mortality as individuals age.
| Age Bracket | Monthly Cost per $1,000 of Protection |
|---|---|
| Under 30 | $0.08 |
| 30 to 34 | $0.09 |
| 35 to 39 | $0.11 |
| 40 to 44 | $0.10 |
| 45 to 49 | $0.15 |
| 50 to 54 | $0.23 |
| 55 to 59 | $0.43 |
| 60 to 64 | $0.66 |
| 65 to 69 | $1.27 |
| 70 and older | $2.06 |
Step-by-Step Calculation of Imputed Income
Calculating taxable group-term life insurance involves a straightforward formula. To illustrate how this process works in practice, consider a hypothetical employee and follow each step required to determine their annual reportable income.
Step 1: Determine Total Coverage and Excess Amount
Suppose an employee receives employer-provided group-term life insurance equal to two times their annual salary of $100,000, resulting in a total death benefit of $200,000. To find the taxable portion, subtract the $50,000 statutory exemption allowed under Section 79.
$$\text{Total Coverage } ($200,000) - \text{Exemption } ($50,000) = \text{Excess Coverage } ($150,000)$$
Step 2: Determine the Appropriate Monthly Rate
Identify the employee's age on the last day of the tax year. Assume the employee is 52 years old. Looking at the Table 1 schedule, the monthly cost for an individual in the 50 to 54 age bracket is $0.23 per $1,000 of protection.
Step 3: Calculate Monthly Imputed Income
Divide the excess coverage by 1,000, then multiply the result by the Table 1 monthly rate.
$$\frac{$150,000}{1,000} = 150 \text{ units}$$
$$150 \times $0.23 = $34.50 \text{ per month}$$
Step 4: Annualize the Figure
Multiply the monthly imputed income by 12 months to find the total amount that must be added to the employee's taxable wages for the year.
$$$34.50 \times 12 = $414.00$$
In this scenario, $414.00 is added to the employee's gross income on their Form W-2.
The Impact of Employee Contributions
Many group-term life insurance plans require employees to pay a portion of the premium for coverage that exceeds $50,000, or even for coverage below that threshold. The tax code provides relief for employees who make after-tax contributions toward their group-term life insurance.
If an employee pays any portion of the premium for the group-term life insurance out of pocket using after-tax dollars, the entire amount of that employee contribution reduces the taxable imputed income dollar-for-dollar. If the employee's after-tax contribution equals or exceeds the calculated Table 1 cost of the excess coverage, the imputed income drops to zero, meaning no additional taxable compensation is reported. However, pre-tax salary deductions do not provide this same offset for Table 1 calculations in the same manner. Employers must track these contributions carefully through payroll systems to ensure accurate reporting on Form W-2, typically reported in Box 12 with Code C.
Exemptions and Special Rules
While Section 79 applies broadly to employer-provided group-term life insurance, certain exceptions and specialized rules apply depending on the characteristics of the policy and the individuals covered.
Key Employee and Nondiscrimination Rules
Section 79 contains strict nondiscrimination rules to prevent plans from favoring key employees—such as officers, high earners, and certain majority owners—over rank-and-file workers. If a group-term life insurance plan is determined to be discriminatory, key employees lose the benefit of the $50,000 exclusion. Instead, taxable income for key employees is calculated using the higher of the actual cost of the insurance or the Table 1 rate, while non-key employees retain their tax-free threshold.
Retirees and Disabled Individuals
Special rules apply when group-term life insurance is provided to former employees. Generally, individuals who have terminated employment because of disability are exempt from the inclusion rules entirely, regardless of the coverage amount. For individuals who have retired, the statutory rules and Table 1 rates may apply differently depending on when the plan was established and whether grandfather provisions under historical tax law adjustments apply.
Permanent Benefits and Non-Qualifying Policies
Table 1 rates apply exclusively to term life insurance. If an employer-provided policy includes a permanent benefit—such as whole life insurance, cash value accumulation, or universal life insurance—the policy must be split into its term and permanent components. The permanent benefits are subject to entirely different taxation rules, and Table 1 cannot be used to value cash-value components. Furthermore, travel insurance and accident-only policies generally do not qualify as group-term life insurance under Section 79.
Employer Reporting and Payroll Responsibilities
Employers bear the legal responsibility for calculating, reporting, and withholding taxes on imputed income derived from excess group-term life insurance.
- Payroll Integration: Employers typically calculate imputed income on a payroll period, quarterly, or annual basis. Many payroll software systems automate this calculation once the employee's birthdate and coverage amounts are entered.
- Tax Withholding: Imputed income is subject to federal income tax withholding and FICA (Social Security and Medicare) taxes. It is generally exempt from FUTA (Federal Unemployment Tax Act) taxes. Because imputed income does not generate cash, employers deduct the employee's share of FICA and income taxes from their regular cash wages, which can result in a slightly lower net paycheck for the affected pay periods.
- Form W-2 Reporting: By January 31 of each year, employers must report the total imputed income for the previous calendar year on the employee's Form W-2. This amount is included in Box 1 (Wages, tips, other compensation), Box 3 (Social Security wages), and Box 5 (Medicare wages). Additionally, it is reported separately in Box 12 using Code C to designate taxable cost of group-term life insurance over $50,000.
Disclaimer: Tax laws and IRS regulations regarding fringe benefits are subject to change. Employers and employees should consult a qualified tax professional or certified public accountant to address specific financial situations and ensure compliance with current internal revenue guidelines.
Frequently Asked Questions
What happens if my employer provides more than $50,000 in life insurance?
The cost of coverage up to $50,000 is tax-free. For any amount exceeding $50,000, the IRS requires your employer to calculate a standardized value using Table 1 rates and add that amount to your taxable income. This increases your overall income tax and FICA withholding obligations, but it does not require you to pay cash directly to the insurance company.
Are Table 1 rates based on my actual health or smoking status?
No. IRS Table 1 rates are statutory figures based entirely on your age at the end of the calendar year. They do not factor in whether you smoke, your personal health history, or your gender. Every employee within the same five-year age bracket is assessed the exact same monthly cost per $1,000 of excess coverage.
Can I decline excess group-term life insurance to avoid the tax?
Plan design rules vary by employer. Some employer-sponsored plans allow employees to elect a lower coverage tier or waive coverage above $50,000 to avoid imputed income. However, many group plans are mandatory or provided as a flat multiple of salary without an opt-down provision. You should check with your employer's human resources or benefits department regarding plan flexibility.
How do after-tax premium contributions affect my taxable imputed income?
If you pay a portion of your group-term life insurance premiums using after-tax dollars, that contribution directly offsets the calculated Table 1 imputed income. If your after-tax contribution equals or exceeds the Table 1 value of the excess coverage, your reportable imputed income for that coverage is reduced to zero.
Do Table 1 rates apply to supplemental or voluntary life insurance?
It depends on how the supplemental plan is structured and paid for. If supplemental life insurance is part of an employer-provided group-term plan and exceeds $50,000 in total combined coverage, Table 1 rules apply. However, if you purchase an individual, portable policy entirely with your own after-tax dollars outside of a group plan, Section 79 and Table 1 do not apply.