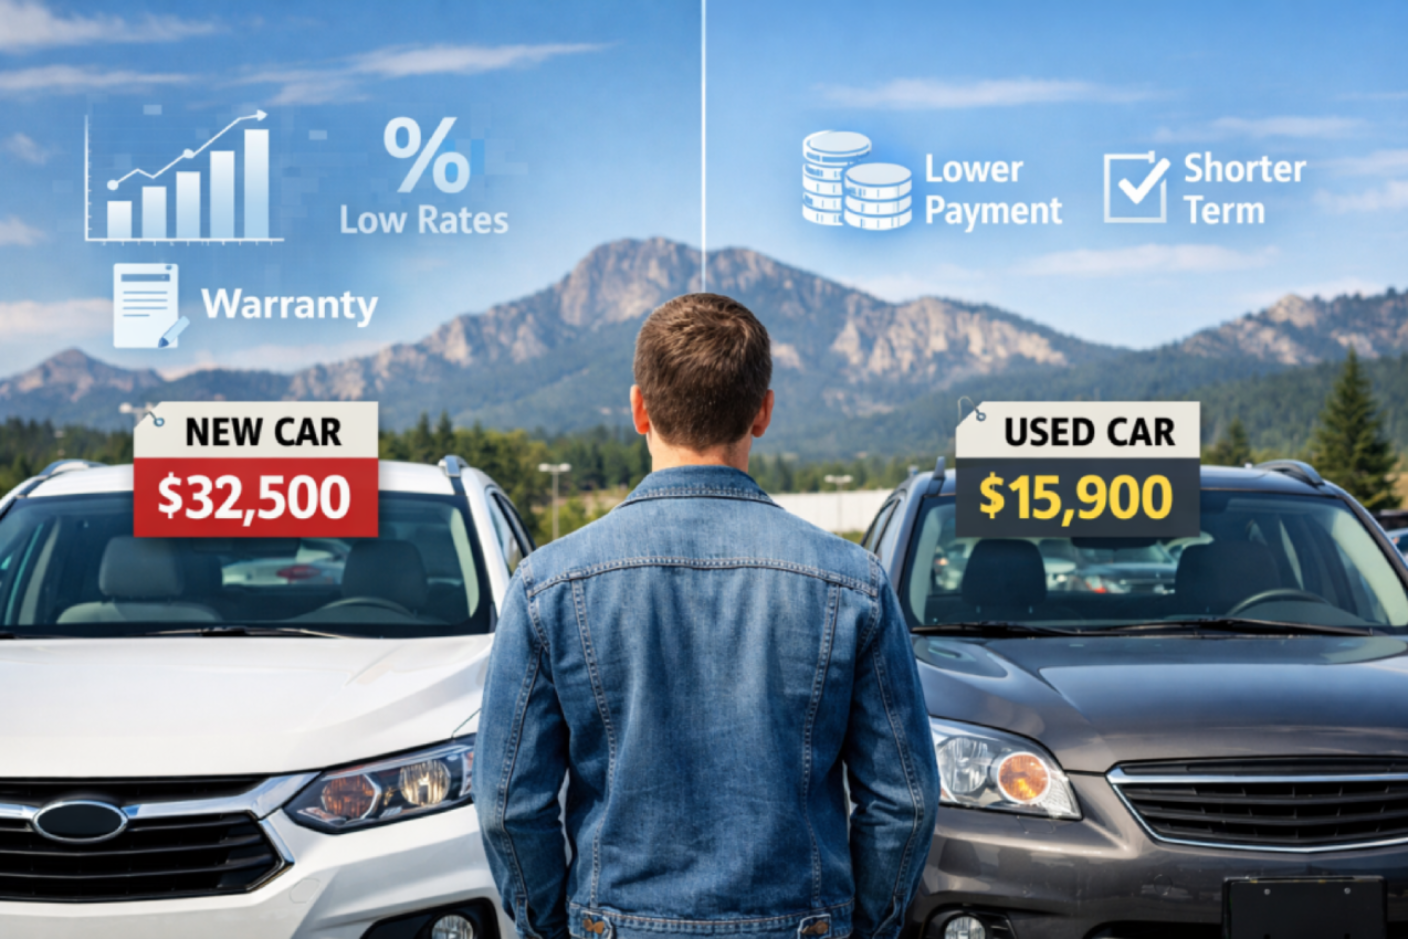
America First Credit Union (AFCU) provides versatile auto financing options for new and used vehicles, featuring competitive interest rates, flexible terms up to 84 months, and a streamlined digital application process. As a member-owned institution, it prioritizes low-cost lending and personalized service for residents in the Intermountain West and beyond.
Navigating the landscape of automotive finance in 2026 requires a clear understanding of how credit unions differ from traditional big-box banks. America First Credit Union (AFCU) has established itself as a major player in the vehicle lending space, particularly within Utah, Nevada, Arizona, Idaho, and New Mexico. Unlike commercial banks that focus on shareholder profits, AFCU operates as a non-profit cooperative, which typically translates into lower interest rates and reduced fees for its members.
When searching for an "af cu car loan overview," it is essential to distinguish America First from other similarly named institutions like the Air Force Federal Credit Union. This guide focuses specifically on America First Credit Union, the sixth-largest credit union in the United States by membership, providing a comprehensive analysis of their current automotive lending portfolio, eligibility criteria, and strategic advantages for borrowers.
Eligibility and Membership Requirements
Before accessing an AFCU car loan, you must first establish membership with the credit union. Credit unions are restricted by federal or state charters regarding who they can serve. AFCU utilizes a "field of membership" model that is primarily geographical but offers several pathways for inclusion.
Geographical and Occupational Qualifications
The most common way to join is by living, working, worshipping, or attending school in one of the specific counties AFCU serves. These core areas include major metropolitan regions across the Southwest and Intermountain West. If you do not live in these areas, you may still be eligible if an immediate family member is already a member of the credit union. Furthermore, many employers in the region have "Select Employer Group" (SEG) status, allowing their employees to join regardless of residency.
The Share Savings Account
To finalize membership, you are required to open a Primary Savings Account with a minimum deposit, usually $5.00. This "share" represents your ownership stake in the credit union. Once this account is active, you are eligible to apply for any of their lending products, including new and used auto loans. In 2026, this process is almost entirely digital, requiring only a government-issued ID and a Social Security number for verification.
Comprehensive Loan Types Offered by AFCU
AFCU does not offer a one-size-fits-all loan. Their product suite is designed to accommodate different stages of vehicle ownership and various types of transportation.
New Auto Loans
New vehicle loans are generally defined as financing for vehicles from the current or previous model year that have not been previously titled. These loans typically carry the lowest interest rates because the vehicle's collateral value is high and predictable. AFCU offers financing for up to 100% of the Manufacturer’s Suggested Retail Price (MSRP), including taxes, licensing, and extended warranties.
Used Auto Loans
Used car financing is a significant portion of AFCU’s business. They provide loans for vehicles up to 10 or 12 years old, though the most favorable rates are reserved for "newer" used cars (those under five years old). When financing a used car, AFCU typically uses the National Automobile Dealers Association (NADA) retail value to determine the maximum loan amount. Borrowers can often finance up to 115% of the vehicle’s value to cover additional costs.
Auto Refinancing
Refinancing is an ideal strategy for members who originally financed their vehicle through a dealership or another bank at a higher rate. By moving the loan to AFCU, borrowers can often reduce their monthly payments or shorten their loan term. AFCU frequently offers "cash-out" refinance options, allowing members to tap into the equity of their vehicle for other financial needs, provided the loan-to-value (LTV) ratio remains within acceptable limits.
Analysis of Interest Rates and Terms
In the 2026 financial climate, AFCU maintains a tiered interest rate structure based on the borrower’s creditworthiness, the age of the vehicle, and the length of the loan term. While exact rates fluctuate with the Federal Reserve's decisions, AFCU remains consistently below the national average for commercial banks.
Factors Influencing Your Rate
- Credit Score: Members with "A+" credit (typically scores above 740) receive the prime rate.
- Loan Term: Shorter terms (e.g., 36 to 48 months) usually command lower interest rates than longer terms (72 to 84 months).
- Automatic Payments: AFCU often offers a 0.25% rate discount if the borrower sets up automatic transfers from an AFCU checking account.
- Down Payment: While 100% financing is available, providing a down payment reduces the credit union's risk and can occasionally improve the tier of the loan.
Typical Loan Structure Comparison (Estimated 2026)
| Loan Type | Typical Term (Months) | Estimated APR Range | Max Financing |
|---|---|---|---|
| New Auto (Current/Next Year) | 36 - 84 | 4.99% - 7.49% | 100% MSRP |
| Used Auto (1-5 Years Old) | 36 - 72 | 5.24% - 8.99% | 115% NADA Retail |
| Used Auto (6+ Years Old) | 36 - 60 | 6.49% - 12.00% | 100% NADA Retail |
| Refinance (External Only) | 36 - 84 | Match or Beat* | 110% Value |
*Note: Refinance "Match or Beat" programs are subject to floor rates and credit approval.
The Step-by-Step Application Process
America First has streamlined its application to be completed in under 10 minutes through their mobile app or website. For those who prefer a face-to-face interaction, their extensive branch network provides on-site loan officers.
1. Pre-Approval
Before visiting a dealership, it is highly recommended to obtain a pre-approval. This gives you the bargaining power of a "cash buyer." AFCU will provide you with a maximum loan amount and a locked-in interest rate valid for 30 to 60 days. This prevents "rate markup" at the dealership, where finance managers may add points to a loan for their own profit.
2. Documentation Requirements
To process the application, you will need:
- Current employment information and gross monthly income.
- The Vehicle Identification Number (VIN) and exact mileage (for used cars).
- Dealer purchase order or a bill of sale from a private party.
- Proof of valid automotive insurance with AFCU listed as the lienholder.
3. Closing and Funding
Once approved, the funds can be disbursed in several ways. If buying from a dealer, AFCU can send a direct wire or provide a specialized "draft" (a check that the dealer can deposit). For private party sales, both the buyer and seller usually meet at an AFCU branch to sign the title and exchange funds, ensuring a legal and secure transaction for both parties.
Ancillary Protection Products
One of the nuances of an AFCU car loan overview is the availability of add-on products that protect the member’s investment. While optional, these are often more affordable through the credit union than the dealership.
Guaranteed Asset Protection (GAP)
If your vehicle is totaled or stolen, insurance companies only pay the current market value. If you owe more on your loan than the car is worth (being "underwater"), GAP coverage pays the difference. AFCU’s GAP insurance often includes a "deductible assistance" feature, which can cover your primary insurance deductible up to a certain amount.
Mechanical Repair Coverage (MRC)
Similar to an extended warranty, MRC covers the costs of major repairs after the manufacturer's warranty expires. AFCU offers various tiers of coverage, from basic drivetrain protection to "platinum" plans that cover almost every mechanical and electronic component of the vehicle.
Credit Life and Disability Insurance
In the event of the borrower’s death or total disability, these insurance products can pay off the remaining loan balance or cover monthly payments. This is particularly relevant for families relying on a single income to service the debt.
Strategic Advantages of AFCU Auto Loans
Choosing America First over a national bank or dealer financing offers several qualitative benefits that are often overlooked in a simple rate comparison.
- Local Decision Making: Loan officers at AFCU have the discretion to look beyond just a credit score. They consider the member's overall relationship with the credit union, which can be pivotal for those with "thin" credit files.
- No Prepayment Penalties: Members are encouraged to pay off their loans early to save on interest. AFCU does not charge fees for extra payments or early closures.
- Dealer Direct Financing: AFCU partners with hundreds of dealerships in the West. You can often tell the dealer you want to finance through America First, and they can pull up the AFCU system right at the desk, combining the convenience of dealer financing with credit union rates.
- Financial Counseling: As part of their mission, AFCU provides free financial counseling. If a member is struggling to qualify for a loan, counselors can help create a roadmap for credit repair.
Potential Limitations and Considerations
While the benefits are significant, there are a few limitations to consider. First, the membership requirement is a hurdle for those outside their service area. Second, for very old high-mileage vehicles or classic cars, AFCU may require a "Personal Loan" rather than an "Auto Loan," which carries higher interest rates. Lastly, while their digital tools are excellent, their physical branch footprint is concentrated in the Western U.S., which may be a drawback for members who move to the East Coast and prefer in-person service.
Financial Disclaimer: This overview is for informational purposes only and does not constitute professional financial advice. Interest rates, terms, and eligibility requirements are subject to change based on market conditions and individual credit profiles. Always consult with a certified financial advisor or an official America First Credit Union representative before making significant borrowing decisions.
Frequently Asked Questions
Can I get an AFCU car loan for a private party sale?
Yes, America First Credit Union actively supports private party transactions. They facilitate the title transfer process and ensure that the seller's existing lien is paid off correctly. It is often safest to conduct the final signing at a local branch where a notary and loan officer can oversee the exchange of the title and funds.
What is the minimum credit score required for an AFCU auto loan?
While AFCU does not publicly disclose a hard minimum, they generally work with borrowers across the entire credit spectrum. Borrowers with scores below 600 may face higher interest rates or require a co-signer, while those with scores above 740 typically qualify for the lowest advertised rates. They look at the "whole picture," including debt-to-income ratio and employment history.
Does AFCU offer loans for motorcycles or RVs?
Yes, AFCU has a robust "Leisure Vehicle" lending program. This includes motorcycles, ATVs, boats, motorhomes, and travel trailers. The terms and rates for these vehicles differ from standard auto loans—usually involving slightly higher rates and different maximum terms—but the application process remains the same.
How long does the pre-approval process take?
For most members, a pre-approval can be granted instantly through the online banking portal or mobile app. If the application requires a manual review by a loan officer (often due to complex income or credit issues), it typically takes one business day. Once pre-approved, the commitment is generally valid for 60 days.
Can I skip a payment on my AFCU car loan?
AFCU occasionally offers a "Skip-a-Payment" program, usually during the holiday season or times of economic hardship. To qualify, your loan must be in good standing, and a small processing fee is usually required. Interest continues to accrue during the skipped month, which extends the life of the loan.
Final Recommendation for Borrowers
For individuals residing within the America First service area, an AFCU auto loan is consistently one of the most cost-effective ways to finance a vehicle in 2026. To maximize your savings, begin by cleaning up your credit report three months before shopping and obtain a pre-approval from AFCU before visiting any dealership. This ensures you are protected from high-pressure sales tactics and can focus on negotiating the best price for the vehicle itself, knowing your financing is already secured at a competitive, member-driven rate.