Finding the best life insurance policy for a man aged 60 involves identifying specific financial goals, comparing term and permanent options, and navigating age-related underwriting. By age 60, the focus typically shifts from family protection to mortgage coverage, estate planning, or final expenses. Success requires evaluating health status accurately and comparing quotes from senior-focused carriers to secure the most cost-effective premium.
Step 1: Define Your Financial Objectives at Age 60
The first and most critical step is determining exactly why you need life insurance at this stage of life. For a 60-year-old man, the "need" for insurance is often significantly different than it was at age 30 or 40. In 2026, with rising costs of living and varying retirement ages, the objectives usually fall into three main categories: debt protection, income replacement for a spouse, or legacy and final expense planning.
If you still have a mortgage or significant personal debt, a term life insurance policy that matches the remaining duration of that debt is often the most logical choice. However, if your primary concern is ensuring your spouse can maintain their standard of living after you pass—especially if your pension or Social Security benefits will decrease—you must calculate the "income gap" that your death would create.
Furthermore, many men at 60 look toward "final expense" or "burial insurance." These are smaller, permanent policies designed to cover funeral costs and minor medical bills, ensuring that the burden does not fall on surviving children. Alternatively, if you have a high net worth, you might use life insurance as a tool for estate liquidity, providing the cash needed to pay estate taxes without forcing heirs to sell off assets. Defining these goals early prevents you from over-insuring or purchasing a policy type that doesn't align with your timeline.
Step 2: Navigate the Different Types of Life Insurance
Once your goals are clear, you must choose the structure of the policy. At 60, the cost of insurance begins to rise more sharply each year, making the choice between term and permanent coverage a high-stakes decision.
Term Life Insurance: Is it Still Viable?
Term life insurance provides coverage for a specific period, such as 10, 15, or 20 years. For a 60-year-old, a 20-year term policy will cover you until age 80. This is often the most affordable way to get a high death benefit. It is ideal for covering a mortgage or protecting a spouse until retirement accounts are fully accessible. However, be aware that in 2026, many carriers limit term lengths for applicants over 60; for instance, finding a 30-year term at age 60 is increasingly rare and prohibitively expensive.
Permanent Life Insurance: Whole vs. Universal
Permanent life insurance lasts your entire life as long as premiums are paid and often includes a cash value component.
- Whole Life Insurance: Offers fixed premiums and a guaranteed death benefit. While expensive, it provides certainty.
- Universal Life (UL): Offers more flexibility in premium payments and death benefits. In 2026, Guaranteed Universal Life (GUL) has become a popular "middle ground" for seniors. GUL functions like a term policy that lasts until a specific age (like 90, 95, or 121) but lacks the expensive cash-value accumulation of traditional whole life, making it more affordable for those who just want a guaranteed payout.
Final Expense Insurance
Also known as "burial insurance," these are small whole life policies (typically $5,000 to $25,000). They are easier to qualify for, often requiring no medical exam, but the cost per $1,000 of coverage is much higher than standard policies.
Step 3: Realistic Health Assessment and Underwriting Expectations
At age 60, your health is the primary factor determining your premium. Insurance companies use underwriting classes to categorize risk. These typically range from "Preferred Plus" (the healthiest) to "Standard" and "Substandard" (for those with chronic issues).
It is vital to be honest about your medical history. Common conditions for 60-year-old men, such as hypertension (high blood pressure) or high cholesterol, do not automatically disqualify you from "Preferred" rates, provided they are well-controlled by medication. However, more serious issues like Type 2 diabetes, a history of tobacco use, or recent cardiac events will move you into a higher-cost tier.
In 2026, many insurers utilize "accelerated underwriting," which uses data from your medical records and prescription history to skip the traditional paramedical exam (blood draw and physical). If you are in excellent health, look for "no-exam" policies that still offer competitive rates. If you have significant health challenges, you may need to look at Guaranteed Issue policies, which have no health questions but include a "graded death benefit" (meaning the full amount isn't paid out if you die within the first two years of the policy).
Step 4: Calculating the Ideal Coverage Amount
Over-insuring at 60 is a common financial mistake. Every dollar of coverage at this age is more expensive than it was a decade ago. To find the "best" policy, you must find the "leanest" amount of coverage that still meets your needs.
A standard approach is the DIME Formula, adjusted for the senior context:
- Debt: Sum up your mortgage, car loans, and credit cards.
- Income Replacement: Calculate how many years your spouse would need an income supplement and multiply that by the annual amount needed.
- Mortgage: Specifically isolate the home payoff if that is your primary goal.
- Final Expenses/Education: Include funeral costs (averaging $10,000–$15,000 in 2026) and any remaining legacy gifts for grandchildren.
Subtract your existing liquid assets (savings, 401k, existing life insurance) from this total. The resulting number is your required coverage amount. For many 60-year-old men, a policy between $250,000 and $500,000 is the "sweet spot" for comprehensive protection, while those only seeking burial coverage focus on $10,000 to $25,000.
Step 5: Identifying Top-Rated Insurers for Seniors
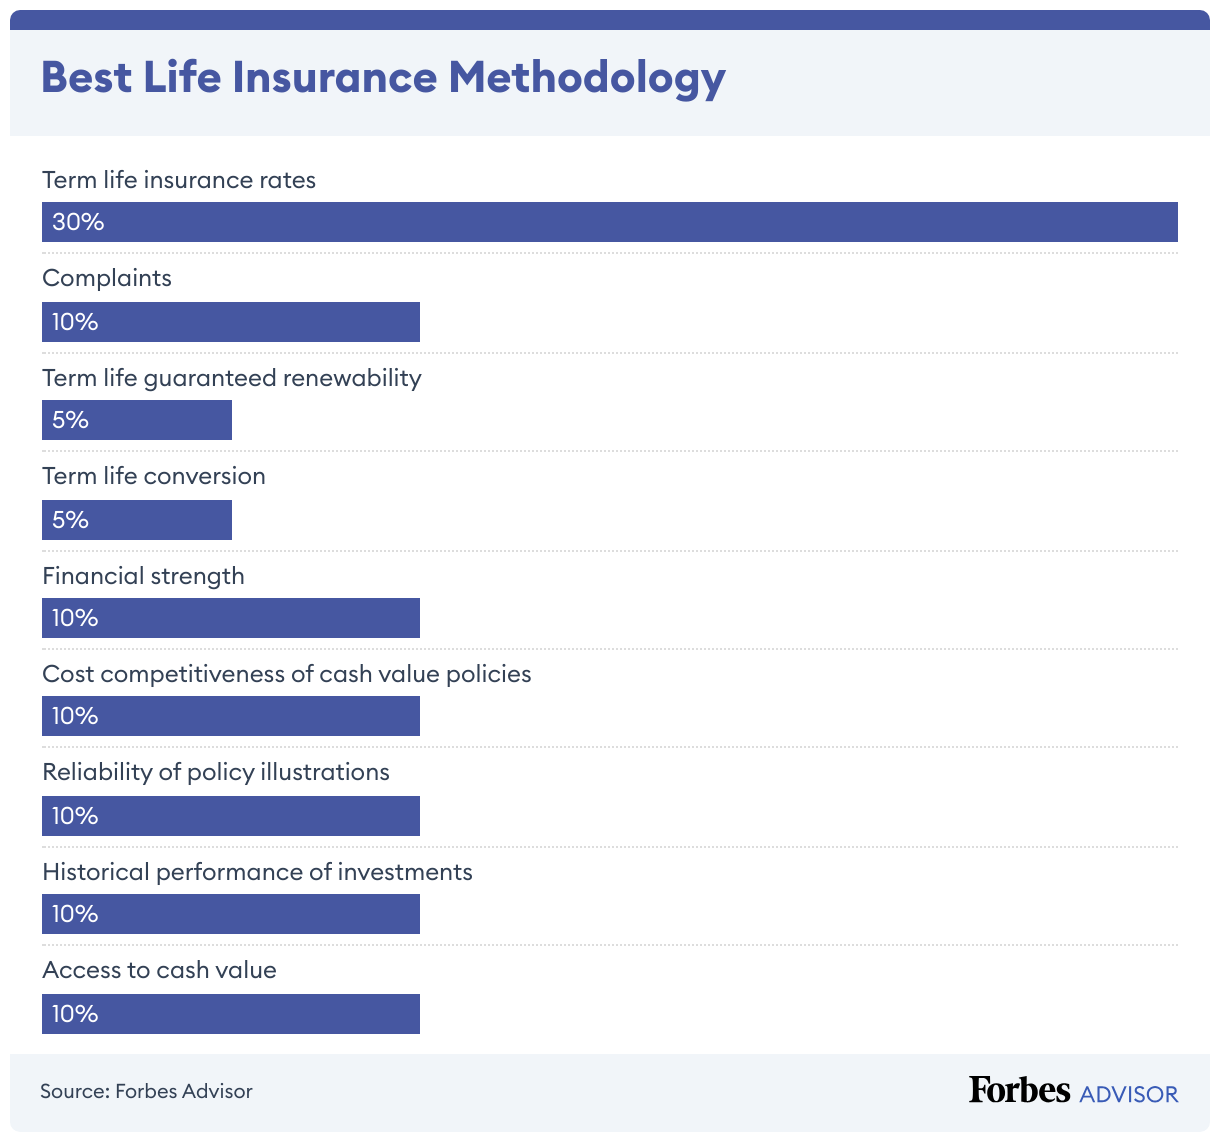
Not all insurance companies specialize in the senior market. Some carriers offer excellent rates for 25-year-olds but are uncompetitive for 60-year-olds. When researching, prioritize companies with high financial strength ratings from agencies like A.M. Best or Standard & Poor’s.
In the 2026 market, look for carriers with a strong track record in "age-nearest" underwriting. Some companies calculate your age based on your last birthday, while others use your "nearest" birthday. If you are 60 and six months, some companies will price you as a 61-year-old, which can increase premiums by 8-12%.
Furthermore, check the National Association of Insurance Commissioners (NAIC) for complaint ratios. You want a company that not only has low rates but also a history of efficient claims processing. High-quality insurers for seniors often include mutual companies, which are owned by policyholders and may pay dividends on permanent policies.
Step 6: Comparing Premiums and Strategic Riders
Once you have a list of carriers, compare "apples to apples" quotes. Do not look only at the monthly premium; look at the policy riders. Riders are optional add-ons that can provide significant value for a man aged 60.
- Accelerated Death Benefit (Living Benefits): This is essential. It allows you to access a portion of the death benefit while you are still alive if you are diagnosed with a terminal or chronic illness. This can help pay for long-term care or medical bills.
- Waiver of Premium: This rider pauses your premium payments if you become totally disabled. However, note that many carriers stop offering this rider once the applicant reaches age 60 or 65.
- Conversion Rider: If you buy a term policy, ensure it has a conversion rider. This allows you to turn your term policy into a permanent one later without a new medical exam—a vital feature if your health declines.
Comparison of Life Insurance Options for a 60-Year-Old Man (2026 Estimates)
| Policy Type | Typical Duration | Medical Exam? | Best For... |
|---|---|---|---|
| 10-Year Term | 10 Years | Often Optional | Short-term debt or mortgage protection. |
| 20-Year Term | 20 Years | Usually Required | Protecting a spouse until age 80. |
| Guaranteed Universal (GUL) | To Age 95+ | Required | Permanent protection without high cost. |
| Whole Life | Lifetime | Required | Estate planning and cash value growth. |
| Guaranteed Issue | Lifetime | No | Men with serious health issues (limited benefit). |
Step 7: Navigating the Application and the "Free Look" Period
The final step is the application process. Once you submit your application, the "underwriting" period begins, which can take anywhere from a few days (for simplified issue) to six weeks (for fully underwritten policies).
During this time, the insurer will review your Medical Information Bureau (MIB) report and your motor vehicle record. In 2026, they may also use "predictive modeling" based on public records. If a medical exam is required, schedule it for the morning, avoid caffeine and tobacco for 24 hours prior, and stay hydrated to ensure the best possible blood pressure and lab results.
Once the policy is issued and you pay the first premium, the "Free Look" Period begins. Most states mandate a period of 10 to 30 days during which you can review the physical policy documents. If you find the terms are not what you expected, or if you find a better deal elsewhere, you can cancel the policy for a full refund of any premiums paid. This is your safety net to ensure the policy you chose is truly the best fit.
Common Pitfalls to Avoid
When shopping for life insurance at 60, avoid these frequent errors:
- Waiting Too Long: Life insurance prices increase significantly with every birthday after 60. A delay of one year can result in a permanent 10% increase in your annual premium.
- Underestimating Health: Do not assume you are "uninsurable" because of a condition like managed diabetes. Conversely, do not hide health issues, as this can lead to a "contestability" claim denial later.
- Ignoring the "Ladder" Strategy: Instead of one large $500,000 policy, some 60-year-olds buy a $250,000 10-year term for the mortgage and a $250,000 permanent policy for the spouse. This "laddering" can save thousands in total premiums.
- Relying Solely on Employer Coverage: Most group life insurance policies end when you retire. If you wait until you retire at 65 to buy individual coverage, you will pay much more than you would at 60.
FAQ
Can a 60-year-old man get life insurance without a medical exam?
Yes. In 2026, many carriers offer "Simplified Issue" or "Accelerated Underwriting" policies for 60-year-olds. These use electronic health records to approve you in minutes or days. However, if you are in excellent health, taking the medical exam often results in a lower premium because it provides the insurer with more certainty.
Is term life insurance a waste of money if I outlive it?
Not necessarily. Life insurance is a risk-management tool. If you buy a 15-year term to cover your mortgage and you outlive the term, the policy has served its purpose: it protected your home during the years of highest financial risk. For those who want a guaranteed return, a permanent policy or a "Return of Premium" rider (though expensive) may be more appropriate.
How do Social Security benefits impact my life insurance needs at 60?
When a spouse passes away, the survivor usually receives the higher of the two Social Security checks, but the smaller check stops. This "lost check" represents a permanent drop in household income. Your life insurance policy should be sized to replace that lost income for the survivor's remaining life expectancy. More information on survivor benefits can be found at the Social Security Administration (SSA).
What is the maximum age for a 20-year term policy?
Most insurers allow a 60-year-old man to purchase a 20-year term policy. However, as you approach 65 or 70, the availability of 20-year terms diminishes. By age 60, you are near the upper limit for the most affordable 20-year term rates.
Should I use an independent agent or buy online?
For a 60-year-old, an independent agent is usually better. They have access to multiple carriers and know which ones are "friendly" toward specific health conditions. While online "instant" quotes are convenient for healthy 30-year-olds, the nuances of senior underwriting often require the expertise of an agent to find the lowest price.
Final Recommendation
If you are a 60-year-old man looking for the best life insurance policy, act now. Every month you wait increases the cost. Start by calculating your "must-cover" expenses (mortgage and spouse's income) and then seek quotes for both a 15-year term and a Guaranteed Universal Life policy. This comparison will show you the cost difference between temporary protection and a lifetime guarantee, allowing you to make an informed decision based on your 2026 budget and long-term retirement strategy.