A net worth of $30 million places a married couple firmly within the ultra-high-net-worth individual tier, unlocking advanced estate planning strategies, specialized private banking services, and complex asset protection structures. Achieving and maintaining this level of wealth requires a sophisticated blend of tax optimization, diversified investing, and intentional risk management tailored to joint financial ownership.
Reaching a joint net worth of $30 million is a milestone that transforms how a family manages liquidity, transfers wealth across generations, and structures philanthropic giving. For couples navigating this echelon of financial success, the focus shifts rapidly from capital accumulation to capital preservation, liability mitigation, and structural efficiency. Whether this wealth is built through closely held operating businesses, concentrated equity compensation, real estate portfolios, or disciplined multi-decade investing, managing $30 million requires specialized knowledge.
Understanding the mechanics, legal frameworks, and structural considerations of ultra-high-net-worth management ensures that a couple can protect their principal, optimize their tax liabilities, and align their financial resources with long-term personal values.
Defining Ultra-High-Net-Worth Status for Married Couples
In the landscape of personal finance and wealth management, net worth is calculated as total assets minus total liabilities. Assets encompass everything from primary residences and vacation homes to retirement accounts, taxable brokerage portfolios, private equity holdings, and business valuations. Liabilities include mortgages, margin loans, business debt, and personal loans.
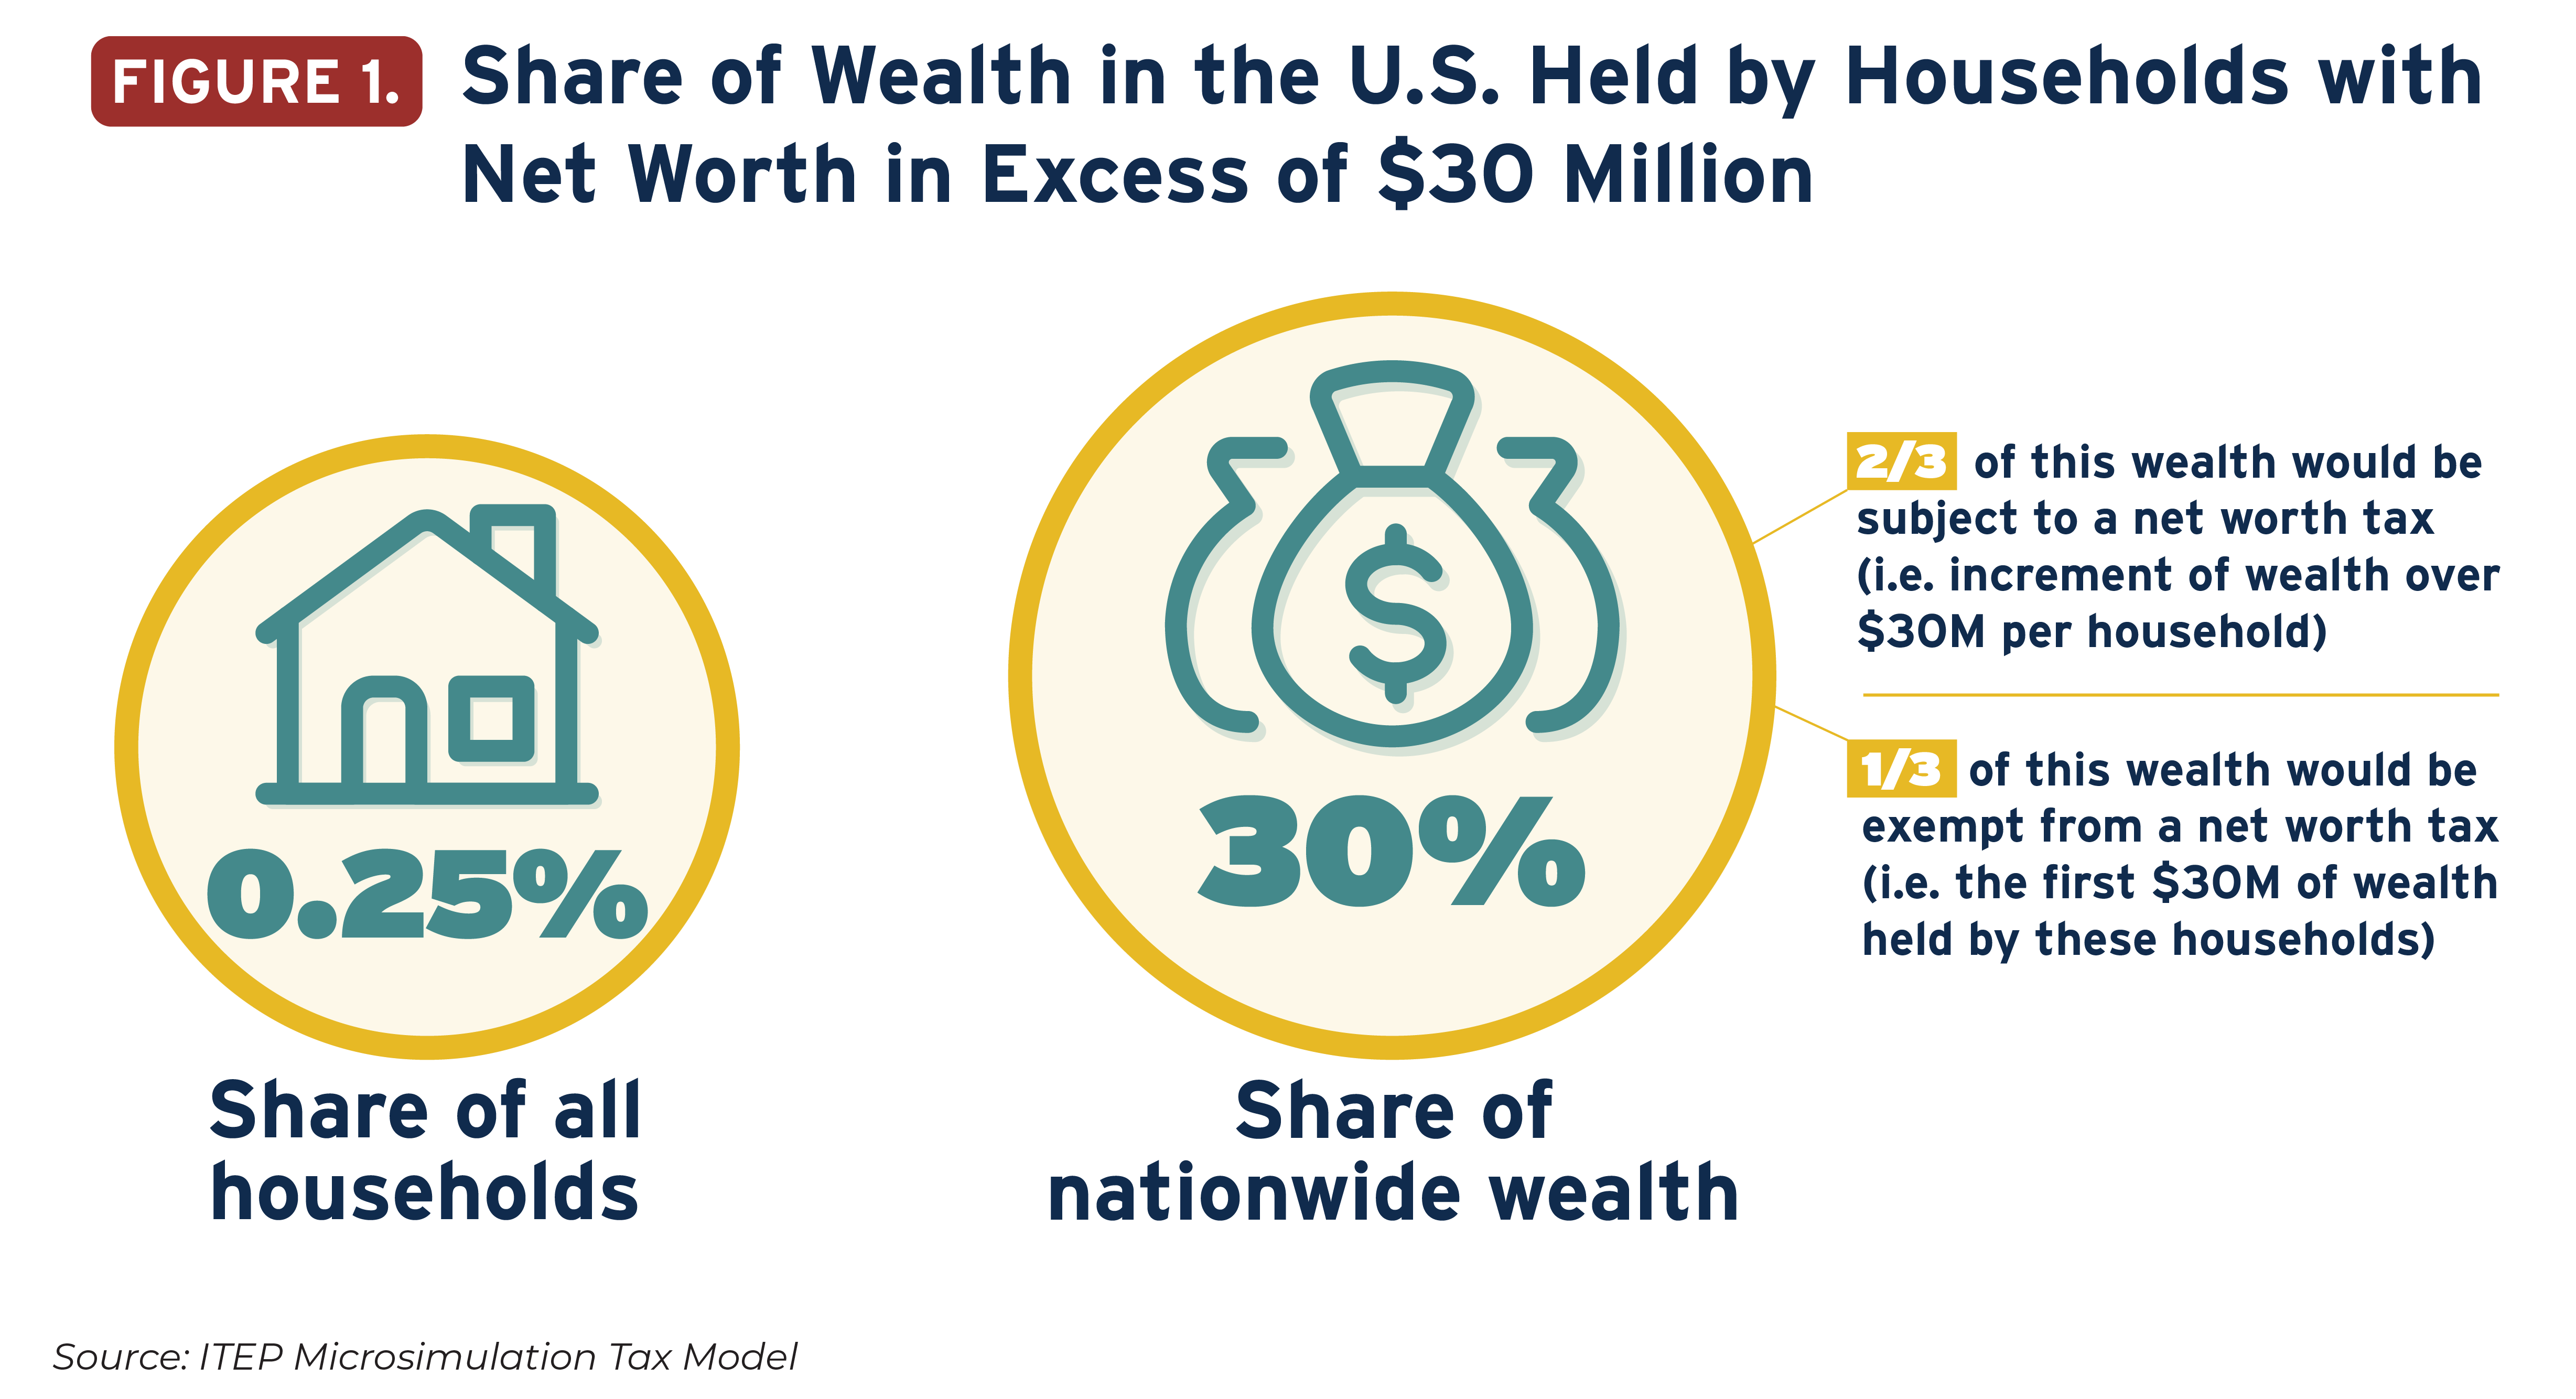
When a married couple reaches a combined net worth of $30 million, they enter the ultra-high-net-worth individual (UHNWI) category. Historically, the threshold for UHNWI status is often cited as $30 million, a benchmark frequently utilized by wealth research firms and private banking institutions such as UBS and Wealth-X.
Reaching this milestone as a married couple changes the regulatory, legal, and financial ecosystem surrounding the household. Financial institutions view $30 million as the entry point for dedicated family office services, bespoke investment products, and sophisticated lending facilities. Furthermore, estate tax exemptions, liability exposures, and insurance requirements scale exponentially once assets cross this threshold.
Primary Wealth Drivers for High-Net-Worth Households
Couples who achieve a $30 million net worth rarely do so through a single savings account or a standard retirement portfolio. Wealth of this magnitude typically stems from specific, high-leverage financial engines. Identifying these drivers helps clarify how such fortunes are built and maintained.
Closely Held Businesses and Entrepreneurship
The most common pathway to an ultra-high-net-worth portfolio is founding, scaling, and successfully exiting a privately held business. Entrepreneurs often hold the majority of their wealth in illiquid equity. As the business grows, valuation increases compound rapidly.
Managing this wealth involves balancing operational risk with personal liquidity, often requiring recapitalizations, employee stock ownership plans (ESOPs), or strategic mergers and acquisitions.
Executive Compensation and Concentrated Stock
Corporate executives frequently accumulate multi-million-dollar portfolios through a combination of base salary, performance bonuses, restricted stock units (RSUs), and non-qualified stock options.
When a couple's wealth is tied to a single publicly traded company, managing concentration risk becomes an urgent priority. Utilizing instruments such as 10b5-1 trading plans allows executives to systematically diversify their holdings over time without triggering insider trading concerns.
Real Estate Portfolios and Development
Commercial and residential real estate development can generate substantial net worth through leverage, cash flow appreciation, and tax advantages such as depreciation and 1031 exchanges. Real estate holdings at the $30 million level usually comprise a mix of direct property ownership, private real estate investment trusts (REITs), and limited partnership shares in private equity real estate funds.
Multi-Generational Inheritance and Trust Structures
A significant percentage of ultra-high-net-worth households inherit wealth. Managing inherited wealth requires navigating pre-existing trust agreements, family governance charters, and complex distribution schedules designed to preserve capital across multiple generations while minimizing estate and generation-skipping transfer taxes.
Strategic Asset Allocation and Portfolio Construction
At a $30 million net worth, standard retail portfolio models—such as the classic 60/40 stock-and-bond split—are rarely sufficient to meet the sophisticated goals of a married couple. Wealth preservation, inflation hedging, and liquidity management demand a multi-asset-class approach.
| Asset Class / Strategy | Primary Purpose in a $30M Portfolio |
|---|---|
| Public Equities | Liquidity, long-term growth, inflation hedge |
| Private Equity & Venture | Enhanced yield, asymmetric growth potential |
| Commercial Real Estate | Cash flow generation, tangible asset backing |
| Fixed Income & Credit | Capital preservation, predictable income streams |
| Alternative Assets | Portfolio decorrelation, inflation protection |
Private Equity and Venture Capital
Because $30 million portfolios have longer investment horizons and greater liquidity tolerance, private markets play a prominent role. Allocating capital to private equity funds, venture capital syndicates, and direct private placements offers access to high-growth companies before they enter public markets. However, these investments require capital lockups that can span a decade or more.
Private Credit and Structured Finance
As traditional banking tightened lending standards, private credit emerged as a primary income driver for wealthy families. Direct lending funds, mezzanine debt, and distressed debt strategies provide high yields that can outperform traditional corporate bonds while offering senior secured positions in corporate capital structures.
Liquid Alternatives and Hedge Funds
Global macro, long/short equity, and managed futures strategies are designed to generate positive absolute returns regardless of broader market direction. For a $30 million household, these strategies act as shock absorbers during market downturns, reducing overall portfolio volatility.
Tax Optimization and Advanced Structuring
Tax efficiency is a cornerstone of managing a $30 million married couple net worth. At this level, marginal tax rates can erode capital rapidly if proactive strategies are not implemented. Comprehensive tax planning integrates federal, state, and international obligations.
Tax-Loss Harvesting and Direct Indexing
In taxable brokerage accounts, sophisticated wealth managers utilize direct indexing and systematic tax-loss harvesting. By owning the individual constituent stocks of an index rather than an exchange-traded fund (ETF), managers can sell losing positions to offset capital gains elsewhere in the portfolio while maintaining market exposure.
Municipal Bonds and Tax-Exempt Yields
For couples in high-tax states facing top federal and state income tax brackets, high-yield municipal bond portfolios generate tax-free income. This approach lowers adjusted gross income (AGI) while providing steady cash flow for living expenses or philanthropic initiatives.
Charitable Vehicles and Philanthropy
Philanthropy serves both social goals and financial optimization at the $30 million level. Utilizing Donor-Advised Funds (DAFs) allows couples to make lump-sum contributions of appreciated securities or closely held stock, taking an immediate charitable deduction while distributing grants to non-profit organizations over time.
For more complex legacy gifting, Charitable Remainder Trusts (CRTs) and Charitable Lead Trusts (CLTs) provide income streams to family members while transferring remainder value to charitable causes tax-free.
Estate Planning, Asset Protection, and Governance
Protecting a $30 million estate from excessive taxation, litigation risks, and poor generational transition requires specialized legal architecture. Married couples must coordinate their estate plans to maximize current federal exemptions while preparing for legislative changes.
Leveraging Spousal Lifetime Access Trusts (SLATs)
A Spousal Lifetime Access Trust is an irrevocable trust established by one spouse for the benefit of the other. By funding a SLAT, a couple can utilize their lifetime gift tax exemptions to remove assets—and all future appreciation on those assets—from their taxable estate, while the beneficiary spouse retains indirect access to trust income.
Family Limited Partnerships (FLPs) and Asset Protection
Operating businesses and extensive real estate portfolios are frequently organized inside Family Limited Partnerships or Family Limited Liability Companies. These structures separate operational control from economic ownership, offering valuation discounts for gift and estate tax purposes while shielding personal assets from commercial liabilities and litigation.
Generation-Skipping Transfer (GST) Tax Planning
To ensure that wealth transfers efficiently to children and grandchildren without incurring punitive generation-skipping transfer taxes, ultra-high-net-worth couples allocate portions of their GST exemption to irrevocable dynasty trusts. These trusts can manage wealth for multiple generations while protecting assets from creditors and divorcing spouses.
Family Office Services and Wealth Management Teams
Managing a $30 million enterprise requires a multidisciplinary advisory team. While households with $1 to $5 million typically utilize a traditional financial planner, a $30 million net worth warrants a more comprehensive advisory model.
Single-Family vs. Multi-Family Offices
While a dedicated Single-Family Office (SFO) is typically reserved for families with net worths exceeding $100 million due to operating costs, a $30 million couple often engages with Multi-Family Offices (MFOs) or specialized boutique wealth management firms. These organizations provide integrated services spanning investment management, tax preparation, bill pay, concierge services, and family governance under one roof.
Coordinating the Core Advisory Trio
Every ultra-high-net-worth couple should maintain an active advisory trio consisting of:
- A Certified Public Accountant (CPA) or Tax Attorney: Specializing in ultra-high-net-worth entity structuring and multi-jurisdictional compliance.
- An Estate Planning Attorney: Well-versed in irrevocable trust design, dynasty planning, and cross-border asset transfers.
- A Wealth Manager or Chief Investment Officer: Overseeing portfolio construction, risk management, and liquidity planning.
Common Pitfalls and Risk Management Strategies
Accumulating and maintaining $30 million exposes a married couple to unique risks that can jeopardize long-term financial security if ignored.
Over-Concentration in Illiquid Assets
A frequent mistake among entrepreneurs and real estate investors is tying up 80% or more of their $30 million net worth in illiquid assets. When an unexpected liquidity need arises—such as estate tax liabilities, business opportunities, or legal settlements—forced liquidations of illiquid assets can destroy value. Maintaining a robust liquid reserve of 10% to 15% in cash equivalents and publicly traded securities mitigates this danger.
Inadequate Liability and Umbrella Insurance
Wealth acts as a magnet for litigation. Standard homeowners and auto insurance policies provide insufficient liability limits for ultra-high-net-worth households. Couples should secure high-limit personal umbrella liability policies and excess liability insurance, often up to $50 million or more, combined with equity-stripping asset protection trusts where necessary.
Absence of Family Governance and Financial Literacy
The statistical reality of generational wealth transfer indicates that a large portion of fortunes are depleted by the third generation. This erosion is rarely caused by poor investments alone; rather, it stems from a lack of communication regarding wealth stewardship. Establishing formal family meetings, teaching heirs financial literacy, and implementing phased inheritance milestones protect both the family and the capital.
Frequently Asked Questions
What qualifies a married couple as ultra-high-net-worth?
A married couple is typically classified as ultra-high-net-worth when their combined net worth reaches or exceeds $30 million. This threshold is recognized across private banking, wealth research, and family office sectors as the benchmark where advanced financial, tax, and estate advisory services become necessary.
How much income does a $30 million net worth generate?
Income generation depends entirely on asset allocation. If a portfolio maintains a conservative 3% to 4% annual withdrawal or yield rate, a $30 million net worth can generate between $900,000 and $1.2 million annually in pre-tax cash flow without depleting the underlying principal.
What is the best way to protect a $30 million estate from taxes?
The most effective protection involves utilizing lifetime gift tax exemptions through irrevocable trusts such as Spousal Lifetime Access Trusts (SLATs), Dynasty Trusts, and Family Limited Partnerships (FLPs). These legal structures remove assets and their future appreciation from the taxable estate.
Should a $30 million couple establish a family office?
A dedicated Single-Family Office is typically cost-effective starting around $100 million in net worth. However, a $30 million couple frequently utilizes Multi-Family Offices or specialized wealth advisory firms to coordinate tax, legal, and investment management services efficiently.
How can a couple manage concentrated stock positions safely?
Concentrated equity positions can be managed through 10b5-1 predetermined trading plans, exchange funds, collar strategies (buying put options and selling call options), or charitable remainder trusts, allowing diversification without triggering immediate capital gains taxes.
Conclusion and Next Actionable Steps
Reaching and maintaining a $30 million married couple net worth requires transitioning from passive accumulation to active, institutional-grade stewardship. The primary action for couples at this level is a comprehensive audit of their current advisory ecosystem, legal structures, and asset allocation strategies.
Begin by scheduling a joint review with your estate planning attorney and CPA to verify that your trust structures align with current tax laws and that your liability insurance limits fully reflect your asset exposure. By prioritizing proactive tax optimization, robust asset protection, and disciplined portfolio diversification, you can preserve your wealth across generations and secure your family's financial legacy.