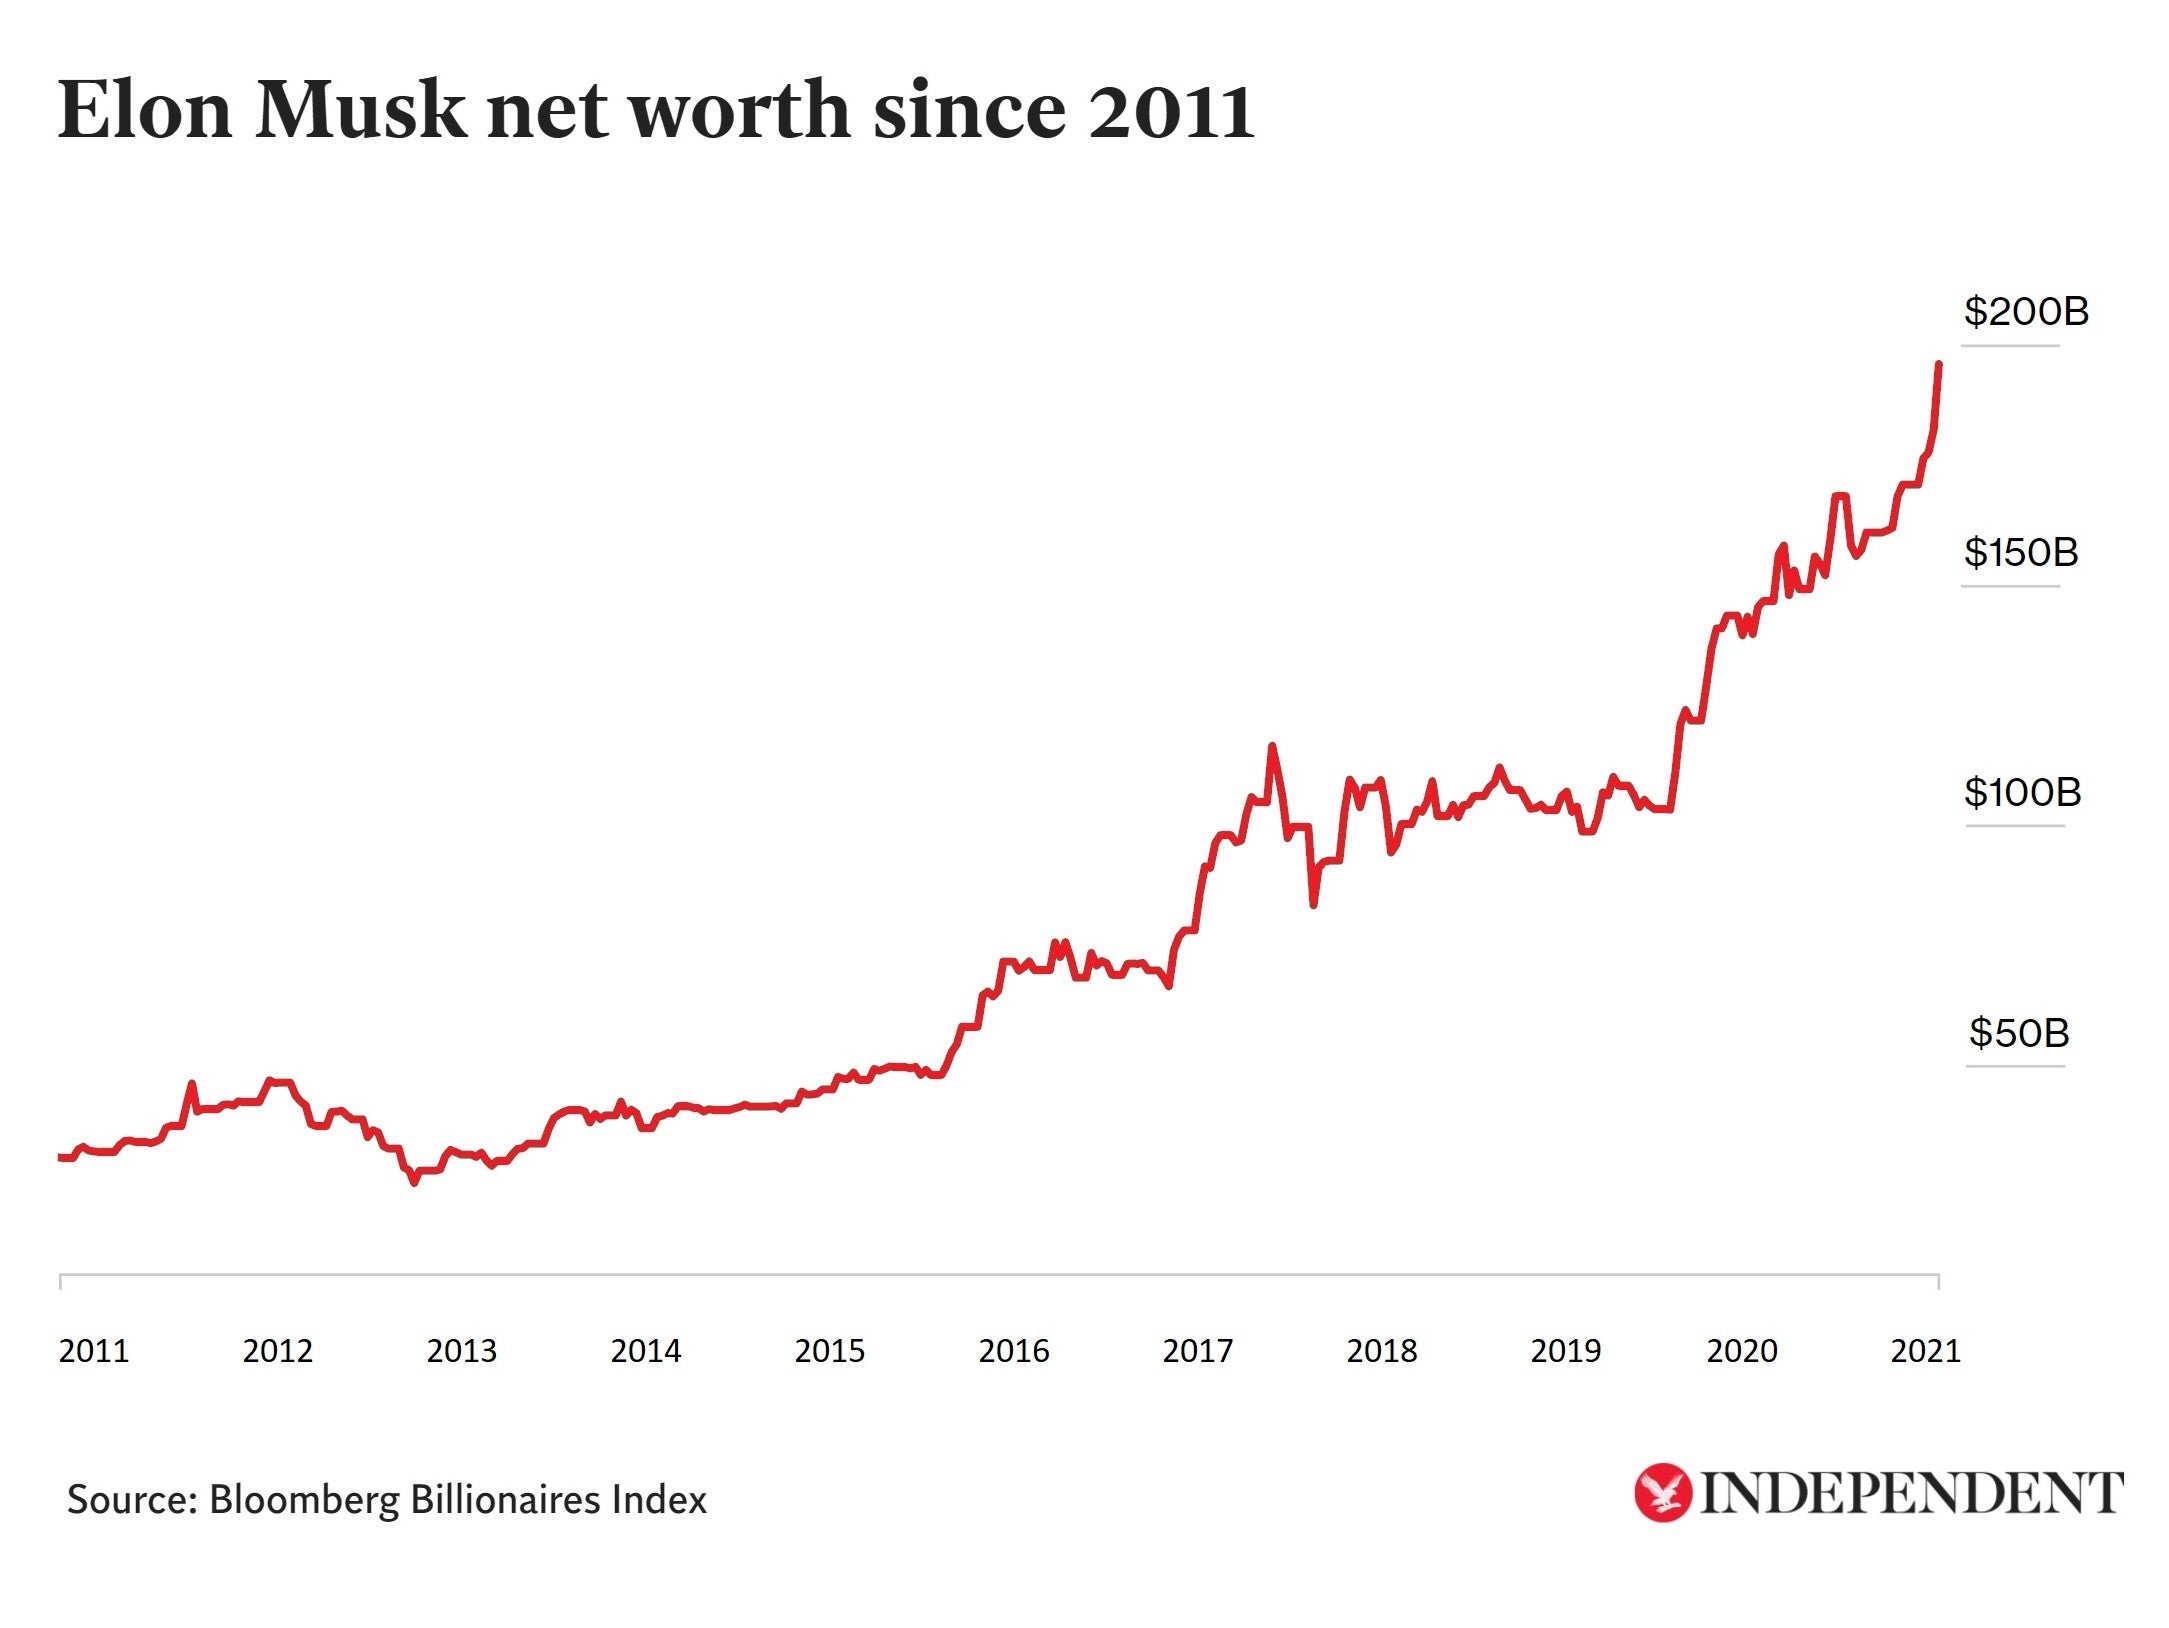
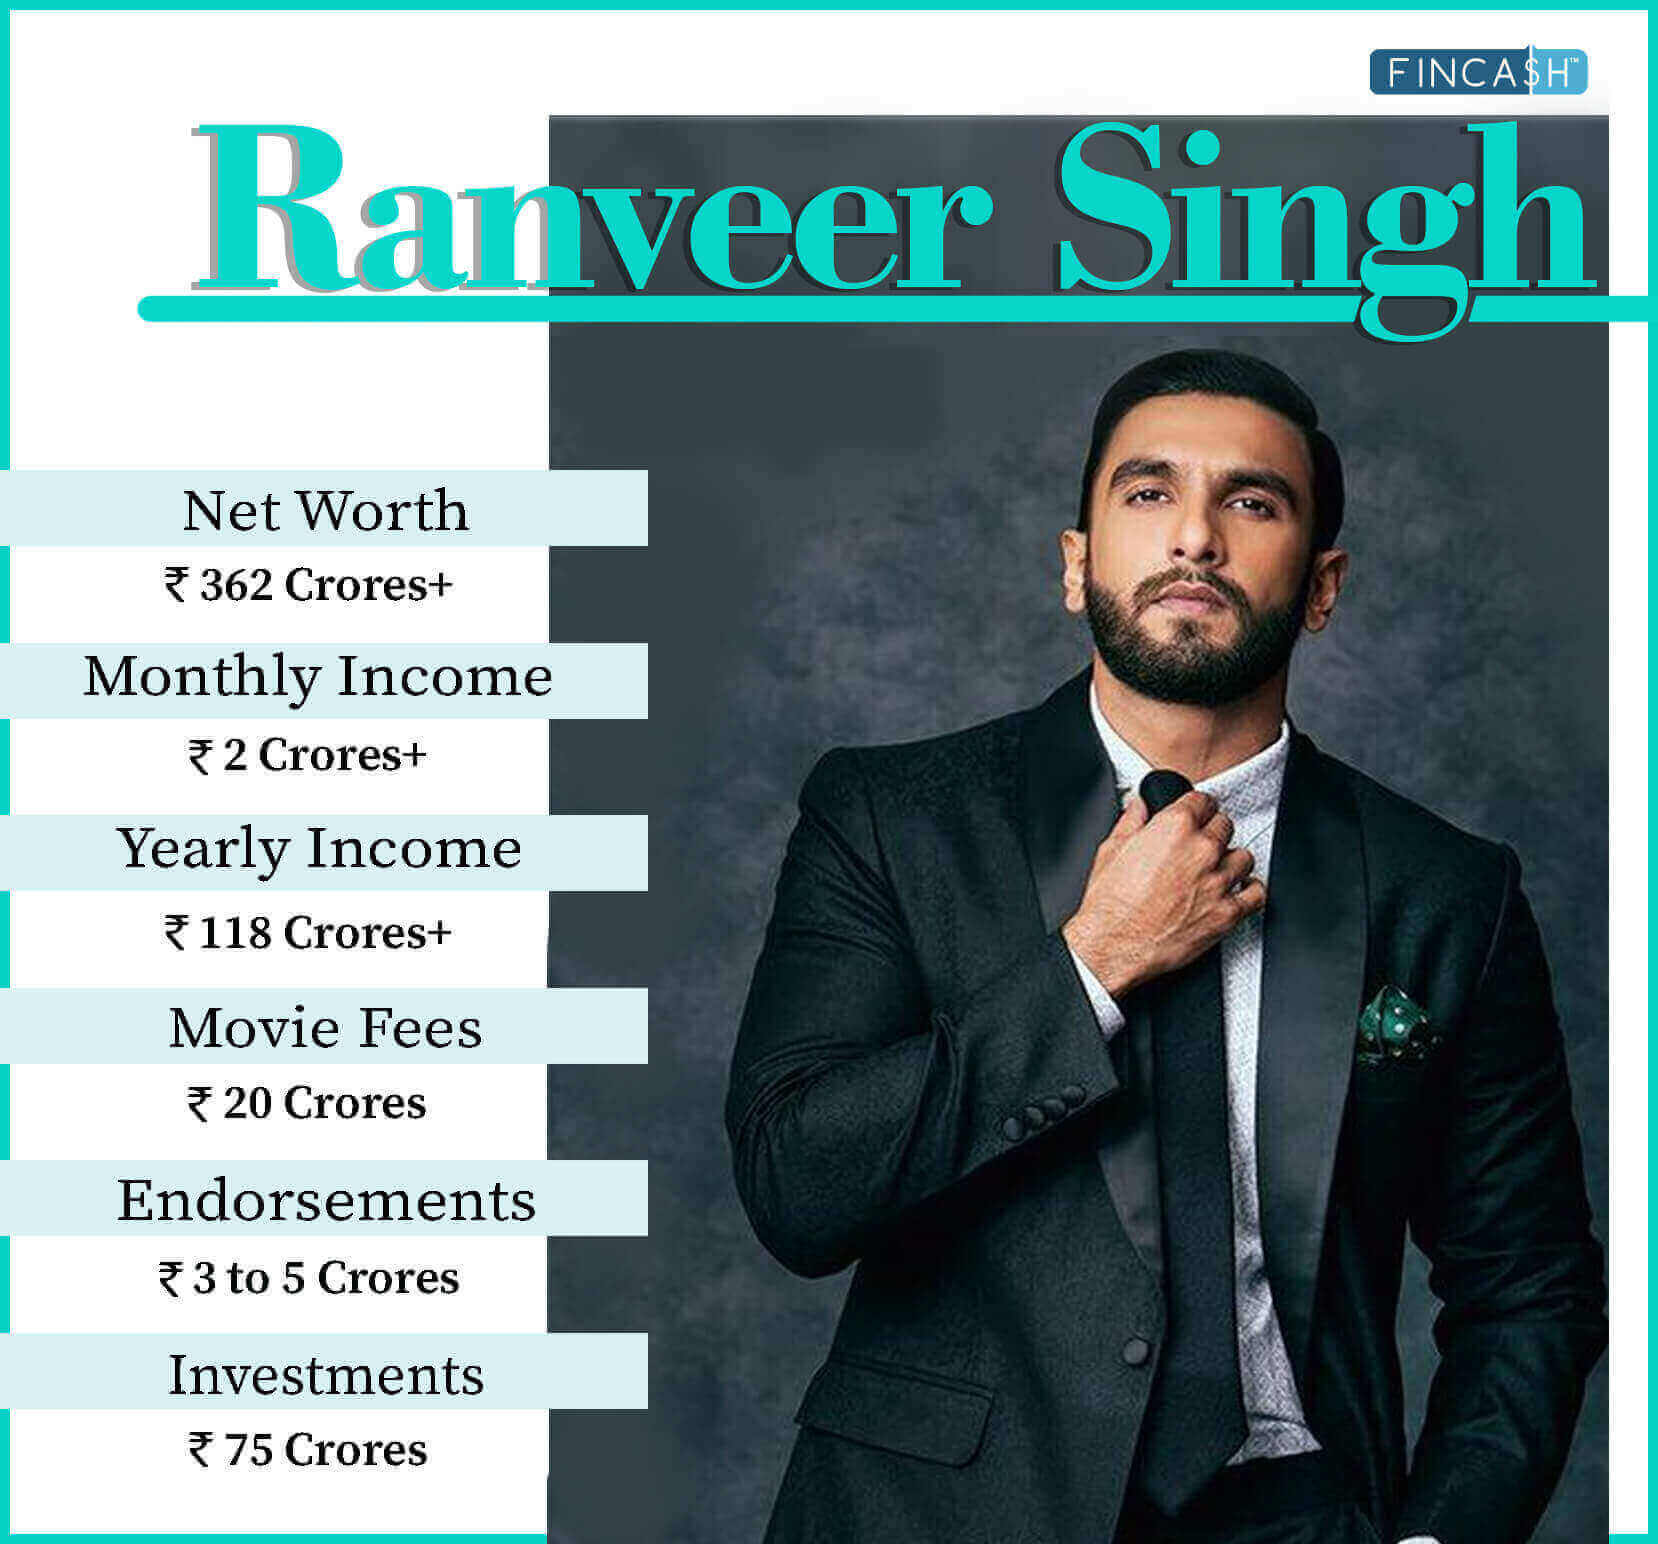
Net worth is the mathematical difference between your total assets and your total liabilities, serving as a snapshot of your current financial health. By calculating the value of everything you own minus everything you owe, you establish a primary metric for tracking long-term wealth accumulation, measuring progress toward financial goals, and informing future investment decisions.
Understanding the Core Components of Net Worth
To arrive at an accurate explanation of net worth, one must first master the distinction between assets and liabilities. This balance sheet approach is the foundation of personal financial accounting.
Defining Assets: What You Own
Assets represent anything of monetary value that you possess. In a personal net worth statement, these are typically categorized into two types: liquid and non-liquid.
- Liquid Assets: These include cash, savings accounts, money market accounts, and certificates of deposit. They are easily converted into cash without significant loss of value.
- Non-Liquid Assets: This category encompasses real estate, retirement accounts (such as a 401(k) or IRA), brokerage investments, business equity, and personal property like vehicles or jewelry.
When valuing non-liquid assets, accuracy is paramount. For example, a home should be valued based on its current fair market value—the price it would realistically fetch in the 2026 market—rather than its original purchase price. Using outdated figures or sentimental estimates leads to a distorted view of your financial position.
Defining Liabilities: What You Owe
Liabilities represent all outstanding financial obligations. This includes both short-term debt and long-term commitments.
- Short-Term Debt: Credit card balances, personal loans, and unpaid utility bills or taxes due within a single fiscal year.
- Long-Term Debt: Mortgages, student loans, and auto loans. These are characterized by extended repayment schedules and usually carry specific interest rates that impact your total liability over time.
The Calculation Methodology
The fundamental formula for net worth is: Total Assets – Total Liabilities = Net Worth.
While the formula is simple, the process of data collection is where most errors occur. To ensure an accurate explanation, you must maintain a consistent schedule for updates. Most financial planners recommend calculating your net worth once every six to twelve months. This cadence provides enough time to see the impact of debt repayment or asset appreciation while remaining frequent enough to catch discrepancies or errors in your financial tracking.
Common Pitfalls in Calculation
A frequent mistake individuals make is "asset inflation," where they estimate the value of possessions based on replacement cost rather than resale value. Personal items, unless they are collectibles or precious metals, often depreciate significantly.
Another common error involves the omission of interest-heavy debt. When listing liabilities, you must record the payoff amount, not just the principal. For a mortgage, this requires contacting your lender to receive an official payoff statement, as the principal balance listed on a standard monthly statement may not account for accrued daily interest or pending escrow adjustments.
Table: Assets vs. Liabilities Categorization
| Asset Category | Description | Liability Category | Description |
|---|---|---|---|
| Cash/Cash Equivalents | Savings, checking, CDs | Revolving Debt | Credit cards, HELOCs |
| Investments | Stocks, bonds, mutual funds | Mortgage/Real Estate | Primary residence, rental loans |
| Retirement Accounts | 401(k), 403(b), IRA | Consumer Loans | Auto loans, personal loans |
| Real Property | Primary home, land | Education Debt | Federal/private student loans |
| Personal Property | Vehicles, art, collectibles | Other Obligations | Tax liens, medical debt |
Why Net Worth Matters in 2026
In the current economic climate of 2026, net worth serves as a more reliable indicator of stability than annual income. Income fluctuates, and high earners can have low net worth if their expenditures match or exceed their earnings. Conversely, a moderate earner with consistent savings and debt reduction strategies can build a substantial net worth over time.
Financial institutions and lenders often use net worth as a proxy for financial maturity. When applying for significant credit lines or specialized investment opportunities, your net worth statement provides evidence of your ability to manage capital, mitigate risk, and maintain a sustainable balance sheet.
Practical Steps for Maintaining an Accurate Statement
- Consolidate Records: Gather your latest bank statements, investment account logins, and loan balance documents.
- Verify Market Values: Use reputable real estate valuation tools or recent appraisals to estimate the fair market value of your home. Use current stock market closing prices for your investment holdings.
- Subtract Liabilities: Ensure you are calculating the total amount required to settle your debts today.
- Audit the Trends: Compare your current net worth to your previous reporting period. Ask yourself: "Did my net worth increase because I paid down debt, or because my assets appreciated?" Understanding the source of growth is as important as the growth itself.
- Address Discrepancies: If your net worth has dropped significantly, investigate whether this was due to market volatility or increased spending.
Frequently Asked Questions
Does a negative net worth mean I am failing financially? No. A negative net worth is common for younger professionals who have recently taken on student loan debt or mortgages. It indicates that your current liabilities exceed your assets, but it does not account for future earning potential or the long-term value of the assets you are financing.
Should I include my vehicle in my net worth? Yes, but you must be realistic about its value. Use a standard valuation tool to determine the private party resale value, not the dealership trade-in value, and ensure you subtract any remaining loan balance on the vehicle.
How do taxes impact my net worth calculation? Taxes are a crucial, often overlooked factor. If you hold significant assets in tax-deferred accounts like a 401(k), remember that those funds are subject to future income taxes upon withdrawal. Some sophisticated investors subtract a "tax liability" percentage from their retirement account totals to reflect the true "after-tax" net worth.
Does net worth change daily? Yes. Because the value of assets—particularly stocks and real estate—and the accrual of interest on debt occur continuously, your net worth is technically a moving target. However, for personal tracking purposes, a periodic "snapshot" is more useful than daily monitoring.
What is the best tool to track net worth? Many people use spreadsheets for complete control, while others prefer automated financial aggregators. Regardless of the tool, ensure it is secure, uses two-factor authentication, and allows you to manually override automated asset valuations if the data is incorrect.
Recommendations for Ongoing Financial Management
To maintain a high level of accuracy, avoid the temptation to "pad" your asset values. A conservative approach is always superior in financial planning. If you are uncertain about the value of a specific asset—such as a piece of property or a private business interest—use the lower end of a professional valuation range.
Moving forward, your primary action should be to create a dedicated ledger. Whether digital or physical, ensure it is updated annually at a minimum. Focus on the trend line over five or ten years rather than month-to-month fluctuations. By treating your personal finances with the same rigor as a corporate balance sheet, you provide yourself with the data needed to make informed, objective decisions about your economic future.