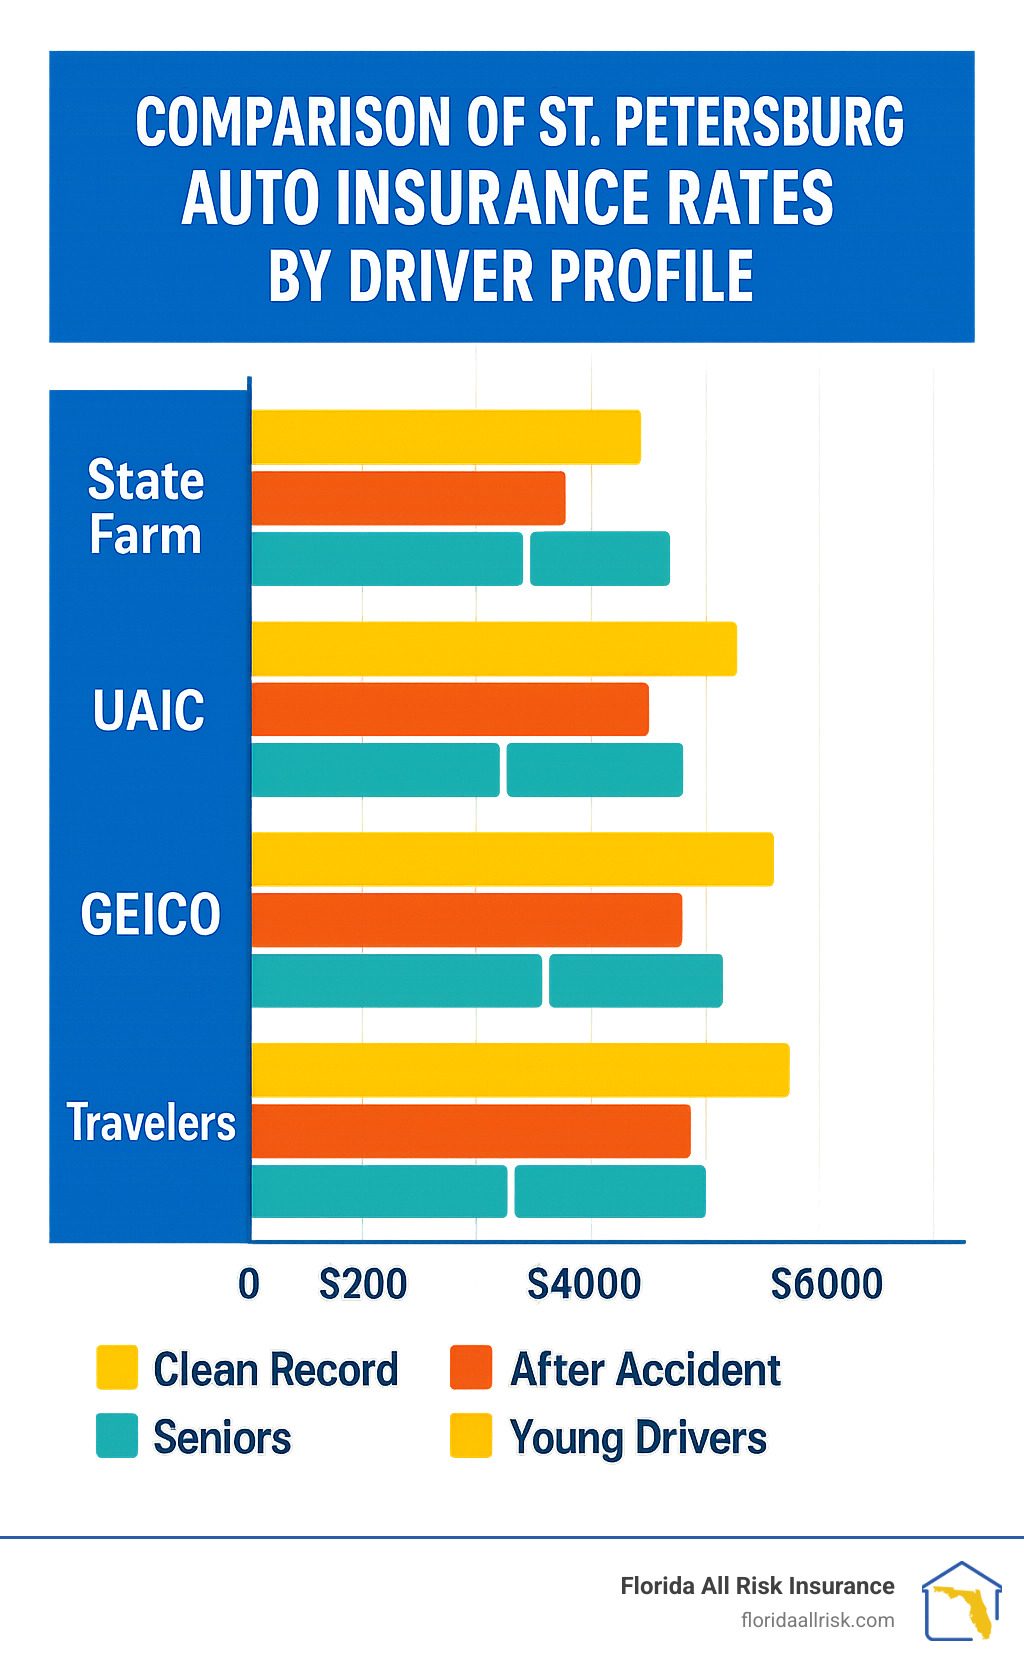
An all risk auto insurance website is a digital platform that allows vehicle owners to research, purchase, and manage "all risk" (or open perils) coverage. Unlike standard policies that only cover specific named events, these portals facilitate comprehensive protection against all damages except those explicitly excluded, offering streamlined quoting, claims processing, and policy management.
Understanding "All Risk" Auto Insurance in the 2026 Market
In the current 2026 insurance landscape, the term "all risk" has become increasingly synonymous with high-tier comprehensive coverage. While traditional policies often list "named perils"—specific events like fire or theft that are covered—an all risk policy operates on the inverse logic. It covers every conceivable cause of loss to your vehicle unless the insurance contract specifically lists it as an exclusion.
Navigating an all risk auto insurance website requires an understanding of this fundamental shift in coverage philosophy. In 2026, these websites have evolved from simple brochure-style pages into complex, AI-driven ecosystems. They integrate real-time data from telematics, vehicle sensors, and public records to provide a nuanced view of risk. When a consumer visits these platforms, they are not just looking for a price; they are looking for a guarantee that their asset is protected against the unpredictable.
Open Perils vs. Named Perils
The primary value proposition of an all risk website is the "open perils" framework. On the website’s "Coverage Details" or "Policy Disclosure" page, users will find that the burden of proof often shifts. Under a named peril policy, the policyholder must prove that the damage was caused by a listed event. Under an all risk policy, if the damage occurs, it is generally covered unless the insurer can prove it falls under a specific exclusion like wear and tear, mechanical breakdown, or intentional acts.
Key Features of a High-Quality All Risk Auto Insurance Website
A top-tier insurance portal in 2026 is defined by its transparency and user autonomy. When evaluating an all risk auto insurance website, users should look for specific technical functionalities that indicate a robust service provider.
Real-Time Premium Adjustment Tools
Modern websites feature interactive "sliders" or configuration engines. These allow users to see exactly how changing a deductible or adding an endorsement (such as "new car replacement" or "gap coverage") impacts their monthly premium in real time. This transparency is critical for all risk policies where the baseline cost is higher due to the breadth of coverage.
Integrated Telematics Dashboards
By 2026, most all risk providers utilize telematics—data transmitted from the vehicle regarding driving behavior. A high-quality website provides a secure login area where users can view their "safety score," see how their driving habits influence their rates, and receive tips on how to lower their premiums. This level of data democratization helps users feel more in control of their insurance costs.
AI-Powered Document Verification
The enrollment process on an all risk website should be frictionless. Advanced portals use Optical Character Recognition (OCR) and AI to scan uploaded driver’s licenses and vehicle registration documents. This reduces manual entry errors and speeds up the "binding" of the policy, allowing drivers to move from a quote to a fully active all risk policy in minutes.
How to Navigate the Online Quote Process
Securing a quote on an all risk auto insurance website involves a specific sequence of data entry and verification. Because all risk policies offer broader protection, the underwriting process is often more detailed than that of a basic liability policy.
- Vehicle Identification: You will typically start by entering your Vehicle Identification Number (VIN). The website’s backend will pull the vehicle's history, safety features, and current market value to assess the potential "all risk" exposure.
- Usage Profiling: The portal will ask for your estimated annual mileage and the primary use of the vehicle (commuting, pleasure, or business). In 2026, many websites also offer a "pay-per-mile" option within their all risk packages.
- Driver History Integration: Most modern websites automatically pull your driving record from the DMV and your claims history from databases like LexisNexis. You should verify this information for accuracy as it significantly impacts the "all risk" premium calculation.
- Selecting Exclusions and Endorsements: While the policy is "all risk," you may have the option to add specific riders for items like custom equipment or high-end audio systems that might otherwise be limited under standard policy language.
- Identity Verification: Before a final binder is issued, the website will use multi-factor authentication (MFA) and potentially biometric verification to ensure the person applying matches the documentation provided.
Technical Requirements and Documentation
To successfully use an all risk auto insurance website, you must have certain digital assets and meet specific prerequisites. The digital nature of 2026 insurance means that paper-based processes are largely obsolete.
- Digital Title or Registration: A high-resolution scan or digital copy of your vehicle's ownership documents.
- Proof of Prior Coverage: Most all risk websites require a digital upload of your previous "Declarations Page" to verify you haven't had a gap in coverage, which can lead to higher rates.
- Photos of the Vehicle: For all risk policies, insurers often require a "pre-inspection" performed via the website’s mobile interface. You will be prompted to take 360-degree photos of the car to document its current condition, ensuring that pre-existing damage isn't claimed later under the new all risk policy.
- Financial Account Linking: To finalize the policy, you will need to link a bank account or credit card. Many websites in 2026 also support digital wallets and cryptocurrency for premium payments.
Comparison of All Risk Insurance Platform Types
Not all websites offering all risk coverage are built the same. Understanding the distinction between direct carriers, agencies, and aggregators is essential for making an informed choice.
| Platform Type | Best For | Primary Advantage | Limitation |
|---|---|---|---|
| Direct Carrier Website | Brand Loyalists | Faster claims processing and direct communication with the underwriter. | Only shows one company's products and pricing. |
| Independent Agency Portal | Personalized Service | Access to multiple all risk carriers with a human advisor available via chat. | Quotes may take longer to generate as they require agent review. |
| Comparison Aggregator | Price Shoppers | Ability to compare "all risk" vs. "named peril" quotes from 10+ companies side-by-side. | Often sells your data to third parties; may show "estimated" rather than final rates. |
| Manufacturer-Linked Site | Owners of New EVs/AVs | Seamless integration with vehicle sensors; often includes "embedded" all risk coverage. | Coverage is often tied strictly to the vehicle brand and cannot be ported. |
Managing Your Policy and Filing Claims Online
The true test of an all risk auto insurance website occurs when you need to use the coverage. The claims portal is the most critical component of the user experience.
The Digital Claims Lifecycle
When an incident occurs—whether it’s a collision, hail damage, or vandalism—the website should allow you to start a claim immediately. In 2026, this usually involves a "guided claim" flow. You upload photos of the damage, and AI algorithms estimate the repair costs within seconds. For all risk policies, the website should clearly state if the cause of loss is being investigated or if it has been automatically approved based on the "open perils" clause.
Real-Time Repair Tracking
Once a claim is approved, the website acts as a hub between you, the insurance company, and the repair facility. You should be able to log in to see the status of parts orders, estimated completion dates, and digital payments made to the mechanic.
Policy Endorsements and Renewals
Updating your policy should not require a phone call. An effective all risk website allows you to add a new driver, change your primary address, or increase your limits through a self-service dashboard. During renewal periods, the site should provide a summary of how your "all risk" premiums have changed based on market conditions and your individual risk profile over the past year.
Common Pitfalls and Troubleshooting Digital Insurance Platforms
While the transition to digital-first insurance has many benefits, users often encounter specific hurdles when dealing with all risk websites.
- Incompatibility with Older Browsers: Many 2026 insurance portals use high-level encryption and WebGL for interactive tools. Using an outdated browser may result in "broken" quote forms or the inability to upload photos.
- Data Mismatches: If the information you enter doesn't perfectly match the data pulled from the DMV, the website may "lock" your quote. In these cases, look for a "Live Chat" or "Secure Message" feature to resolve the discrepancy with a human representative.
- Mobile vs. Desktop Discrepancies: Some all risk websites are "mobile-optimized" to the point where the desktop version lacks certain features, like the camera-based pre-inspection tool. Always check if the insurer recommends using their dedicated app for the initial setup.
- Overlooking the Fine Print: Because "all risk" sounds exhaustive, users often skip reading the exclusions. Even on a high-tech website, you must locate the "Policy Form" or "Terms of Service" to identify what is not covered.
Legal and Financial Considerations for 2026
When using an all risk auto insurance website, you are entering into a legally binding financial contract. It is important to recognize the jurisdictional limits of these platforms. An all risk policy in one state or country may have different mandatory exclusions than in another.
Furthermore, the "all risk" nature of the policy typically makes it more expensive than "Liability Only" or "Collision/Comprehensive" splits. Consumers should use the website's financial tools to ensure the premium fits their budget. Most websites now include "Financial Health" indicators that suggest coverage levels based on your vehicle's current depreciated value.
Disclaimer: Insurance regulations and policy terms vary significantly by jurisdiction. Always consult with a licensed insurance professional and read your specific policy documents before making a purchase decision.
Frequently Asked Questions
Is "all risk" the same as "full coverage"?
Not exactly. "Full coverage" is a colloquial term that usually refers to a combination of liability, collision, and comprehensive insurance. "All risk" is a specific technical term meaning the policy covers all perils except those excluded. While an all risk website might market itself as providing "full coverage," the all risk framework is actually more protective because it covers "unknown" risks that aren't specifically named.
Why is my quote higher on an all risk website than on a standard site?
All risk policies carry higher premiums because the insurer is taking on more uncertainty. Since they agree to cover everything not excluded, they are responsible for unusual or rare events that a "named peril" policy would ignore. The website’s premium reflects this broader transfer of risk from you to the insurance company.
Can I buy an all risk policy for an older car online?
Most all risk websites have an age limit for vehicles, often 10 to 15 years. For older or classic cars, the website may redirect you to a "stated value" or "agreed value" policy, which functions differently than a standard all risk policy.
How do I know if an all risk insurance website is legitimate?
Verify the company’s license through your local government insurance regulator (such as the NAIC in the United States). Legitimate websites will always provide their license number and physical address in the footer of the page. Additionally, ensure the site uses "https" and has a valid SSL certificate before entering any personal or financial data.
Can I cancel my policy through the website?
Yes, by 2026, most jurisdictions require insurance companies to allow online cancellations if they allow online sign-ups. However, be aware that cancelling an all risk policy may result in a "short-rate" penalty or a lapse in coverage that could make your next policy more expensive.
Final Recommendation for Users
When choosing an all risk auto insurance website, prioritize platforms that offer full transparency regarding exclusions. The most sophisticated interface is useless if it hides the "fine print." Use the interactive tools to test different scenarios—such as a higher deductible—to find the balance between comprehensive protection and affordability. Before finalizing any policy, download the draft "Evidence of Insurance" to ensure the "all risk" designation is explicitly stated in the policy language.