Able Auto Insurance operates as a specialized independent agency primarily serving the Mid-Atlantic region, with a heavy focus on North Carolina and Virginia. Known for providing "non-standard" auto insurance, they cater to drivers who struggle to find coverage through mainstream carriers due to high-risk profiles, previous traffic violations, or the need for specific state filings like SR-22s or FR-44s.
Understanding the Role of Able Auto Insurance in 2026
To accurately evaluate Able Auto Insurance, one must first distinguish between an insurance carrier and an insurance agency. Able Auto Insurance functions as an independent agency. This means they do not underwrite the policies themselves; instead, they partner with various insurance companies—such as National General, Progressive, or Foremost—to find policies that fit the specific needs of their clientele.
In the 2026 insurance landscape, the "non-standard" market has become increasingly complex. With rising vehicle repair costs and more stringent state regulations regarding uninsured motorists, agencies like Able play a critical role. They act as intermediaries for drivers who may have been denied coverage elsewhere, providing a bridge to legal compliance and financial protection on the road.
The Niche: High-Risk and Specialized Filings
The primary reason consumers seek out Able Auto Insurance is their expertise in high-risk underwriting. While a "preferred" driver with a perfect 10-year record might find lower rates at a direct-to-consumer giant, a driver with a recent DUI, multiple speeding tickets, or a lapse in coverage often finds those same giants either prohibitively expensive or unwilling to offer a quote. Able specializes in these scenarios, particularly focusing on:
- SR-22 Filings: A financial responsibility certificate required by the state to prove you carry the minimum liability insurance.
- FR-44 Filings: Common in Virginia, this requires significantly higher liability limits than a standard policy, usually following a DUI or DWI conviction.
- Non-Owner Policies: For individuals who do not own a vehicle but need to maintain a license or fulfill a legal requirement for insurance.
Detailed Coverage Options Provided by Able Auto Insurance
Because Able Auto Insurance works with multiple carriers, the breadth of coverage available is quite wide. However, most policies facilitated through their agency fall into several core categories required by North Carolina and Virginia law.
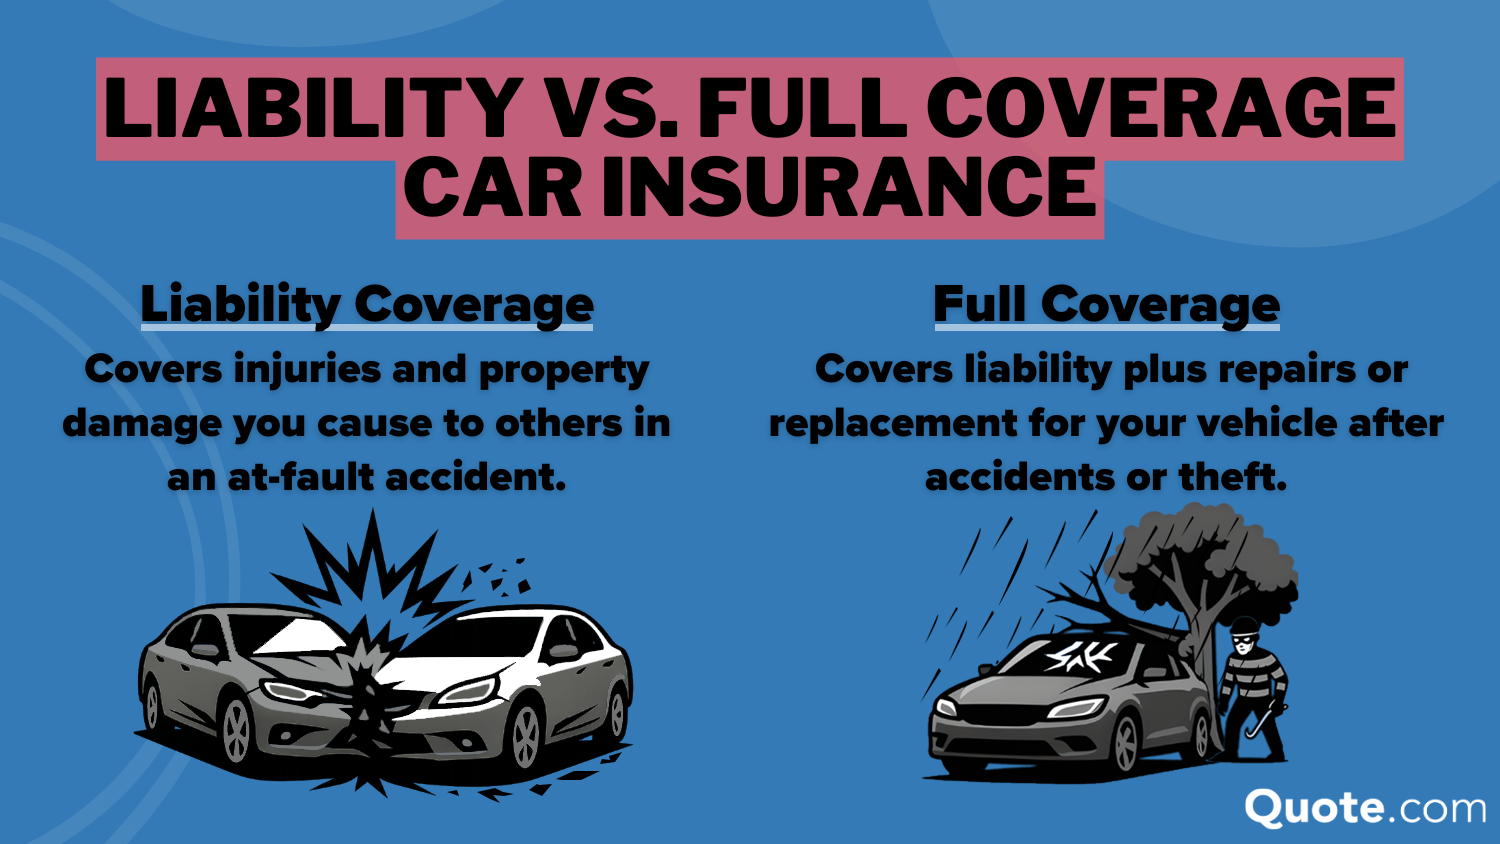
1. Liability Insurance (Bodily Injury and Property Damage)
This is the foundation of any auto policy. In 2026, state minimums remain the baseline, but Able agents typically recommend higher limits to protect personal assets.
- Bodily Injury Liability: Covers medical expenses, lost wages, and legal fees for the other party if you are at fault in an accident.
- Property Damage Liability: Pays for the repair or replacement of the other driver’s vehicle or other property (like fences or storefronts) damaged in an at-fault accident.
2. Physical Damage Coverage (Collision and Comprehensive)
For drivers with newer vehicles or those with an active auto loan, physical damage coverage is essential.
- Collision Insurance: Covers damage to your own vehicle resulting from a collision with another car or object, regardless of fault.
- Comprehensive Insurance: Protects against "acts of God" or non-collision events, including theft, vandalism, fire, and weather-related damage (hail, flooding). Given the increase in extreme weather events noted through 2026, comprehensive coverage has seen a higher attachment rate even in the non-standard market.
3. Uninsured and Underinsured Motorist Coverage (UM/UIM)
In states like North Carolina, UM coverage is often mandatory. It protects you if you are hit by a driver who either has no insurance or whose limits are too low to cover your total damages. This is particularly vital for Able’s customer base, as they often operate in demographic areas where insurance lapses are more statistically frequent.
4. Medical Payments (MedPay)
MedPay is a no-fault coverage that pays for medical or funeral expenses for you and your passengers following an accident. Unlike liability insurance, this covers the policyholder regardless of who caused the accident.
5. Specialized Non-Owner Policies
Able Auto Insurance is a leading provider of non-owner auto insurance. This is a specific contract designed for people who drive borrowed cars or need to reinstate a driver's license but do not have a registered vehicle in their name. It provides liability protection but does not cover physical damage to the vehicle being driven.
2026 Cost Overview: What to Expect
Auto insurance premiums across the United States have faced upward pressure through the mid-2020s due to "social inflation" (higher jury awards), increased technology in car parts, and a shortage of skilled labor in repair shops. For a non-standard agency like Able, costs are inherently higher than the national average because the risk pool is higher.
Factors Influencing Your Premium at Able
When you request a quote from Able Auto Insurance in 2026, their partner carriers use a variety of data points to determine your rate:
- Driving Record: This remains the most significant factor. A single DUI in 2026 can increase premiums by 60% to 100% in the Virginia and North Carolina markets.
- Credit-Based Insurance Scores: While controversial, many carriers Able represents still use credit history as a predictor of risk.
- Lapse in Coverage: If you have gone more than 30 days without insurance, you are categorized into a higher-risk tier.
- Vehicle Usage: How many miles you drive and whether the vehicle is used for commuting or business.
Estimated Cost Comparison (Monthly Averages)
The following table provides an estimate of monthly premiums for different driver profiles in the 2026 Mid-Atlantic market when shopping through a non-standard agency like Able.
| Driver Profile | Policy Type | Estimated Monthly Premium (2026) |
|---|---|---|
| Clean Record (Standard) | State Minimum Liability | $65 – $95 |
| One At-Fault Accident | Full Coverage (Coll/Comp) | $180 – $240 |
| DUI Conviction (SR-22) | State Minimum Liability | $210 – $350 |
| DUI Conviction (FR-44 - VA) | High-Limit Liability (100/300/50) | $300 – $500 |
| Non-Owner | Liability Only | $40 – $75 |
Note: These are estimates based on market trends in 2026 and vary significantly by ZIP code and specific carrier underwriting.
Customer Reviews and Reputation Analysis
Reviews for Able Auto Insurance are generally polarized, which is common for agencies specializing in the high-risk market. To provide a balanced view, we have categorized feedback based on recurring themes found in consumer reports and digital forums.
The Positives: Why Customers Stay
- Ease of Filing: Customers frequently praise Able for their efficiency in filing SR-22 and FR-44 forms with the DMV. In many cases, these filings are processed electronically the same day, allowing drivers to regain their licenses quickly.
- Agent Accessibility: Unlike larger carriers that rely heavily on AI chatbots, Able maintains a human-centric approach. Reviewers often mention specific agents who helped them navigate the complexities of "Point Systems" (like the North Carolina SDIP).
- Acceptance of All Drivers: The most common positive sentiment is gratitude for providing coverage when "no one else would."
The Negatives: Common Complaints
- Agency Fees: As an independent agency, Able may charge an agency fee or "broker fee" in addition to the carrier’s premium. Some customers find these fees frustrating, especially when they are non-refundable.
- Price Volatility: Because they deal with high-risk carriers, customers often see significant premium hikes at renewal if another ticket or accident occurs.
- Limited Digital Tools: Compared to national brands like Geico or State Farm, Able’s online portal and mobile app capabilities are reported to be more basic, with some functions still requiring a phone call to an agent.
Comparing Able to National High-Risk Carriers
When shopping for insurance in 2026, it is useful to see how a regional agency like Able stacks up against national companies that also target the high-risk market, such as The General or Bristol West.
- Able vs. The General: The General has a massive national advertising presence and a highly integrated mobile app. However, Able often provides a more "local" feel with agents who understand the specific nuances of North Carolina’s complex insurance laws, such as the Reinsurance Facility (NCRF).
- Able vs. Progressive: Progressive is one of the carriers Able might actually sell. The advantage of going through Able is that the agent can compare Progressive's quote against several other smaller, niche carriers that you might not be able to access directly.
How to Obtain a Quote and File a Claim
The process at Able Auto Insurance is designed for speed, particularly for those needing immediate proof of insurance for the DMV.
Getting a Quote
To get an accurate quote in 2026, you will need:
- Driver’s License Numbers: For all household members.
- Vehicle Identification Number (VIN): For all cars to be insured.
- Violation Dates: Exact dates of any accidents or tickets in the last 3-5 years.
- Prior Insurance Info: The name of your last carrier and the date your coverage ended.
The Claims Process
Since Able is the agent and not the insurer, you do not file a claim with Able. Instead, you file a claim with the specific carrier that issued your policy (e.g., National General).
- Step 1: Contact the carrier’s claims hotline (usually 24/7).
- Step 2: Provide the policy number found on your Able Insurance ID card.
- Step 3: An adjuster from the carrier will be assigned to evaluate the damage.
- Step 4: Able agents can often act as advocates if you encounter communication issues with the carrier's claims department.
Frequently Asked Questions
Does Able Auto Insurance offer "Instant" SR-22s?
Yes, in many cases. Able Auto Insurance specialized in 2026 electronic filing systems that connect directly to the North Carolina and Virginia DMV databases. Once the policy is bound and the first payment is made, the filing is typically transmitted within minutes to a few hours.
Can I get a policy with Able if my license is currently suspended?
Yes. Able is specifically structured to help drivers in this situation. They can provide the necessary insurance (often a non-owner policy or a standard policy with an SR-22) that the DMV requires as a prerequisite for license reinstatement.
What happens if I move out of North Carolina or Virginia?
Able is primarily licensed in the Mid-Atlantic region. If you move to a state where they are not licensed, you will need to find a new agent or carrier. It is crucial to set up your new policy before canceling your Able policy to avoid a lapse in coverage, which can trigger DMV penalties.
Are there discounts available for high-risk drivers?
While limited, discounts do exist in the non-standard market in 2026. These may include "Paid in Full" discounts, "E-signature" discounts, and sometimes a "Safe Driver" discount if you complete a state-approved defensive driving course.
Why is my quote through Able higher than the price I saw online?
Initial online quotes are often "teaser" rates based on self-reported data. Once the agent runs your official Motor Vehicle Report (MVR) and Comprehensive Loss Underwriting Exchange (CLUE) report, the price may adjust to reflect your actual driving history and claims record.
Final Recommendation: Is Able Auto Insurance Right for You?
Able Auto Insurance is an excellent choice for drivers who fall outside the "preferred" market. If you have a clean driving record and a high credit score, you will likely find more competitive rates and better digital tools with a national direct carrier.
However, if you are navigating a license suspension, need an FR-44 in Virginia, or have been dropped by your previous insurer, Able Auto Insurance offers the specialized expertise and carrier access needed to get you back on the road legally. Their value lies not in being the cheapest option for everyone, but in being a reliable option for those who are currently "uninsurable" by standard market definitions.
To proceed, it is recommended to call an Able agent directly rather than relying solely on automated online tools, as high-risk underwriting often requires the nuance of a human agent to find the most favorable carrier placement.