The term "2019 parent auto insurance program" refers to specific marketing initiatives, internal corporate discounts, or localized safe-driving incentive programs launched by insurance carriers around 2019 to mitigate the risks associated with teen drivers. These programs typically focused on bundling young drivers under a parent’s policy, leveraging telematics or academic performance to reduce premiums during a period of high insurance costs.
Understanding the Context of the 2019 Automotive Landscape
To understand the 2019 parent auto insurance initiatives, one must look at the climate of the automotive insurance industry during that calendar year. In 2019, insurance carriers were facing rising loss ratios, largely driven by the increasing complexity of vehicle repairs and the high accident frequency among novice drivers. Data from the National Highway Traffic Safety Administration (NHTSA) consistently highlighted that drivers aged 16–19 were significantly more likely to be involved in fatal crashes than older drivers.
Insurance companies responded by refining their "good student" discounts and expanding "parent-student" driver programs. These programs were rarely unified national mandates; instead, they were localized or carrier-specific contractual arrangements that allowed parents to integrate their teenage children into existing policies under specific safety covenants. By 2019, many of these programs had pivoted toward digital integration, using mobile applications to monitor driving habits—a precursor to the sophisticated telematics used in 2026.
Eligibility Requirements and Prerequisites
For a parent in 2019 to qualify for a parent auto insurance program, several stringent requirements were generally enforced. These were designed to ensure that the risk profile of the teenager was being actively managed by the policyholder.
- Primary Residency: The teenager was almost universally required to reside in the same household as the parent. Insurance carriers define "household" strictly; if a student moved away to university, the policy often had to be restructured, sometimes excluding the driver to lower premiums or keeping them as a "student away at school."
- Academic Performance: Many 2019 programs heavily incentivized academic success. A "Good Student Discount" usually required a student to maintain a "B" average (or a 3.0 GPA) or to rank in the top 20% of their class. Proof, such as a report card or an official letter from the school registrar, was a mandatory submission requirement.
- Driver Safety Training: Completion of a defensive driving course—often one certified by the state or a recognized third-party organization—was frequently a prerequisite for program entry. This served to lower the "risk score" assigned to the teenager during the policy underwriting process.
- Vehicle Assignment: Insurance companies in 2019 often mandated that the teenager be explicitly listed as a driver on a specific vehicle within the household fleet, rather than having "occasional" status on every vehicle, to prevent premium under-collection.
Mechanisms of Coverage and Premium Mitigation
The core of these programs was the mitigation of the "teenager surcharge." Because teenagers lack historical driving data, carriers statistically assign them the highest risk profile, leading to significant premium spikes.
Telematics and Behavior Monitoring
By 2019, the integration of telematics (usage-based insurance) had moved from a niche offering to a central feature of parent-teen programs. Parents could install a plug-in device or a smartphone app that monitored:
- Hard Braking: Frequent, sudden stops indicating distracted driving or lack of awareness.
- Speeding: Exceeding local speed limits consistently.
- Time-of-Day Restrictions: Monitoring late-night driving, which is statistically more dangerous for novice drivers.
While some parents found these programs intrusive, they provided the most substantial discount—sometimes 15% to 30% off the teenage driver’s portion of the premium. By 2026, these systems have evolved significantly, but the fundamental mechanics established in 2019—using data to prove safety—remain the industry standard.
Comparison Table: 2019 Program Features vs. Modern Expectations
The following table outlines how standard parent-teen insurance programs functioned in 2019 versus the developments expected by 2026.
| Feature | 2019 Program Standard | 2026 Expectation |
|---|---|---|
| Monitoring Method | Plug-in OBD-II devices or early apps | AI-integrated smartphone telematics |
| Academic Discount | Flat rate based on GPA | Variable based on school performance |
| Data Privacy | Basic opt-in disclosures | Advanced GDPR-compliant consent |
| Primary Incentive | Premium reduction | Premium reduction + safety coaching |
| Underwriting | Based on age/gender/GPA | Based on real-time behavior patterns |
The Impact of Localized Legislation and Carrier Variations
It is critical to note that the "2019 parent auto insurance program" was not a federal law or a singular product. Insurance in the United States is regulated at the state level. Consequently, a program offered by a national carrier in Florida might differ significantly from the same company’s offering in California or New York.
In some jurisdictions, state insurance commissioners implemented caps on how much a parent’s policy could increase when a teenager was added. In others, carriers were required to provide "Safe Driver" credits if the teenager participated in specific state-approved modules. Parents who navigated these programs successfully in 2019 often had to act as their own advocates, ensuring that the insurance company correctly applied all eligible credits, such as the "multi-car" discount combined with the "good student" discount.
Common Mistakes and Troubleshooting
Navigating these programs was often fraught with administrative errors. Parents frequently encountered issues that resulted in unnecessarily high premiums.
- The "Student Away" Oversight: If a teenager moved to a college more than 100 miles away without a car, they could often be listed as an "Away at School" driver. Failure to update this status in 2019 meant the parent continued to pay the "local driver" premium rate for a child who was rarely behind the wheel.
- Age-Out Delays: Many parents forgot to remove the teenage driver from the "teenager" classification once they reached the age of 21 or 25. While insurance premiums decrease as a driver gains more years of experience, the transition from a "teenager" to a "young adult" often required a specific request to the insurance agent to recalculate the policy risk.
- Missing Proof of Education: Carriers are not always proactive in requesting updated report cards. If a parent failed to submit proof of a 3.0 GPA annually, the "Good Student" discount would often drop off automatically.
Professional Advice and Financial Considerations
When managing auto insurance for a household with multiple drivers, the financial burden is significant. Financial advisors often suggest that parents view these insurance costs as a fixed educational expense rather than a variable luxury.
If you are currently managing a policy that originated under older guidelines, verify with your agent that you are not on a "legacy" plan that lacks the benefits of newer, more efficient telematics programs. In many cases, transitioning to a modern usage-based model allows for lower premiums if the teenage driver demonstrates responsible habits. However, always request a "premium impact analysis" before switching, as some programs penalize "hard braking" more severely than they reward safe speed, which could inadvertently raise costs for an inexperienced driver.
Frequently Asked Questions (FAQ)
1. Does my teen still qualify for 2019-era good student discounts? Most current insurance policies still offer Good Student Discounts, but they are not tied to 2019 contracts. You must provide current academic verification, usually every six months or at policy renewal, to maintain the discount.
2. Is it cheaper to put a teen on my policy or get them their own? Generally, it is significantly cheaper to include a teenager on a parent’s policy. Insurers offer multi-driver and multi-car discounts that are lost if a teenager holds an independent policy. Furthermore, teenagers lack the credit history and insurance history to qualify for competitive independent rates.
3. Are the 2019 telematics devices still valid? Most legacy telematics devices from 2019 have been decommissioned. Modern carriers favor smartphone-based apps or updated OBD-II sensors that communicate via 5G networks. Contact your provider to upgrade your hardware.
4. Can I exclude my teen from my policy to save money? Yes, most states allow for a "named driver exclusion." However, this means the teenager is strictly forbidden from driving the insured vehicles. If they drive the car and are involved in an accident, the insurance company will likely deny coverage, leaving the parent liable for all damages.
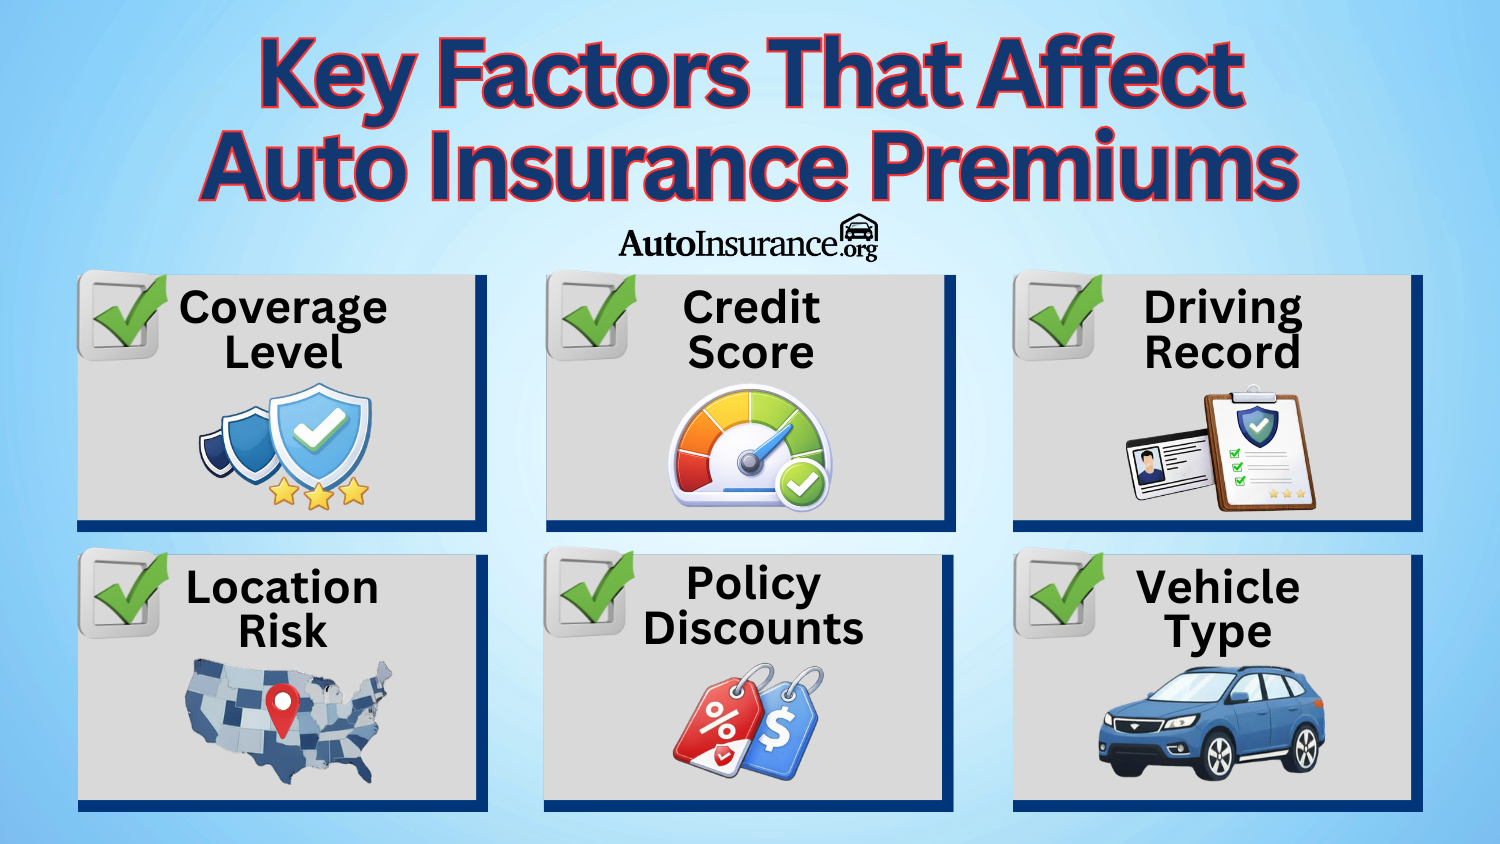
5. How do I verify my teen's driving risk score? You can request a summary of your policy’s risk factors from your insurance agent. While they may not provide a specific "score," they can explain which factors—such as age, vehicle type, and location—are driving your current premium.
Next Steps for Policy Management
To ensure you are not overpaying on your current auto insurance, perform an annual audit of your policy. Confirm that the vehicle assigned to your teenage driver is the safest and least expensive to repair, as this significantly influences the premium. Ensure that all academic and defensive driving course completions are documented and filed with your agent. Finally, if your teenager has reached the age of 21, request a manual review of their driver classification to ensure your premium reflects their increased experience.