Bundling home and auto insurance in Arvada, Colorado, combines both policies under a single insurer, generating multi-policy discounts typically ranging from 10% to 25%. In Arvada’s Front Range climate—where severe hail, high winds, and wildfire risks drive up individual policy rates—bundling helps maximize savings while streamlining claim management and policy administration.
Why Bundling Home and Auto Insurance Matters in Arvada
Arvada sits directly along Colorado's Front Range, an area globally recognized for volatile weather patterns. Homeowners and vehicle owners in Jefferson and Adams counties face significant exposure to extreme hailstorms, high-velocity Chinook winds coming off the Rocky Mountains, heavy winter snowfall, and localized wildfire hazards in western neighborhoods near Leyden and Ralston Valley. Because these regional risks increase underwriting loss ratios across both property and casualty lines, property and auto premiums in Colorado are among the higher averages nationwide.
Combining property and automobile protection into a multi-policy bundle is one of the most effective strategies to control insurance expenditures without sacrificing coverage depth. Insurance carriers incentivize multi-policy account management because client retention rates are higher for bundled accounts. For policyholders, this translates to substantial premium reductions on both the homeowners dwelling policy and the personal auto policy.
Beyond direct financial savings, operating under a single insurance carrier simplifies policy management. Dealing with one billing schedule, a single customer portal, and a unified claims administration process reduces friction when catastrophic weather events inflict simultaneous damage to a residence and vehicles parked on the property.
How Multi-Policy Bundling Works and Premium Savings
A multi-policy bundle operates by applying a percentage-based discount across each individual line of coverage. When you purchase both your homeowners insurance (HO-3 or HO-5 policy) and your personal auto policy through the same company, the carrier applies a multi-policy credit to both premiums.
- SINGLE INSURANCE CARRIER
- Homeowners Coverage
- Dwelling & Other Structures
- Personal Property & Liability
- Auto Coverage
- Comprehensive
- Collision & Liability
- Multi-Policy Discount (10% to 25%)
- Single Deductible Provision (Select)
- Streamlined Billing & Claims Portal
- Homeowners Coverage
The Financial Impact of the Multi-Policy Discount
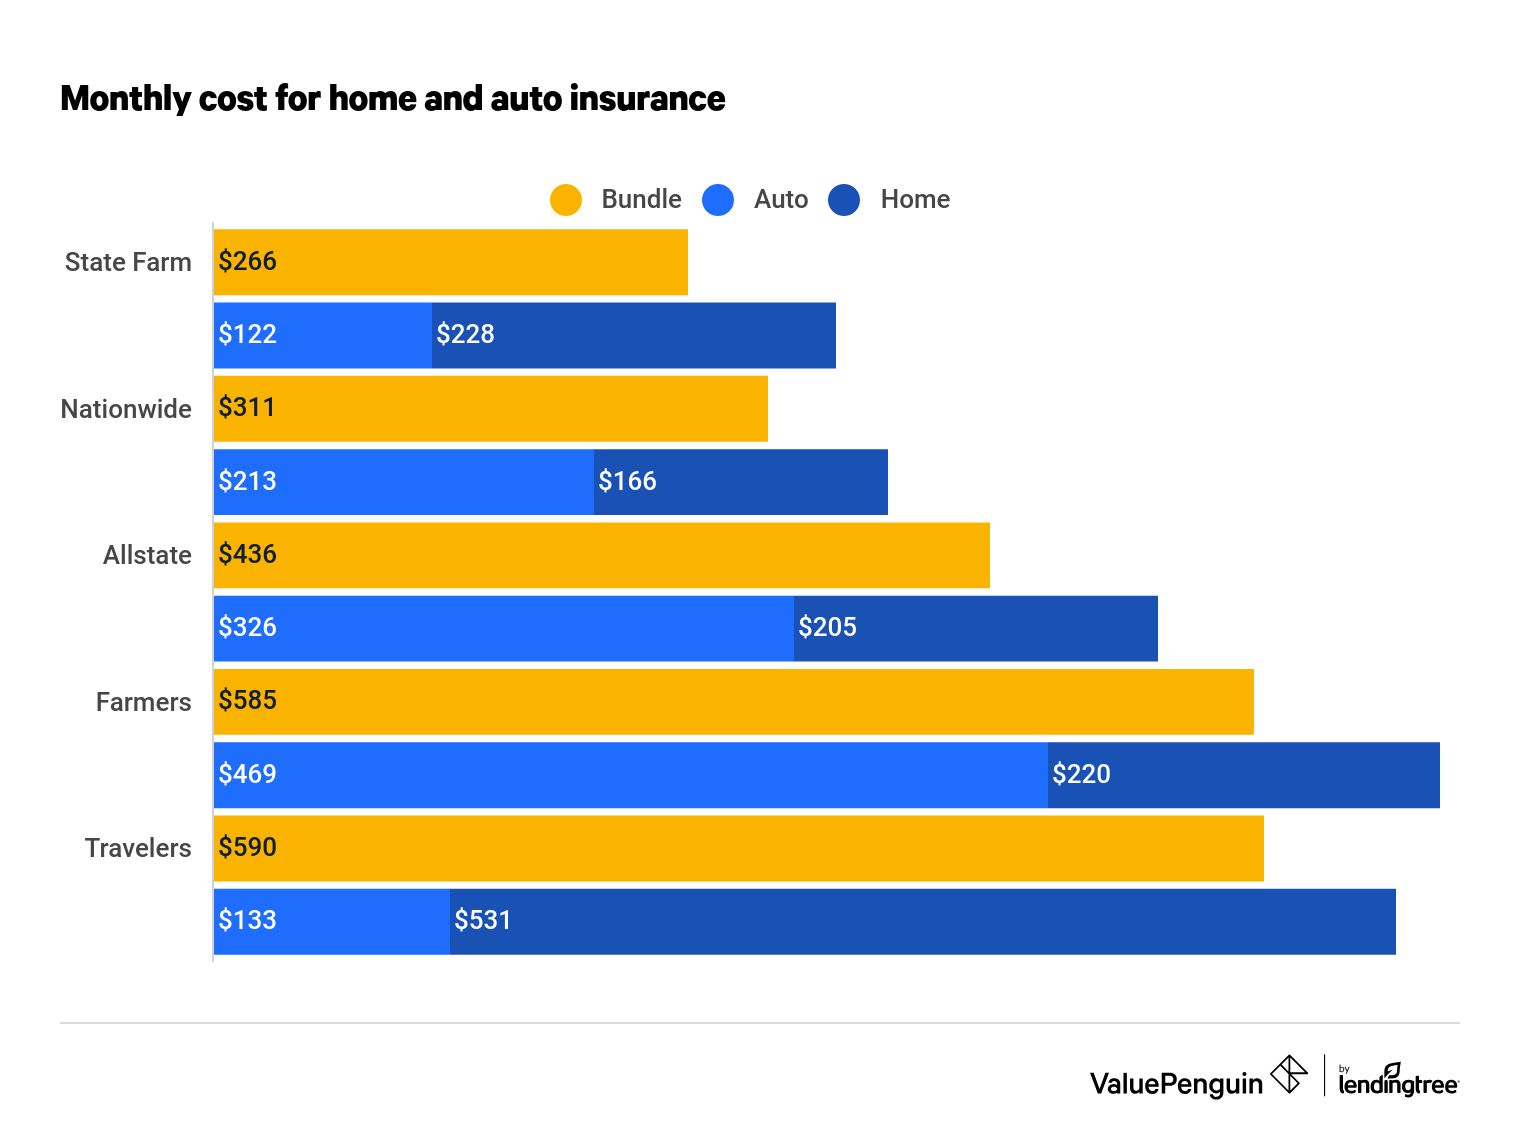
Discount structures vary depending on the insurance company, but typical reductions range from 10% to 25% on combined annual costs.
- Homeowners Discount: Carriers frequently reduce the base dwelling premium by 15% to 20%.
- Auto Discount: Multi-car and multi-policy discounts on auto coverage generally lower liability, comprehensive, and collision premiums by 10% to 15%.
When aggregated over an annual term, a household paying $2,400 per year for home coverage and $2,000 per year for auto coverage could see savings between $440 and $1,100 annually, depending on the carrier's specific rating algorithms and discount structures.
Single Loss Deductible Benefits
A critical feature offered by select bundled insurance providers in Arvada is the single-deductible endorsement for concurrent losses. Front Range hail storms frequently damage the roof, siding, and windows of a home while simultaneously denting vehicles parked in the driveway.
Under separate insurance carriers, you would be forced to pay two independent deductibles: a personal auto comprehensive deductible and a property wind/hail deductible. Under a carrier that offers a single loss deductible feature, if a single severe weather event damages both your home and auto, the insurer applies only the higher of the two deductibles or waives one deductible entirely.
Navigating Arvada's Specific Coverage Requirements
Securing a bundled policy requires evaluating coverage limits to ensure neither policy leaves major vulnerability gaps. Arvada's geographic position introduces specific liabilities that require targeted policy endorsements.
Homeowners Insurance Considerations
- Roof Loss Settlement Terms: Due to frequent severe hail along the Front Range, many carriers in Colorado have shifted from Replacement Cost Value (RCV) to Actual Cash Value (ACV) for roofs over a certain age (often 10 to 15 years old). When selecting a bundle, ensure your home policy retains RCV for wind and hail damage where possible, or evaluate roof endorsement options carefully.
- Wind and Hail Deductibles: Most insurers in Jefferson County mandate a separate deductible for wind and hail damage, typically set as a percentage of the total dwelling coverage (e.g., 1%, 2%, or 5% of Coverage A) rather than a flat dollar amount ($1,000 or $2,500). If your home has a $500,000 dwelling limit, a 2% wind/hail deductible requires a $10,000 out-of-pocket expense before insurance payments begin.
- Wildfire Risk and Defensible Space: Homes in western Arvada approaching the foothills must account for wildfire exposure. Insurers may require proof of defensible space—clearing brush, trimming trees, and managing flammable debris within 30 to 100 feet of the structure—as a prerequisite for issuing a bundled policy.
- Water Backup and Sump Pump Failure: Rapid snowmelt in spring combined with heavy rain can overwhelm municipal sewer lines or residential sump pumps. Standard home policies exclude water backup; an endorsement must be added to ensure coverage.
Auto Insurance Considerations
- Comprehensive Coverage for Hail: Comprehensive coverage pays for vehicle repair when non-collision events damage your vehicle. In Arvada, comprehensive coverage is essential due to high hail frequency. Ensure your auto policy comprehensive deductible is manageable ($250 to $500) so hail repair or glass replacement does not present a financial hardship.
- Liability Limits vs. Colorado Minimums: Colorado state law requires minimum liability limits of 25/50/25 ($25,000 bodily injury per person, $50,000 bodily injury per accident, and $25,000 property damage). However, given modern vehicle prices and high medical costs, local drivers should consider minimum liability coverage of 100/300/100 or higher to shield personal assets from lawsuit exposure.
- Uninsured/Underinsured Motorist (UM/UIM): A notable percentage of motorists operate vehicles without adequate insurance. UM/UIM coverage protects you and your passengers if you are struck by an uninsured or underinsured driver. This coverage is crucial across the Denver metropolitan area.
Comparing Home and Auto Bundle Elements in Arvada
To make an informed decision when evaluating carrier quotes, compare key coverage components, typical deductible structures, and local environmental protections.
| Policy Component | Basic/Unbundled Baseline | Comprehensive Arvada Bundle | Arvada Risk Factor Addressed |
|---|---|---|---|
| Home Dwelling Coverage | Estimated Replacement Cost | Extended Replacement Cost (125%-150%) | Rapid regional construction labor and material inflation |
| Roof Claim Settlement | Actual Cash Value (ACV) after 10 years | Replacement Cost Value (RCV) | High hail frequency requiring frequent full roof replacements |
| Wind/Hail Deductible | 2% to 5% Percentage Deductible | Flat $2,500 or 1% Split Deductible | Major out-of-pocket cost control following Front Range storms |
| Auto Liability Limits | CO Minimum (25/50/25) | Recommended (100/300/100 or 250/500/100) | Higher asset protection against costly multi-vehicle crashes |
| Auto Comprehensive | Optional / High Deductible ($1,000) | Standard / Low Deductible ($250-$500) | Frequent hail dent repair and windshield replacement |
| Combined Event Deductible | Two separate deductibles paid | Single loss deductible endorsement | Hail or wind storm damaging home and auto simultaneously |
| Wildfire Protection | Basic policy (subject to strict underwriting) | Policy with wildfire mitigation credit | Proximity to Front Range urban-wildland interface |
Step-by-Step Process to Secure a Home and Auto Bundle
Transitioning to a bundled policy or shopping for a new home and auto bundle requires a methodical approach to verify that you are gaining true financial savings without compromising essential protections.
- Step 1: Audit Existing Policies
- Check current coverage limits & deductibles
- Note roof age and auto VINs
- Identify renewal dates to avoid cancellation fees
- Step 2: Establish Arvada-Specific Coverage Baselines
- Require Replacement Cost Value (RCV) for roof
- Set comprehensive auto deductible at $250–$500
- Select liability limits matching total asset exposure
- Step 3: Collect & Compare Itemized Carrier Quotes
- Ensure quotes reflect identical limits
- Confirm multi-policy discount percentages
- Check for single-deductible endorsements
- Step 4: Conduct Property Safety Inspections
- Perform wildfire defensible space mitigation
- Document roof updates, hail impact ratings, or security upgrades
- Step 5: Execute Policy Switch & Synchronize Dates
- Bind new bundle policies
- Notify mortgage escrow account manager (if applicable)
- Cancel prior insurance policies with written confirmation
Step 1: Audit Current Policies and Declarations Pages
Gather your existing home and auto declarations pages. Document current coverage limits, deductibles, endorsements, and total annual premiums. Check your current roof age, heating system details, and vehicle identification numbers (VINs). Note your expiration dates so you can coordinate the changeover without experiencing a coverage gap.
Step 2: Establish Baseline Coverage Requirements
Define your coverage requirements before soliciting carrier quotes. Ensure your dwelling baseline reflects true regional rebuilding costs per square foot in Jefferson County. Mandate minimum auto liability limits of at least $100,000/$300,000/$100,000 and select low comprehensive deductibles for auto hail protection.
Step 3: Request Detailed, Itemized Carrier Quotes
Contact independent insurance brokers or captive insurance agents serving the Arvada market. Request bundled quotes that match your established baseline. Review the quotes to confirm that the advertised discount is applied to both lines, rather than a steep discount on auto paired with an inflated home baseline.
Step 4: Verify Local Risk Rules and Deductible Details
Examine the fine print regarding roof deductibles and loss settlement terms. Ask specifically:
- Is the wind/hail deductible a flat dollar amount or a percentage of Coverage A?
- Is roof coverage settled at Replacement Cost Value (RCV) or Actual Cash Value (ACV)?
- Does the policy include a single deductible waiver for joint hail or storm claims?
Step 5: Finalize Binding and Escrow Coordination
Once you select a carrier, set effective dates that align with your prior policy expirations. If your homeowners premium is paid through a mortgage escrow account, forward the new carrier's binder and invoice to your lender immediately to prevent double-billing or escrow shortfalls. Formally cancel your prior insurance policies in writing after confirming your new bundled policy is fully bound.
Common Pitfalls When Bundling Policies in Arvada
While bundling insurance offers advantages, making choices based solely on price can result in unexpected expenses when filing a claim.
Focus on Low Upfront Premiums Over High Deductibles
Carriers may lower a bundled policy quote by raising the property wind and hail deductible to 2% or 5% or setting auto collision and comprehensive deductibles at $1,500 or $2,000. While this reduces the monthly premium, a severe hail storm could leave you responsible for thousands of dollars in out-of-pocket costs before coverage responds.
Overlooking Roof Age and ACV Depreciation Endorsements
In response to high hail claim volume, insurance companies operating in Colorado often place strict restrictions on older roofs. If an insurer forces your roof onto an Actual Cash Value (ACV) schedule as a condition of issuing the bundle, the policy will deduct depreciation from your claim payment. Replacing a hail-damaged roof under an ACV provision can cost you thousands of dollars out of pocket compared to a standard Replacement Cost Value (RCV) policy.
Failing to Adjust Rebuilding Limits for Local Construction Costs
Front Range supply chain conditions and construction labor demands can cause local rebuilding costs to increase faster than national averages. A basic dwelling coverage limit based on standard national estimates may leave a home underinsured. Verify that your bundled policy includes extended replacement cost coverage (providing an additional 10% to 50% buffer above Coverage A limits) to account for demand surges following localized natural disasters.
Assuming a Bundle is Always the Cheapest Option
Although multi-policy bundling provides discounts in most cases, it is not universally the cheapest option for every homeowner or driver. For example, if a household has drivers with multiple moving violations or DUI history, specialized auto insurers may offer significantly lower auto rates than a traditional home-and-auto carrier. In such cases, purchasing separate policies from different carriers (monoline policies) may yield lower total costs than maintaining a bundle with a standard insurance provider.
Frequently Asked Questions
How much can I save on average by bundling home and auto insurance in Arvada?
Most policyholders in Arvada save between 10% and 25% on combined premium costs when bundling home and auto insurance. Total dollar savings depend on vehicle types, household driving records, total dwelling coverage limits, and carrier discount structures.
Does a bundled policy cover hail damage to both my home roof and my vehicle under one claim?
Coverage for both property structures and motor vehicles is evaluated under their respective policy sections (Homeowners Dwelling/Roof under Coverage A, and Auto damage under Auto Comprehensive). However, if both suffer damage in the same severe weather event, select bundled insurers allow you to file the claims simultaneously and pay only a single primary deductible rather than paying separate deductibles for both policies.
What auto liability limits are recommended for Arvada drivers beyond Colorado minimums?
While Colorado law permits minimum limits of 25/50/25, these figures are often insufficient to cover severe multi-vehicle accidents or extensive medical care. Industry experts recommend minimum auto liability limits of $100,000 per person, $300,000 per accident for bodily injury, and $100,000 for property damage (100/300/100), paired with equal limits of Uninsured/Underinsured Motorist coverage.
How does the age of my roof affect my ability to bundle insurance in Jefferson County?
Insurance companies carefully evaluate roof age and condition in Arvada due to frequent Front Range hail activity. Roofs older than 10 to 15 years may require an exterior inspection prior to policy approval. Depending on condition, the carrier may restrict coverage to Actual Cash Value (ACV) or require a higher wind/hail percentage deductible. In some instances, replacing an older roof is necessary to qualify for top-tier bundled rates with full Replacement Cost Value (RCV) protection.
Can I bundle policies if I live in a wildfire hazard zone in western Arvada?
Yes, but underwriting requirements are more stringent in high-risk areas such as western Arvada, Leyden, and the foothills. Insurance companies may require an inspection to verify defensible space mitigation around the home, including clearing dry vegetation, storing firewood away from the main structure, and removing tree branches overhanging the roof, before issuing a bundled policy.
Next Steps for Arvada Homeowners and Drivers
To optimize your insurance coverage and secure maximum multi-policy discounts, take direct action to review your personal asset exposure:
- Review Declarations Pages: Check your current home policy's wind/hail deductible, roof settlement terms (RCV vs. ACV), and auto comprehensive deductible.
- Conduct Property Inspections: Address overhanging tree branches, repair aging roof sections, and create defensible space to position your home for tier-one underwriting rates.
- Obtain Comparable Quotes: Contact a licensed local insurance agent or independent broker to gather bundled policy comparisons that match identical liability limits and include single-deductible options.
- Coordinate Policy Transitions: Ensure continuous, gap-free coverage by matching your new policy effective date with your previous policy cancellation date, and notify your mortgage lender to update escrow disbursement instructions.