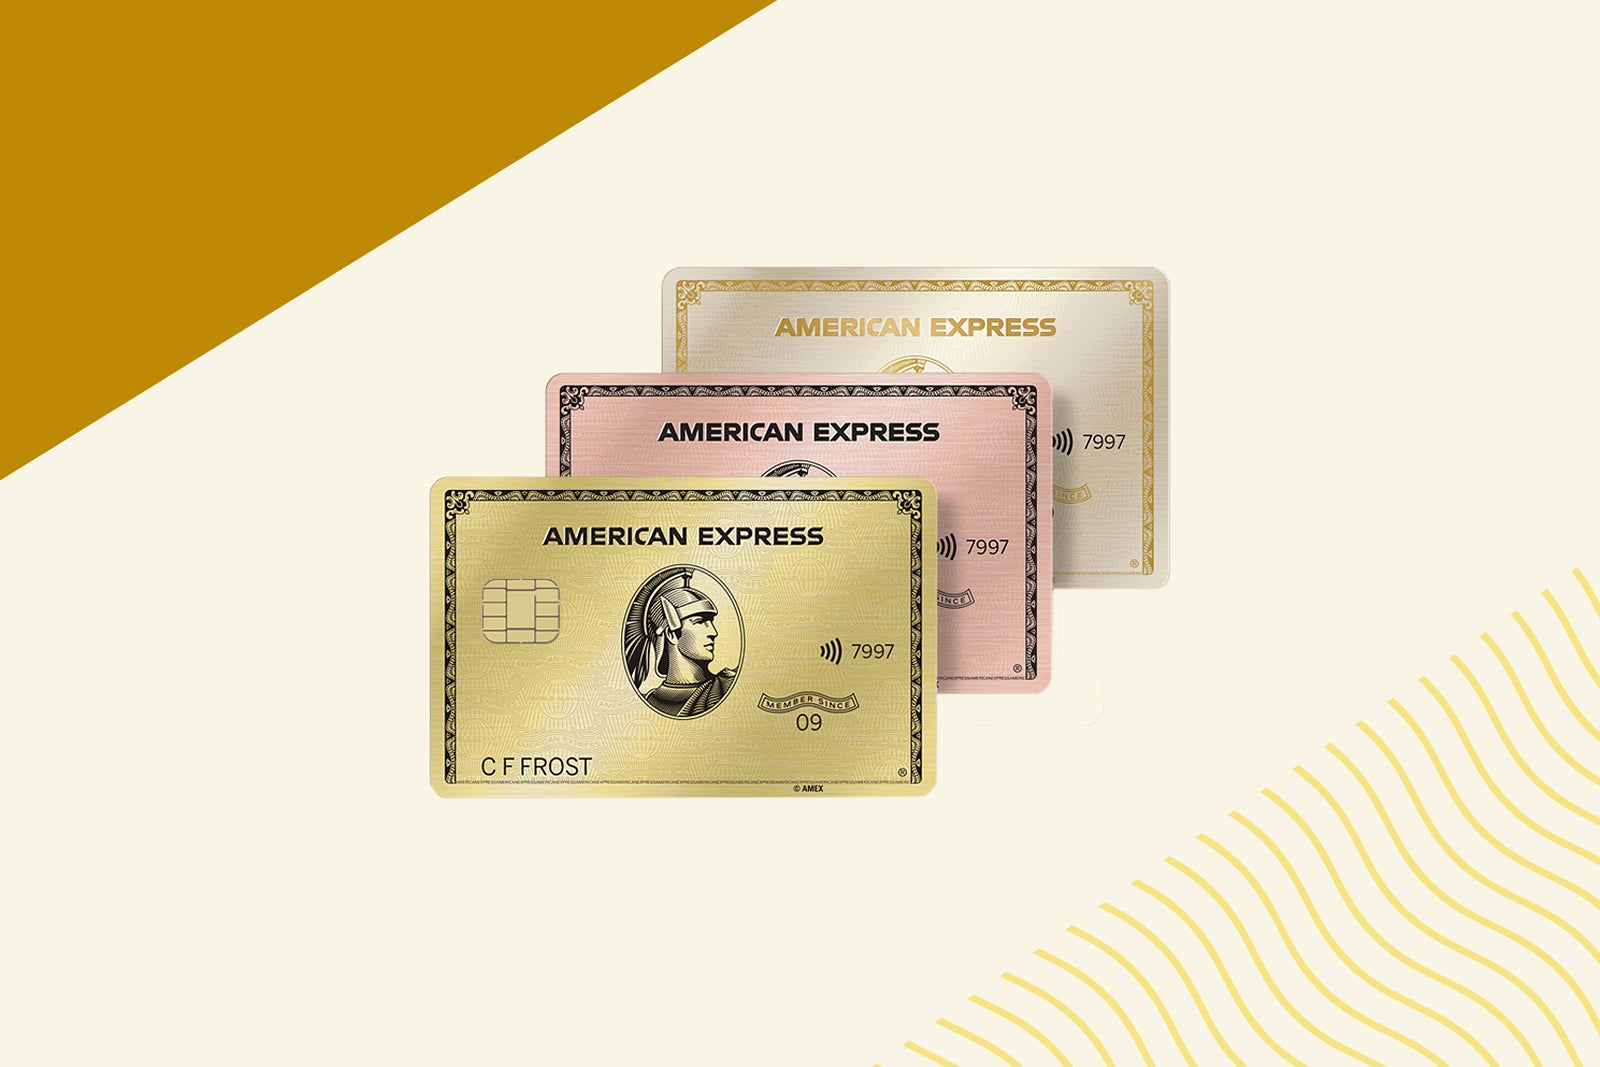
The American Express Business Gold card delivers targeted rewards for small- and medium-sized businesses by automatically shifting 4x points to the top two spending categories each billing cycle, alongside welcome bonus opportunities and robust business expense tracking features.
Choosing the right corporate or small-business credit card requires balancing annual fees against rewards structures, cash flow flexibility, and supplementary tools. For businesses with heavy spending in traditional operational areas—such as advertising, shipping, transit, and computing technology—the American Express Business Gold Card occupies a unique space in the financial ecosystem. Understanding the mechanics of the current welcome offer, the unique 4x rewards accrual system, the associated fees, and the broader ecosystem of Membership Rewards can help business owners determine whether this card aligns with their operational expenditure profile.
Core Structure and Target Audience of the Amex Business Gold
The American Express Business Gold Card is engineered specifically for sole proprietors, partnerships, and registered corporations with consistent, concentrated spending in select business categories. Unlike personal travel cards that prioritize dining and supermarkets, business cards must align with commercial overhead.
The primary target audience consists of growing businesses that spend heavily on digital marketing campaigns, shipping logistics, electronic equipment, and software services. These businesses often require flexible purchasing power without a traditional revolving credit limit, as well as employee cards that can accumulate rewards toward a centralized corporate account.
Understanding Membership Rewards Economics
To extract maximum value from any American Express Business Gold offer, applicants must understand how Membership Rewards points operate. Amex points can be redeemed for statement credits, gift cards, or travel through the Amex Travel portal, but their highest potential value typically lies in transferring them to airline and hotel loyalty program partners.
- Transfer Partners: Amex partners with dozens of airline and hotel programs, allowing cardholders to transfer points at a standard 1:1 ratio in most cases.
- Flexibility: Points do not expire as long as the account remains open and in good standing.
- Pooling: Points earned across multiple eligible American Express business and personal cards can be combined into a single master account, streamlining redemption strategies.
Evaluating the Welcome Offer and Application Prerequisites
Welcome offers for the American Express Business Gold card typically consist of a specified number of Membership Rewards points awarded after meeting a designated minimum spending threshold within a set timeframe following account opening. These bonuses represent the most immediate return on investment for new cardholders, often outweighing the card's annual fee during the first year.
However, securing the offer requires meeting specific eligibility criteria and navigating issuer-specific rules.
Eligibility Criteria and Issuer Rules
American Express maintains strict guidelines regarding who can qualify for a welcome bonus on business card products:
- Once-in-a-Lifetime Rule: Generally, applicants who currently hold or have previously held the American Express Business Gold Card are not eligible to receive a welcome offer for that same product. Amex evaluates eligibility based on internal history, and a pop-up window will typically notify applicants during the online application process if they do not qualify for the bonus before the final credit check is performed.
- Creditworthiness: Approval depends heavily on the applicant’s personal credit score and history, even though the card is issued for business purposes. Personal guarantees are standard for small business credit products.
- Business Verification: Applicants must provide accurate business details, including a legal business name, structure, address, and an Employer Identification Number (EIN) or Social Security Number (SSN) for sole proprietors.
| Card Feature | Specification / Detail |
|---|---|
| Primary Reward Rate | 4x points on the top two eligible categories each billing cycle |
| Reward Cap | 4x applies to the first $150,000 in combined purchases per calendar year |
| Base Reward Rate | 1x points on all other eligible business purchases |
| Annual Fee | Structured according to current Amex fee schedules |
| Foreign Transaction Fees | None |
| Credit Limit Type | Expanded buying power (not a traditional fixed revolving limit) |
The 4x Points Mechanics: How the Spending Categories Work
The defining feature of the American Express Business Gold card is its dynamic 4x points multiplier. Rather than forcing cardholders to choose a static bonus category, the card automatically adapts to spending patterns from month to month.
Eligible 4x Categories
Each billing cycle, the card identifies the top two categories where the business spent the most money and awards 4x points on those purchases. The available categories typically include:
- Online, TV, and Radio Advertising: Purchases for digital marketing, social media ads, and broadcast media placed with media providers in the U.S.
- Computer Hardware, Software, and Cloud Solutions: Purchases made directly from select technology providers for hardware, software, and cloud computing subscriptions.
- Shipping Services: Purchases for courier, freight, and postal services originating in the U.S.
- Transit: Purchases including trains, taxicabs, rideshare services, ferries, tolls, parking, buses, and subways.
- Gas Stations: Purchases at standalone U.S. gas stations.
- Restaurants: Purchases at restaurants located in the U.S., including takeout and delivery.
The Annual Spending Cap
The 4x rewards rate applies to the first $150,000 in combined eligible purchases each calendar year. Once this threshold is reached, all spending in those categories reverts to the base rate of 1x points for the remainder of the calendar year. This cap resets on January 1st of each subsequent year. For businesses with expenditures exceeding this cap, careful tracking is necessary to optimize reward accumulation across multiple accounts or alternative financial products.
Comparing Amex Business Gold vs. Alternative Business Cards
Selecting the right card involves weighing the Business Gold against competing products in the small business market, such as the Chase Ink Business Preferred or the American Express Platinum Business Card.
American Express Business Gold vs. Chase Ink Business Preferred
- Reward Structure: The Business Gold offers a dynamic 4x structure on top spending categories up to $150,000 annually. The Ink Business Preferred offers a static 3x multiplier on the first $150,000 spent combined in broad categories like shipping, advertising, internet/cable/phone services, and travel.
- Annual Fee: The Business Gold carries a higher annual fee than the Ink Business Preferred, reflecting its higher earning potential in specialized categories and additional merchant-focused credits.
- Redemption Ecosystem: Amex focuses on Membership Rewards transfer partners, whereas Chase utilizes Ultimate Rewards points, which feature distinct airline and hotel partners (such as United Airlines and Hyatt).
American Express Business Gold vs. Amex Business Platinum
- Focus: The Business Gold is strictly optimized for earning points on day-to-day operational spending. The Business Platinum is a premium travel card that offers airport lounge access, status, and large purchase multipliers (such as 1.5x on eligible purchases of $5,000 or more), but features a significantly higher annual fee.
- Credits: The Business Platinum includes extensive statement credits for software, wireless services, and travel, whereas the Business Gold is tailored specifically to advertising, dining, and operational expenses.
Cost Considerations and Ongoing Account Management
Owning a business credit card entails more than just earning rewards; it requires careful management of fees, cash flow, and accounting integration.
Annual Fees and Value Realization
The annual fee represents a fixed overhead cost. To determine net value, business owners must calculate whether the points earned via the 4x categories and any included statement credits exceed the cost of the fee. For instance, a business spending $3,000 a month consistently in advertising and shipping will accumulate 144,000 points annually from those categories alone (at 4x), easily surpassing the baseline cost of ownership when transferred to high-value travel partners.
Cash Flow and Flexible Purchasing Power
The American Express Business Gold card is designed with "Expanded Buying Power," meaning the credit limit is dynamic and adjusts based on factors such as payment history, credit record, and financial resources. While this allows businesses to handle large, unexpected inventory or advertising outlays, it is critical to note that the card functions as a charge card or a Pay Over Time product. Carrying a balance incurs interest charges, which can quickly erode the value of accumulated rewards if balances are not managed prudently.
Expense Management Tools
To simplify bookkeeping, the card integrates with various financial software platforms like QuickBooks. Cardholders can also issue employee cards, set individual spending limits, and track employee expenditures in real-time through the American Express online dashboard, reducing the administrative burden of manual expense reporting.
Common Pitfalls and Troubleshooting
Navigating business credit card rewards requires attention to detail to avoid missed bonuses or forfeited points.
- Missing the Welcome Offer Deadline: The timeframe to meet the minimum spending requirement begins the day the account is approved, not when the physical card arrives. Delays in activation can shorten the operational window for hitting spending thresholds.
- Misunderstanding Category Inclusions: Not all purchases coded under a broad industry term qualify for 4x points. For example, software purchased through a third-party reseller rather than directly from the developer may code as general business supplies (1x) rather than software solutions (4x). Reviewing merchant category codes (MCC) is essential for high-volume spenders.
- Forfeiting Points: If an account is closed due to delinquency, accumulated Membership Rewards points can be permanently lost. Points should be transferred to partner programs or redeemed before initiating voluntary account closures.
Strategic Next Actions for Interested Business Owners
For business owners considering an application for the American Express Business Gold card, a structured approach yields the best results:
- Audit Past Expenses: Review the previous 12 months of company ledger entries to determine if spending aligns with the 4x categories (advertising, shipping, technology, transit).
- Verify Welcome Offer Terms: Check current public or targeted offers to ensure the minimum spending requirement aligns with upcoming operational outlays (such as a planned inventory purchase or marketing push).
- Check Eligibility: Utilize the online pre-qualification tools on the American Express website to check for potential welcome bonus eligibility before submitting a formal application that triggers a hard credit inquiry.