Securing comprehensive insurance coverage in Georgia involves navigating state-specific regulations and Allstate’s unique product offerings. Whether you are insuring a vehicle or protecting a home, understanding coverage requirements, potential discounts, and the claims process is essential for making informed financial decisions in the current insurance market.
The Landscape of Insurance in Georgia
Georgia operates under a "tort" system for auto insurance, meaning the individual at fault for an accident is responsible for the damages. This legal framework necessitates that drivers carry specific minimum levels of liability coverage to remain compliant with the Georgia Department of Insurance. When choosing Allstate for auto and home insurance, policyholders are engaging with a national carrier that integrates local agency support with digital management tools.
Because insurance pricing and availability can shift based on geographic risk—such as the prevalence of severe weather in Northern Georgia or urban traffic density in the Atlanta metropolitan area—policyholders must verify their coverage against their specific residential and driving profiles.
Understanding Georgia Auto Insurance Requirements
In Georgia, the minimum mandatory auto insurance coverage is designed to provide financial protection for third parties involved in an accident caused by your vehicle. As of 2026, the state-mandated minimums are:
- Bodily Injury Liability: $25,000 per person and $50,000 per accident.
- Property Damage Liability: $25,000 per accident.
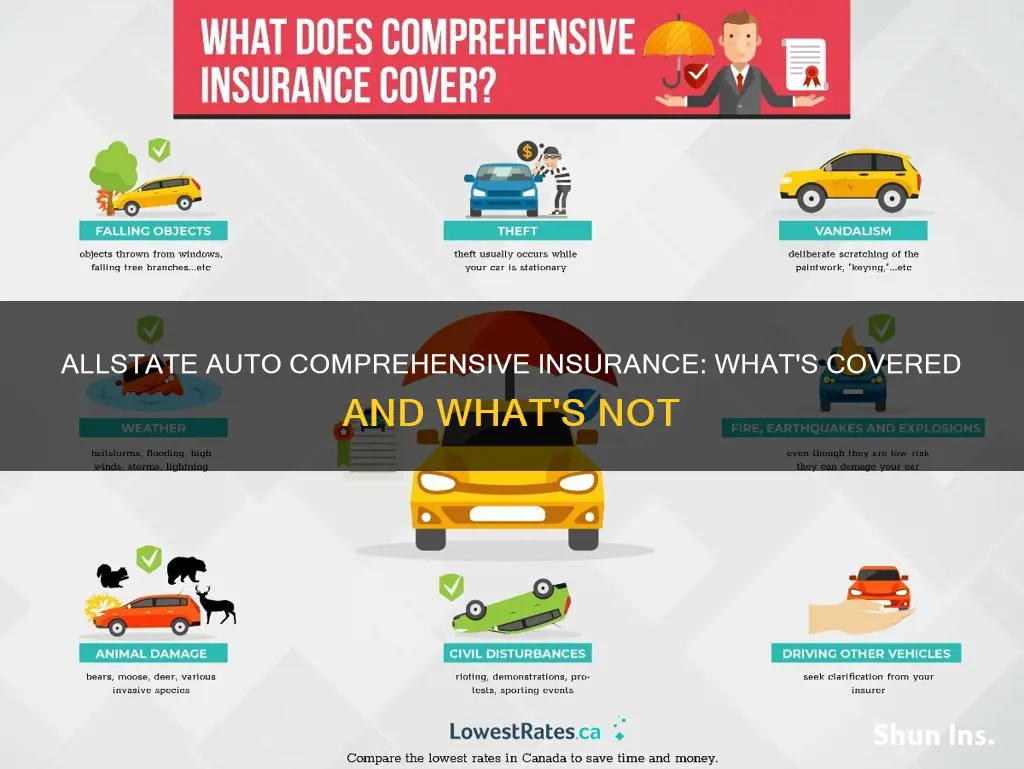
While these figures meet the legal threshold for operating a motor vehicle, they often fall short of the actual costs associated with modern vehicle repairs or medical expenses. Allstate’s auto insurance portfolio in Georgia allows for supplemental options such as collision coverage, comprehensive coverage, and uninsured/underinsured motorist protection. Selecting coverage levels higher than the state minimum is a common strategy to protect personal assets from litigation.
Homeowners Insurance Considerations in Georgia
Homeowners insurance is not legally mandated by the state of Georgia, but it is almost universally required by mortgage lenders. Allstate’s homeowners policies in the state generally cover the physical structure of the home, personal property, and liability protection.
Given Georgia's climate, which can include heavy seasonal thunderstorms, wind events, and rare but impactful winter storms, reviewing the "perils" covered by your policy is critical. Policyholders should pay close attention to:
- Replacement Cost Coverage: This provides the funds to rebuild your home to its pre-loss condition without a deduction for depreciation.
- Actual Cash Value: This accounts for the current market value of your property, which may be significantly lower than what is required to rebuild.
- Exclusions: It is important to note that standard homeowners insurance typically does not cover flood damage or earthquake damage. These usually require separate, standalone policies.
Comparing Coverage Options and Bundling
One of the primary benefits of utilizing a large provider like Allstate is the ability to "bundle" home and auto policies. Bundling often results in a multi-policy discount, which can reduce the annual premium for both lines of insurance.
| Feature | Auto Insurance | Homeowners Insurance |
|---|---|---|
| Primary Goal | Liability and asset protection | Property and liability protection |
| Mandatory Status | Required by law | Required by lenders |
| Key Factors | Driving record, vehicle type | Location, age of home, materials |
| Available Discounts | Safe driving, multi-car, bundling | Multi-policy, protective devices |
When evaluating these options, users should request a "Declarations Page" from their current provider to compare coverage limits side-by-side with an Allstate quote. This ensures an "apples-to-apples" comparison rather than merely comparing the final premium price, which can be misleading if coverage levels differ.
Factors Influencing Insurance Premiums in Georgia
Several variables determine the final cost of an insurance policy in Georgia. Allstate, like most carriers, utilizes actuarial data to assess risk.
- Geographic Risk: Premiums are often tiered based on the "rating territory." A home in a zip code with a higher history of claims or a vehicle parked in a high-theft urban area may command higher rates.
- Credit-Based Insurance Scores: Georgia law permits the use of credit information to calculate insurance premiums. Maintaining a positive credit history is one of the most effective ways to manage long-term insurance costs.
- Deductibles: Increasing your deductible—the amount you pay out-of-pocket before insurance kicks in—is a reliable method to lower your monthly premium. However, you must ensure you have the liquid savings to cover the higher deductible in the event of a claim.
- Claims History: Past claims indicate a higher statistical probability of future claims. A clean loss history is typically rewarded with lower rates.
The Allstate Digital Experience vs. Local Agents
Allstate maintains a hybrid model in Georgia. Customers can manage their policies through the Allstate mobile application or website, which allows for bill payments, document retrieval, and the initiation of claims. However, the company also relies heavily on local, independent-contractor agents.
For complex insurance needs, such as determining the correct amount of umbrella liability coverage or navigating the nuances of a historic home's insurance requirements, interacting with a local agent is often more effective than relying solely on automated systems. Agents can provide localized expertise regarding Georgia-specific risks and available state-level discounts that might not be highlighted in a generic online quote engine.
Initiating a Claim
In the event of an accident or property damage, the speed and accuracy of the claim process are paramount. For auto accidents, always prioritize safety and, if required by law, contact local law enforcement to obtain a police report. This report is vital for your claim.
For home insurance claims, the policyholder has a duty to mitigate further damage. This might include tarping a damaged roof or boarding up a broken window after a storm. Documenting the damage with photographs or video before any cleanup begins is essential for the adjustor’s report. Allstate allows for claims submission via their mobile app, where you can upload evidence and track the status of your claim in real-time.
Common Mistakes to Avoid
- Underinsuring the Home: Many homeowners make the mistake of insuring their home for its "market value" rather than its "rebuild value." If your home is worth $500,000 but would cost $650,000 to rebuild due to labor and material costs, you are underinsured.
- Failing to Disclose Renovations: If you have installed a new roof, upgraded electrical wiring, or added a security system, notify your agent. These improvements can often lower your homeowners insurance premiums.
- Neglecting Liability Limits: Minimum state liability limits rarely provide adequate protection if you are found liable for a serious injury. Many experts suggest carrying higher liability limits to safeguard your future earnings and assets.
- Ignoring Periodic Reviews: Insurance is not a "set it and forget it" product. Life changes—such as a new driver in the household, a home addition, or changes in credit score—should trigger a policy review at least annually.
Frequently Asked Questions
1. Does Allstate offer discounts for safe driving in Georgia? Yes, Allstate offers several programs, such as Drivewise, which monitors driving habits through a mobile app. Safe driving behaviors, such as avoiding sudden braking and limiting late-night driving, can lead to premium discounts upon renewal.
2. Can I get a discount for having a home security system? Yes, in Georgia, many homeowners qualify for discounts if they have monitored burglar or fire alarms installed. You will likely need to provide proof of the system's maintenance or a certificate from the monitoring company to your agent.
3. Is flood insurance included in an Allstate homeowners policy? No. Flood insurance is generally excluded from standard homeowners policies. In Georgia, residents in high-risk areas—and even moderate-risk areas—should consider a separate flood insurance policy, typically provided through the National Flood Insurance Program (NFIP) or private market equivalents.
4. How does the bundling discount work in Georgia? Bundling is the practice of holding both your auto and home insurance policies with the same provider. By doing so, Allstate typically applies a discount to both premiums. The percentage varies based on the specific policy details and location within Georgia.
5. How are insurance premiums determined in Georgia? Premiums are calculated based on risk assessment. Factors include your specific location, the age and condition of your home, your driving history, your credit-based insurance score, and the coverage limits and deductibles you select.
Recommended Next Actions
If you are currently evaluating your insurance coverage in Georgia, begin by collecting your current policy documents. Schedule a consultation with a local Allstate agent to conduct a "coverage gap analysis." Ask them specifically about the replacement cost of your home and whether your current liability limits are sufficient to protect your net worth. Review these documents annually, especially after any major life event or home improvement, to ensure your financial security remains intact.