For ultra-high-net-worth individuals (UHNWIs) seeking elite asset stewardship in 2026, UBS Global Wealth Management, J.P. Morgan Private Bank, and Goldman Sachs Private Wealth Management represent the gold standard. These institutions provide the global scale, institutional-grade investment access, and sophisticated estate planning required to manage capital exceeding $30 million.
Navigating the landscape of private banking at the ultra-high-net-worth (UHNW) level requires more than just a standard brokerage account. At this echelon, wealth management transforms into a comprehensive suite of services including tax optimization, philanthropic advisory, private equity access, and multi-generational succession planning. By 2026, the consolidation of the banking sector and the advancement of AI-driven portfolio construction have further distinguished the top-tier players from regional competitors.
Defining the UHNW Private Banking Landscape in 2026
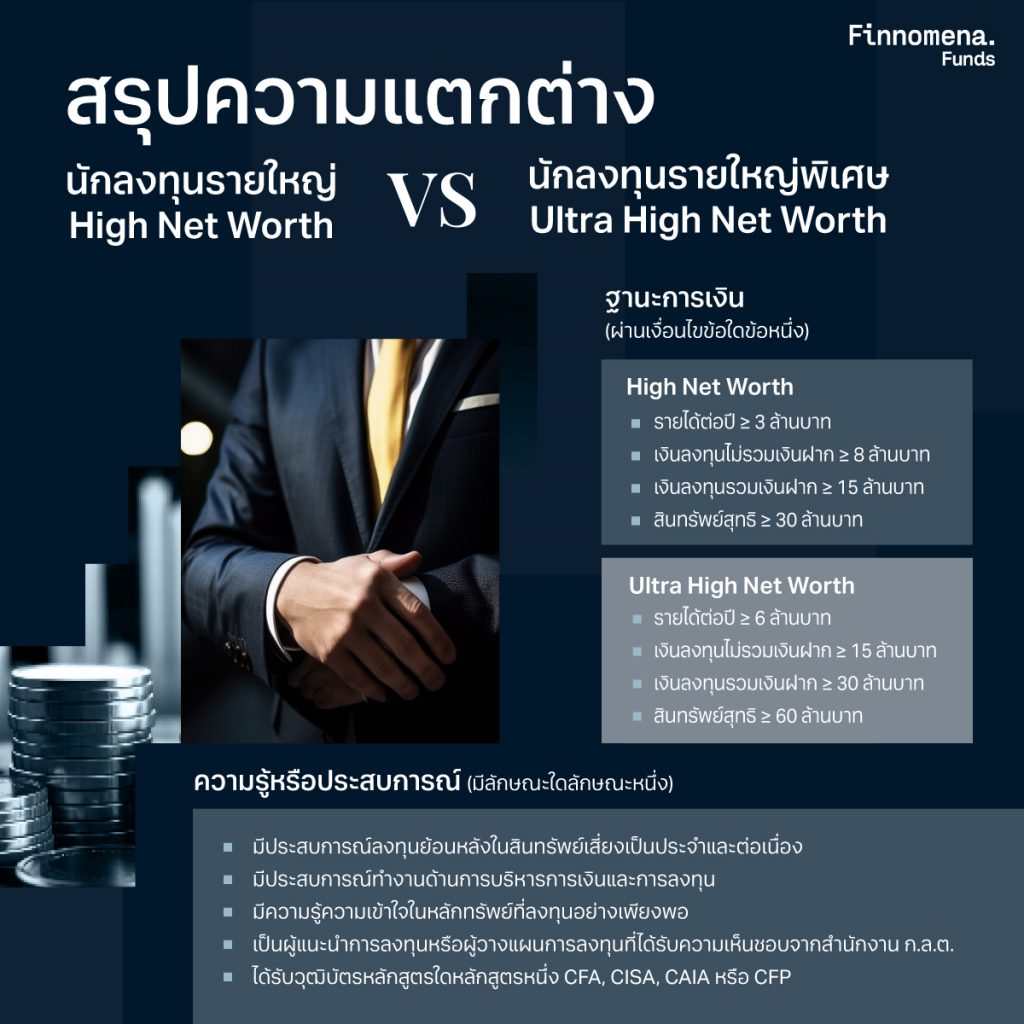
To understand why these three firms dominate, one must first define the parameters of ultra-high-net-worth wealth management. While "High Net Worth" (HNW) generally refers to individuals with $1 million to $5 million in liquid assets, the UHNW segment typically begins at $30 million in investable assets. However, for the premier "Private Office" tiers within these banks, the threshold often sits at $50 million to $100 million.
The primary problem these managers solve is the "complexity of scale." When a family’s net worth exceeds $100 million, their financial life resembles a mid-sized corporation more than a household. They require institutional-grade reporting, specialized lending (such as art or aircraft financing), and access to "club deals"—private investment opportunities not available to the public or even to smaller HNW clients.
In 2026, the regulatory environment is more stringent than ever, emphasizing transparency and the "fiduciary-first" model. The top wealth managers have adapted by integrating advanced risk-management tools that simulate geopolitical shocks and climate-related financial risks in real-time.
1. UBS Global Wealth Management: The World’s Largest Pure-Play Wealth Manager
As of 2026, UBS remains the undisputed leader in global wealth management. Following the successful integration of Credit Suisse—a process finalized years prior—UBS has solidified its position as the primary choice for international UHNWIs, particularly those with cross-border interests in Europe, Asia, and the Americas.
Global Reach and the "Chief Investment Office" (CIO)
The hallmark of UBS is its Chief Investment Office (CIO). This entity synthesizes global economic data to provide a unified "House View" that guides trillions of dollars in assets. For UHNW clients, this means their portfolios are not just managed by a single advisor but are backed by a global engine of over 900 analysts. In 2026, UBS has leveraged this scale to offer highly specialized "thematic" portfolios focusing on post-carbon energy transitions and longevity biotechnology.
The Global Family Office (GFO) Segment
For families with assets exceeding $250 million, UBS offers the Global Family Office unit. This is a joint venture between the Investment Bank and Wealth Management divisions. It provides UHNWIs with the same level of execution and liquidity that the bank offers to hedge funds and institutional pension schemes. This includes direct access to capital markets, bespoke derivatives for hedging concentrated stock positions, and prime brokerage services.
Minimums and Accessibility
While UBS Global Wealth Management technically accepts clients at lower HNW levels, the dedicated UHNW service tier typically requires a minimum of $50 million in assets held with the bank to access the full suite of specialized advisory and GFO services.
2. J.P. Morgan Private Bank: The Institutional Powerhouse
J.P. Morgan Private Bank is frequently cited as the top choice for UHNWIs who require the "Fortress Balance Sheet" and the raw power of a Tier-1 investment bank. J.P. Morgan’s value proposition in 2026 centers on its integrated approach, often referred to as the "One Bank" model.
Institutional Access for Individuals
The primary advantage of J.P. Morgan is that it treats its UHNW clients like institutional investors. A client with $100 million at J.P. Morgan can access the same private equity funds, venture capital rounds, and private credit opportunities as a billion-dollar endowment. Their 23 Wall team—a specialized unit named after the bank’s historic headquarters—specifically services the world’s 700 wealthiest families, providing them with bespoke deal flow that rarely reaches the broader market.
Technology and Unified Reporting
By 2026, J.P. Morgan has perfected its digital wealth platform, allowing UHNWIs to view their entire global footprint—including art collections, real estate, and private business interests—in a single, secure interface. This "total wealth" view is critical for the modern UHNW individual who may hold assets across dozens of jurisdictions and entities.
Prerequisites and Requirements
J.P. Morgan Private Bank generally requires a minimum of $10 million to $25 million in investable assets for its standard private banking services. However, to access the elite UHNW advisory teams and specialized alternative investment platforms, the functional requirement is often $50 million or higher.
3. Goldman Sachs Private Wealth Management: The Elite Specialist
If UBS is the global giant and J.P. Morgan is the institutional fortress, Goldman Sachs is the elite specialist. Goldman Sachs Private Wealth Management (PWM) is known for having one of the highest ratios of support staff to clients in the industry, ensuring an extremely high-touch experience.
Focus on Alternatives and Private Markets
Goldman Sachs has historically been defined by its prowess in investment banking. For a UHNW client in 2026, this translates into unparalleled access to Alternative Investments. Goldman’s PWM clients are often first in line for the firm’s proprietary private equity funds and co-investment opportunities alongside the bank’s own capital. This "alignment of interest" is a significant draw for entrepreneurs and C-suite executives.
The "Advisor-Led" Model
Unlike some competitors that have moved toward more automated or "platform-led" models, Goldman Sachs maintains a fiercely traditional, advisor-led approach. Each advisor works with a limited number of families, often spanning three or four generations. This allows for deep expertise in complex areas like the Qualified Small Business Stock (QSBS) rules or the structuring of Family Limited Partnerships (FLPs).
Minimums and Exclusivity
Goldman Sachs remains one of the most exclusive players in the market. While they have expanded their reach through various acquisitions in the past, their core Private Wealth Management business typically maintains a strict $10 million minimum, with the "Goldman UHNW" experience truly beginning at the $30 million to $50 million mark.
Comparison of Top UHNW Wealth Managers
The following table compares the core attributes of the three leaders as they stand in 2026.
| Feature | UBS Global Wealth Management | J.P. Morgan Private Bank | Goldman Sachs PWM |
|---|---|---|---|
| Primary Strength | Global reach & thematic research | Institutional integration & lending | Alternatives & high-touch advisory |
| Typical UHNW Entry | $50M+ (GFO Tier) | $25M - $50M | $10M - $30M |
| Global Presence | Strongest (Dominant in Europe/Asia) | High (Strongest in North America) | High (Selective Global Hubs) |
| Alternative Access | Extensive (External Manager focus) | Institutional (Internal & External) | Elite (Heavy focus on Proprietary deals) |
| Best For | International families with global assets | Clients needing complex lending/IB | Entrepreneurs seeking PE/VC access |
Understanding Fee Structures in UHNW Private Banking
Fee transparency has become a central theme in 2026. For UHNWIs, the cost of wealth management is rarely a single number. Instead, it is a combination of several layers that must be carefully audited.
- Advisory Fees (AUM-based): Most private banks charge a percentage of Assets Under Management (AUM). For UHNW accounts, this fee is highly negotiable. While a retail client might pay 1.00%, a client with $100 million may pay between 0.25% and 0.50% for the core advisory relationship.
- Platform and Custody Fees: This covers the administrative cost of holding assets, executing trades, and generating tax reports. In many 2026 fee models, these are bundled into the advisory fee.
- Product-Level Fees: These are the internal costs of the funds themselves. For UHNWIs heavily invested in private equity or hedge funds, "carried interest" (performance fees) and management fees (typically 1.5% to 2%) within those funds can be the largest expense.
- Specialized Service Fees: Banks may charge flat fees for specialized work such as complex estate planning, philanthropic foundation management, or "lifestyle" services (e.g., managing a private fleet).
It is a common mistake to focus only on the AUM fee. A sophisticated investor must look at the Total Expense Ratio (TER), which includes all the hidden layers mentioned above.
Critical Considerations for Selecting a Manager
Choosing among these three firms requires an alignment of the family's specific needs with the bank's core identity.
- Jurisdictional Complexity: If your wealth is spread across multiple countries with different tax treaties, UBS’s global footprint is often the most efficient. They are adept at handling the regulatory reporting requirements of diverse jurisdictions simultaneously.
- Liquidity Needs: If you are a founder whose wealth is tied up in a private company and you need significant liquidity for a new venture, J.P. Morgan’s lending desk is often the most aggressive and capable of structuring complex, asset-backed loans.
- Investment Philosophy: If your goal is to outperform the public markets through early-stage technology or private credit, the "deal-making" culture of Goldman Sachs provides a distinct advantage.
The Role of the Multi-Family Office (MFO) Alternative
While UBS, J.P. Morgan, and Goldman Sachs are the "Big Three" of private banking, many UHNWIs in 2026 also consider Multi-Family Offices (MFOs). Firms like Rockefeller Capital Management or Bessemer Trust offer a different model—often fee-only and independent of an investment bank.
The trade-off is one of scale versus objectivity. A private bank provides everything under one roof (the "supermarket" model), which is convenient and powerful. An MFO acts more like a "buyer" of services on behalf of the family, potentially offering more objective advice but lacking the direct, "first-call" access to IPOs and massive balance-sheet lending that a J.P. Morgan or Goldman Sachs provides.
Verification and Safety: The G-SIB Designation
When dealing with UHNW levels of capital, the safety of the institution is paramount. All three of these firms are classified as Global Systemically Important Banks (G-SIBs) by the Financial Stability Board. This designation means they are subject to higher capital buffer requirements and more rigorous stress testing than regional banks. For a UHNW client, this provides a layer of "too big to fail" security that is essential for long-term capital preservation.
Frequently Asked Questions
What is the difference between HNW and UHNW?
High Net Worth (HNW) generally refers to individuals with $1 million to $5 million in investable assets. Ultra-High Net Worth (UHNW) is defined by the industry as individuals with $30 million or more in liquid, investable assets. The service level changes significantly at the UHNW mark, moving from standardized investment products to bespoke, institutional-grade solutions.
Do I need a Private Bank if I already have a Family Office?
Many UHNW families use a "Hybrid Model." They have their own Single Family Office (SFO) to handle day-to-day administration, but they maintain accounts at one or two of the top private banks to access global custody, investment research, and capital markets execution that a private office cannot replicate internally.
How do I switch wealth managers at the UHNW level?
Switching is a complex process known as "onboarding and transition." It involves an In-Kind Transfer (ACATS) of public securities to avoid tax hits, but private equity interests and structured products may be more difficult to move. The new bank typically assigns a dedicated transition team to handle the legal and tax paperwork over a 3-to-6-month period.
Are fees negotiable at the $50 million level?
Yes, fees are highly negotiable. At $50 million and above, the "rack rate" or standard fee schedule rarely applies. Clients should ask for a "bundled" fee quote and a "break-out" of all underlying product costs to ensure they are receiving a competitive institutional rate.
Which bank is best for ESG and Impact Investing in 2026?
By 2026, UBS has the most integrated ESG (Environmental, Social, and Governance) framework, having made it their "preferred" investment style for all private clients. J.P. Morgan is a close second, particularly in the realm of large-scale "Green Infrastructure" and carbon-offset project financing.
Next Steps for Prospective UHNW Clients
If you are evaluating these managers in 2026, the first step is to request a Request for Proposal (RFP). This document should require the bank to demonstrate how they would handle your specific "Concentration Risk" (e.g., too much wealth in one stock) and their strategy for "Generation Skipping" tax planning.
Before committing, it is advisable to meet not just the lead advisor, but also the specialists in trust and estate law and the "portfolio construction" experts who will be doing the actual trading. The strength of a UHNW relationship lies not in the brand name, but in the specific team’s ability to communicate complex strategies to your family and your existing legal advisors.