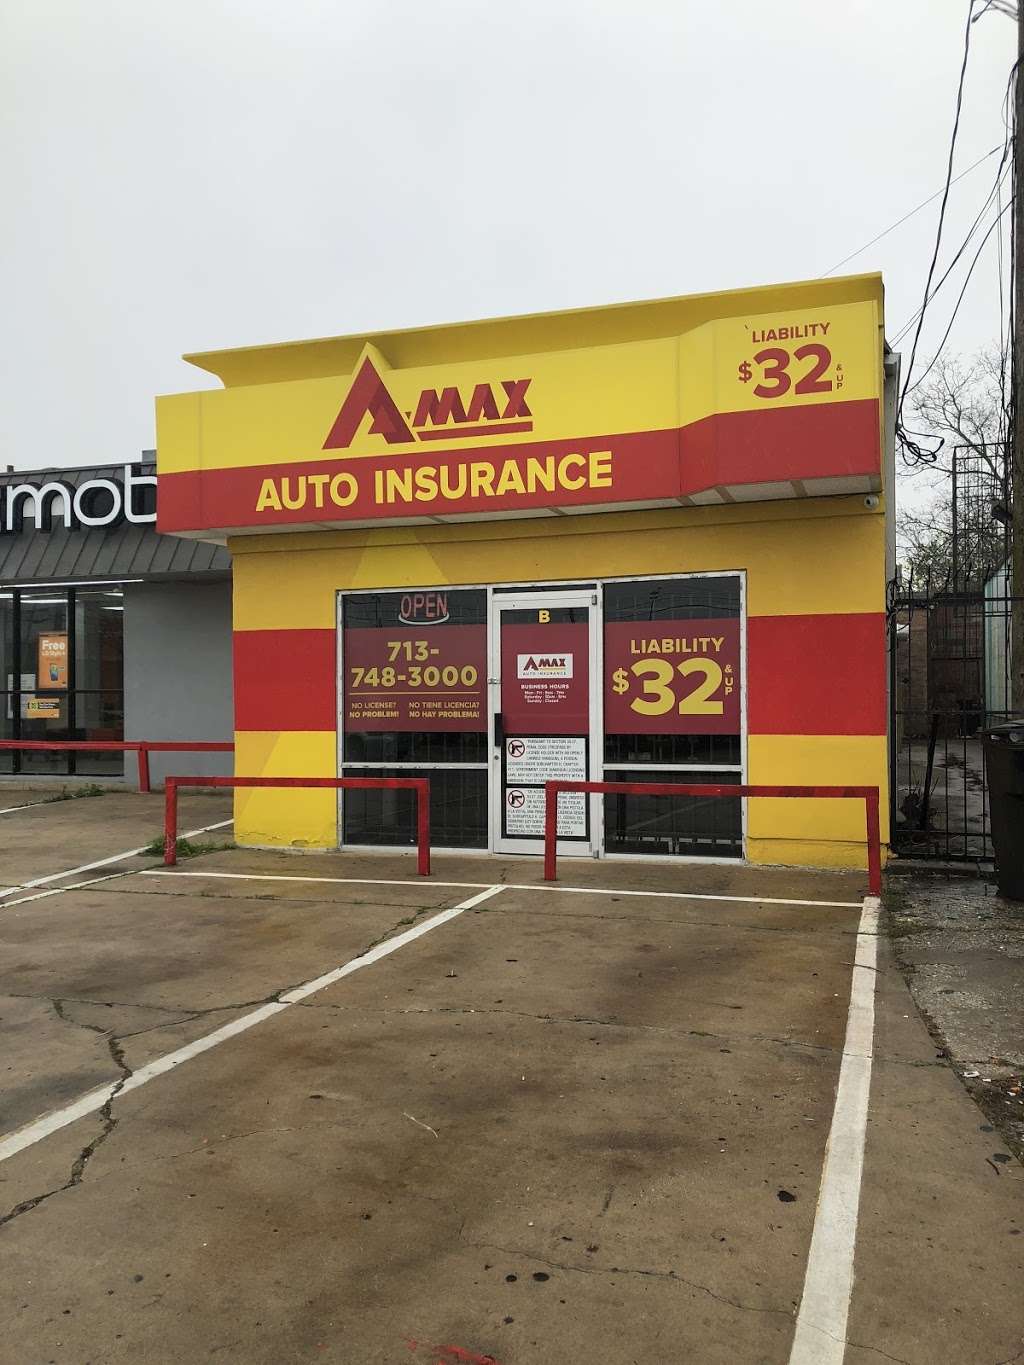
A-Max Auto Insurance in Mesquite functions as an independent agency that shops for competitive rates across more than 30 different insurance carriers. They specialize in affordable, non-standard auto insurance for high-risk drivers, offering everything from basic liability and SR-22 filings to comprehensive coverage and commercial policies tailored for Texas motorists.
Understanding the A-Max Agency Model in Mesquite
To understand A-Max Auto Insurance in Mesquite, one must first distinguish between an insurance carrier and an insurance agency. A-Max is an independent agency, meaning they do not underwrite the policies themselves. Instead, they act as a bridge between the consumer and a variety of insurance companies such as Progressive, Foremost, and Bristol West. This model is particularly beneficial in a city like Mesquite, where the demographic of drivers is diverse, ranging from daily commuters to Dallas to local small business owners.
In the 2026 insurance landscape, the ability to compare multiple quotes simultaneously has become a necessity. As vehicle technology has advanced and repair costs have risen, premiums in the Dallas-Fort Worth (DFW) metroplex have seen significant adjustments. A-Max leverages its partnership with dozens of carriers to find the "Maximum" savings—hence the name—by filtering through different risk pools. If one carrier raises rates due to a high volume of claims in the North Texas region, A-Max can pivot a customer to a different provider that may have a lower risk exposure at that time.
The Mesquite locations specifically cater to a "non-standard" market. This term refers to drivers who might struggle to find coverage through traditional "preferred" carriers like State Farm or Allstate. Reasons for needing non-standard insurance include a history of accidents, a lapse in previous coverage, a poor credit score, or the need for a state-mandated SR-22 filing. By focusing on this niche, A-Max has established itself as a primary resource for Mesquite residents who need to remain legal on Texas roads without paying the exorbitant "penalties" often found with standard insurers.
Texas Minimum Liability and Mesquite Requirements
Operating a vehicle in Mesquite, Texas, requires adherence to the state’s financial responsibility laws. As of 2026, Texas maintains strict enforcement of insurance requirements through the TexasSure database, which allows law enforcement to instantly verify a vehicle's insurance status via its license plate.
The current minimum liability requirements in Texas, often referred to as 30/60/25, are the foundation of the policies A-Max provides in Mesquite:
- $30,000 for Bodily Injury per person: This covers medical expenses for a single person you injure in an accident where you are at fault.
- $60,000 for Bodily Injury per accident: This is the total cap the insurance will pay for all people injured in a single accident.
- $25,000 for Property Damage: This covers the repairs to the other person's vehicle or property (like a fence or storefront) that you damage.
For many Mesquite residents, especially those navigating the heavy traffic near the Town East Mall or the I-635 interchange, these minimums may feel insufficient. A-Max agents are trained to explain the "gap" between these minimums and the actual costs of modern vehicles. For instance, if you are at fault in an accident involving a 2026 electric vehicle, $25,000 in property damage coverage might not even cover half of the repair costs. A-Max explains these risks and offers "stepped-up" liability limits to protect personal assets from lawsuits.
Coverage Deep Dive: Beyond the Basics
While many customers visit A-Max for the lowest possible price to get their tags or renew their registration, the agency offers a full suite of products. Understanding these options is critical for protecting a vehicle in the unpredictable North Texas environment.
Comprehensive and Collision Coverage
In Mesquite, weather is a significant factor in insurance costs. The region is prone to severe hailstorms and occasional tornadic activity. Comprehensive coverage is vital here as it protects against "acts of God," including hail damage, falling tree limbs, and flooding. It also covers theft, which remains a concern in urbanized areas of the DFW metroplex.
Collision coverage pays for damage to your own vehicle regardless of who is at fault. For residents who are still making payments on a car loan or lease—common for vehicles seen at Mesquite dealerships—collision and comprehensive are almost always required by the lienholder.
Uninsured and Underinsured Motorist (UM/UIM)
Texas has historically had a high rate of uninsured drivers. Despite the TexasSure system, many drivers in the Mesquite area may let their policies lapse. If you are involved in a hit-and-run or an accident with an uninsured driver on Highway 80, Uninsured Motorist coverage ensures your medical bills and car repairs are paid for by your own policy. A-Max frequently recommends this coverage because it provides a safety net that liability-only policies lack.
Personal Injury Protection (PIP) vs. Medical Payments
In Texas, insurers are required to offer PIP unless you reject it in writing. PIP covers medical expenses, 80% of lost wages, and even funeral expenses regardless of fault. A-Max agents often explain that PIP is a "no-fault" benefit, which is particularly useful for families in Mesquite who may not have robust private health insurance. Medical Payments (MedPay) is a more limited alternative that only covers direct medical and funeral costs.
The SR-22 and High-Risk Driver Solutions
One of the primary reasons Mesquite drivers seek out A-Max is for SR-22 certification. An SR-22 is not actually a type of insurance; it is a financial responsibility certificate filed by an insurance company with the Texas Department of Public Safety (DPS).
Drivers usually need an SR-22 if their license has been suspended due to:
- Driving Under the Influence (DUI) or Driving While Intoxicated (DWI).
- Driving without insurance (multiple offenses).
- Accumulating too many points on a driving record.
- Unpaid judgments related to vehicle accidents.
A-Max specializes in immediate SR-22 filings. In most cases, the agency can process the filing electronically, allowing the driver to present proof to the DPS or the court on the same day. Because A-Max works with non-standard carriers, they can often find an SR-22 policy at a fraction of the cost that a "preferred" carrier would charge—if the preferred carrier would even agree to write the policy at all.
Local Factors Affecting Mesquite Insurance Rates in 2026
When A-Max calculates a quote for a Mesquite resident, several localized factors influence the final premium. Geography plays a massive role in insurance mathematics.
- Commuting Risks: Mesquite is a bedroom community for Dallas. The heavy traffic on I-30 and the 635 Loop increases the statistical probability of a collision. Drivers with long commutes to downtown Dallas or North Dallas generally pay higher premiums than those who work within Mesquite city limits.
- Vehicle Theft and Vandalism Rates: Specific zip codes in Mesquite, such as 75150 or 75149, have different risk profiles for vehicle theft. A-Max's systems use historical data from these neighborhoods to adjust comprehensive coverage costs.
- Weather Patterns: As mentioned, the DFW "Hail Alley" necessitates higher comprehensive premiums compared to South Texas. By 2026, insurers have used more precise satellite and AI-driven modeling to price hail risk down to the specific street level.
- Local Infrastructure: Ongoing construction projects, such as those historically seen on the 635 East Project, often lead to higher accident rates in the short term, which can cause localized spikes in insurance premiums.
Comparison of Coverage Levels at A-Max
The following table outlines the common coverage packages Mesquite residents choose when visiting A-Max.
| Feature | State Minimum (Liability) | Enhanced Protection | Full Coverage (Finance Ready) |
|---|---|---|---|
| Bodily Injury | 30/60 Limit | 50/100 Limit | 100/300 Limit |
| Property Damage | $25,000 | $50,000 | $100,000 |
| Collision | Not Included | Optional | Included ($500-$1,000 Ded) |
| Comprehensive | Not Included | Optional | Included ($500-$1,000 Ded) |
| Uninsured Motorist | Optional (Often Rejected) | Included | Included |
| Roadside/Towing | No | Optional | Usually Included |
| Best For | Older cars, tight budgets | Daily commuters, asset protection | Financed/Leased or new cars |
Pricing and Discounts for 2026
In 2026, the average cost of insurance in Texas has been influenced by a 15% increase in vehicle parts and labor costs over the preceding three years. However, A-Max utilizes several discount structures to keep rates manageable for the Mesquite community.
- Multi-Car Discount: Insuring two or more vehicles on the same policy can result in a significant percentage reduction.
- Defensive Driving: Drivers who complete a Texas-approved defensive driving course can often receive a 10% discount on their liability and collision premiums for up to three years.
- Prior Insurance: Even if your previous policy was with a competitor, having "continuous coverage" (no gaps) is one of the strongest indicators of lower rates.
- Paperless and Auto-Pay: In the digital-first environment of 2026, A-Max offers discounts for customers who receive documents electronically and set up automatic monthly drafts.
- Homeowners Discount: Even if A-Max only provides the auto policy, proof of homeownership in Mesquite can often trigger a "stability" discount from certain carriers.
The Claims Process and Customer Service
One common point of confusion is how to file a claim. Because A-Max is an agency, they do not pay the claim themselves. However, their Mesquite offices serve as a resource for clients who are unsure how to navigate the process.
If an accident occurs in Mesquite:
- Contact the Carrier Directly: Your policy ID card will list the actual insurance company (e.g., Alinsco, Empower, or Progressive). You should call their 24/7 claims line first to begin the investigation.
- Notify A-Max: While not strictly required for the claim to proceed, informing your A-Max agent allows them to advocate for you if the carrier is unresponsive or if you have questions about your deductible.
- Local Repairs: A-Max often has relationships with local Mesquite body shops, which can help expedite estimates, though the carrier usually provides a list of "preferred" repair facilities to guarantee the work.
Frequently Asked Questions
Can I get a policy at A-Max Mesquite without a Texas Driver's License?
Yes. A-Max is well-known for helping residents who have a Matricula Consular, an International Driver's License, or a license from another state. They specialize in finding carriers that accept alternative forms of identification, which is vital for the diverse international population in the DFW area.
Does A-Max offer commercial insurance for Mesquite small businesses?
A-Max offers commercial auto insurance for local businesses. Whether you are a contractor with a single truck or a small delivery fleet operating near the Mesquite Airport, they can shop for policies that include higher liability limits and cargo coverage required for commercial operations.
How quickly can I get proof of insurance?
In most cases, proof of insurance is provided immediately. Once the initial payment (down payment) is made, A-Max can email or text a digital insurance card, which is legally valid in Texas for registration and law enforcement purposes.
What happens if I miss a payment?
Non-standard carriers often have strict cancellation policies. If a payment is missed, the policy may enter a "grace period," but once it cancels, a "reinstatement fee" is usually required. A-Max agents in Mesquite can often help negotiate a "no-lapse" reinstatement if the payment is made within a few days of the due date.
Is A-Max cheaper than buying directly from a carrier?
Because A-Max has access to "agent-only" carriers that do not sell directly to the public, they can often find rates that are lower than those available on major comparison websites. Additionally, they can "bundle" unconventional risks that larger companies might decline.
Practical Recommendation for Mesquite Residents
For those living or working in Mesquite, the best way to utilize A-Max is to treat them as a consulting resource rather than just a storefront. Before visiting their locations on Military Parkway or Gus Thomasson Road, residents should gather their current policy's "Declarations Page." This allows the A-Max agent to perform an "apples-to-apples" comparison.
In the 2026 market, it is recommended to shop your rate every 12 months. Insurance companies frequently update their algorithms, and a carrier that was the most expensive for you last year might be the most competitive today due to changes in their North Texas risk appetite. If you have an SR-22 requirement, ensure you ask for a "non-owner" policy if you do not own a vehicle but need to keep your license active—this is a frequently overlooked, cost-saving strategy that A-Max agents can facilitate.