Finding the right renters insurance in Las Vegas, Nevada, involves balancing standard property protection with localized risks like desert weather extremes, flash flooding, and urban property crime rates. Renters insurance provides essential financial safety nets by covering personal belongings against theft, fire, and specific water damage, while also offering liability protection if someone is injured inside your rented apartment, condo, or single-family home. Furthermore, many Las Vegas landlords and property management companies explicitly require proof of an active policy before handing over the keys.
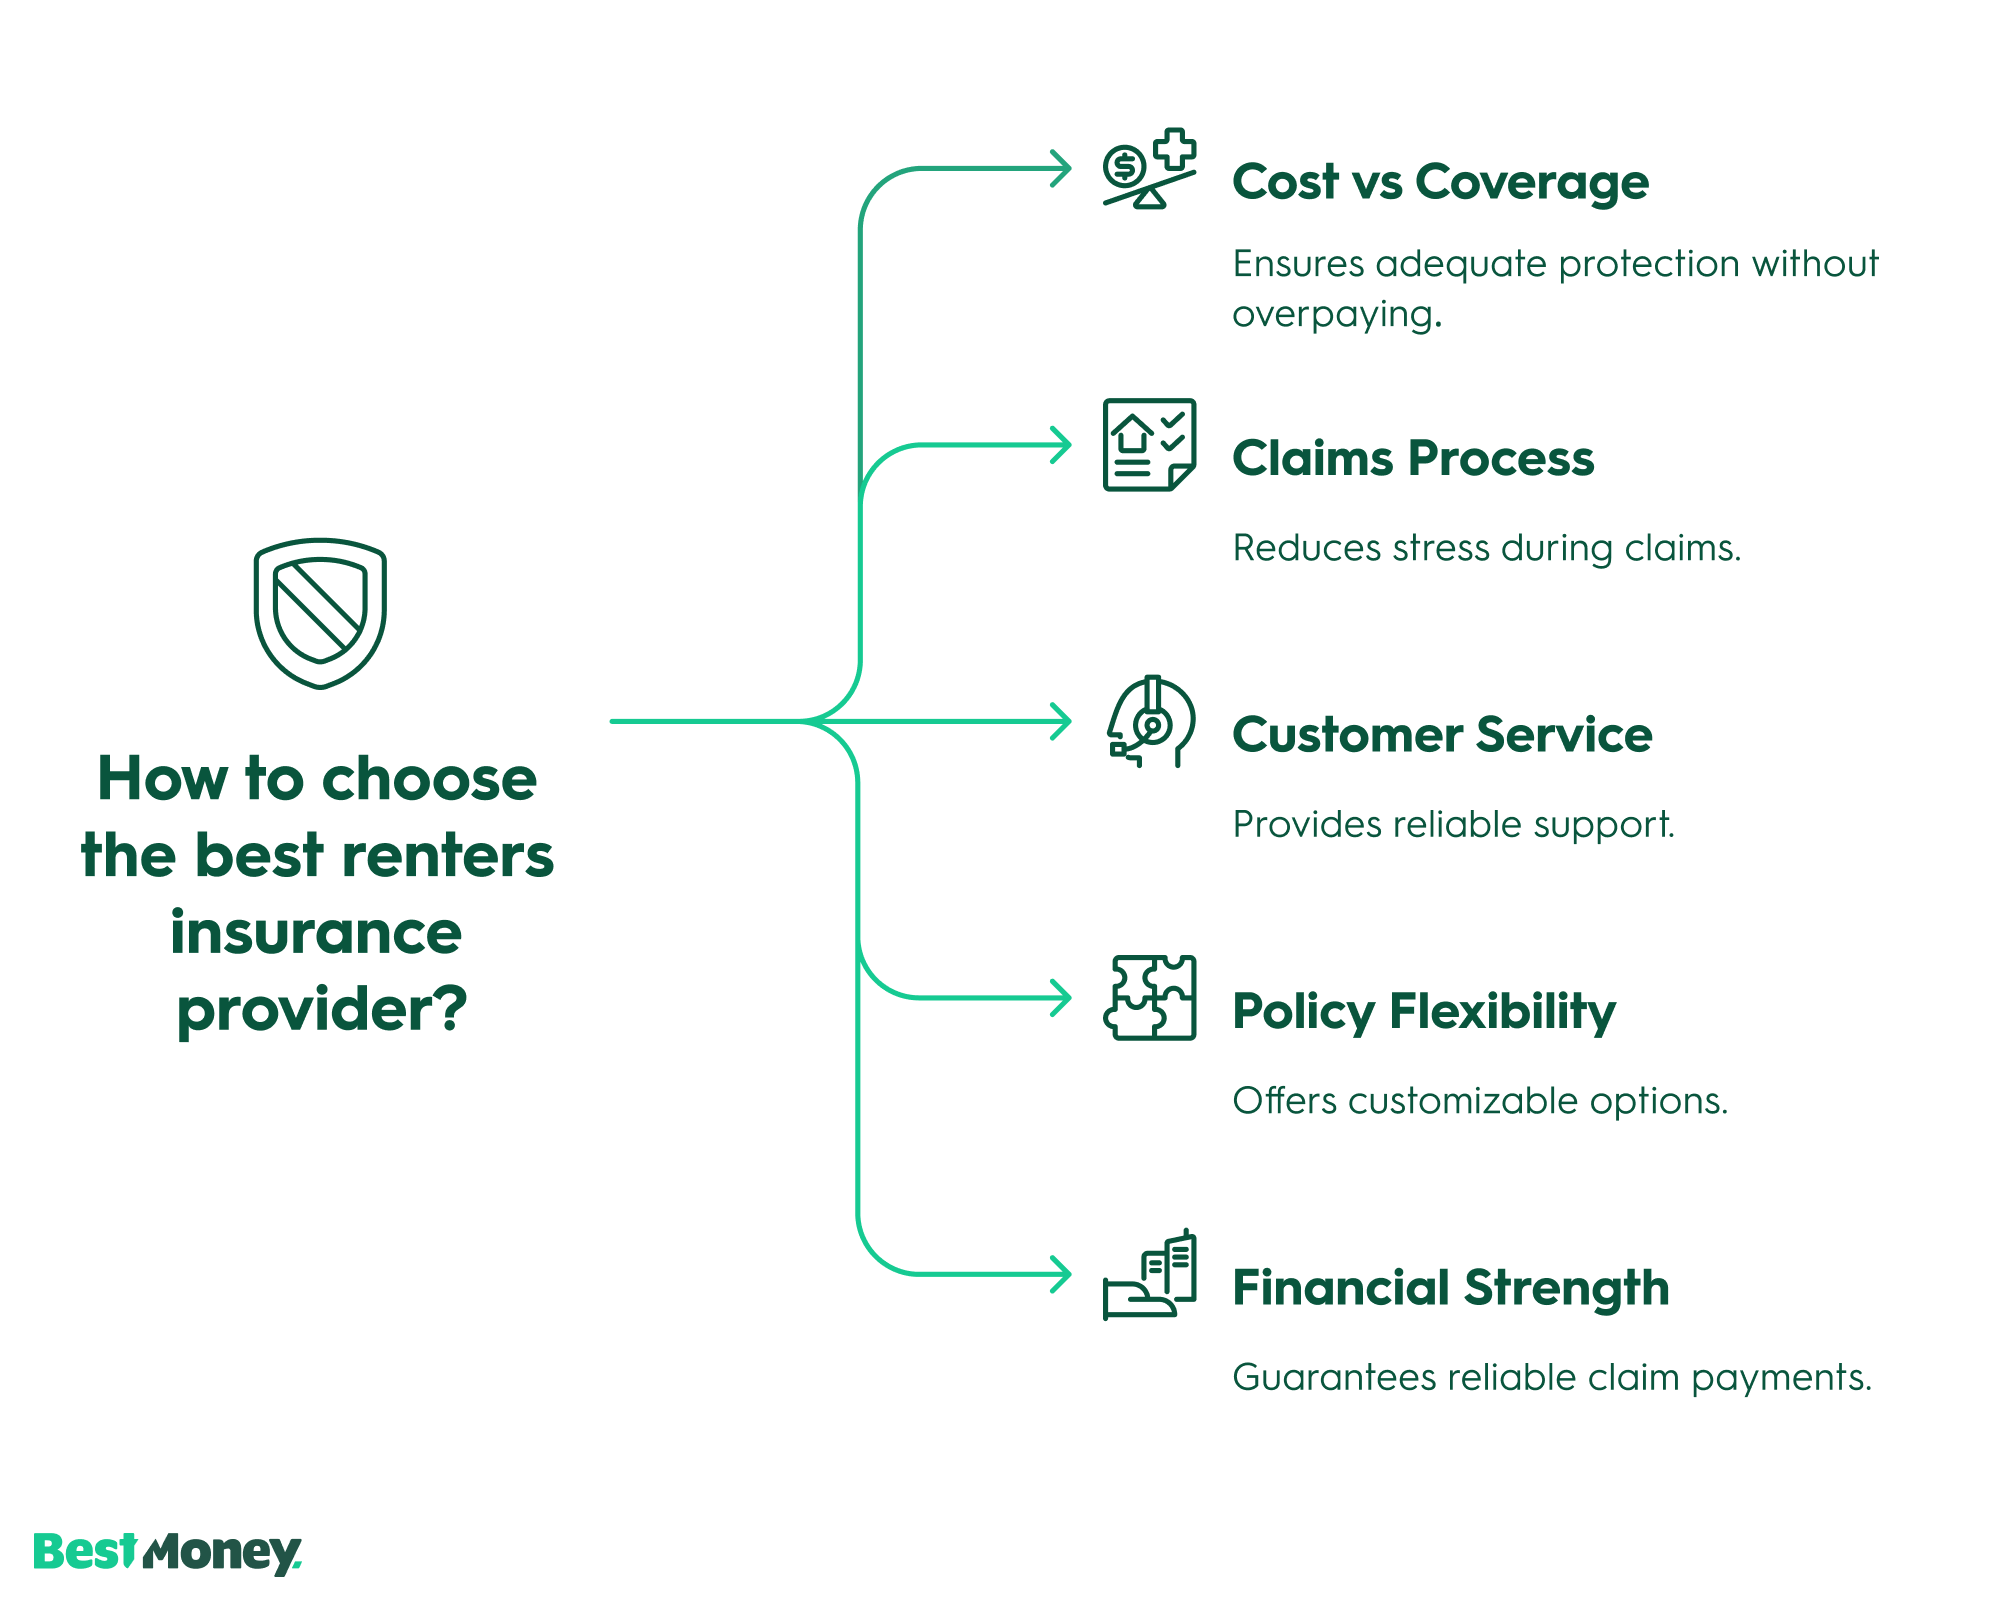
Evaluating providers in the Silver State requires looking beyond basic monthly premiums to examine customer service ratings, coverage customization, deductible options, and how smoothly claims are handled when disaster strikes. The five best renters insurance options available in Las Vegas for 2026 stand out for their comprehensive coverage, financial stability, and policyholder satisfaction, helping you protect your home and assets effectively.
Understanding Renters Insurance in Las Vegas
Before diving into specific carrier options, it helps to understand what standard renters insurance covers and why Las Vegas renters face unique underwriting considerations. A typical HO-4 renters insurance policy consists of three core coverage pillars: personal property, liability, and loss of use.
Personal property coverage protects your belongings—such as electronics, furniture, clothing, and appliances you own—against designated perils. These perils typically include fire, smoke, lightning, vandalism, theft, and certain types of water damage from internal plumbing failures. However, standard policies in Nevada often exclude flood damage caused by overflowing natural bodies of water or torrential desert downpours, meaning residents living in flood-prone areas like parts of the Las Vegas Valley may need to purchase separate flood insurance through the National Flood Insurance Program (NFIP).
Liability coverage steps in if you are legally responsible for bodily injury to another person or property damage to someone else's property, whether that occurs inside your rental unit or elsewhere. For example, if a guest slips on a wet floor in your Las Vegas apartment and breaks a wrist, your liability coverage helps pay for their medical bills and legal defense if you are sued. Loss of use coverage (additional living expenses) pays for hotel bills, restaurant meals, and temporary housing if your rental home becomes uninhabitable due to a covered disaster like a major apartment complex fire.
When shopping for coverage, you must also choose between Actual Cash Value (ACV) and Replacement Cost Value (RCV). ACV policies factor in depreciation, meaning a five-year-old television will be reimbursed at its current depreciated market value. RCV policies cost slightly more per month but pay what it actually costs to buy a brand-new item of similar kind and quality at current retail prices. For most Las Vegas residents, upgrading to replacement cost coverage provides significantly better financial protection.
Top 5 Renters Insurance Companies in Las Vegas
Evaluating insurance options requires analyzing financial strength, digital claims management, local agent availability, and user feedback. The following five carriers represent the top choices for renters residing in Las Vegas.
1. Lemonade: Best for Fast Digital Experience and Tech-Forward Renters
Lemonade has revolutionized the insurance industry with its artificial intelligence-driven platform, making it a top choice for tech-savvy Las Vegas renters who value speed and convenience. You can secure a policy in under two minutes via their mobile app or website, and claims are frequently processed and paid out instantly through automated algorithms without requiring tedious phone calls or paperwork.
- Pros: Extremely fast onboarding and claims processing; flat fee business model with transparent pricing; low starting rates for basic coverage; easy policy customization through the app.
- Cons: Limited availability for high-value items without scheduled riders; customer service relies heavily on digital chat rather than traditional in-person agents; strictly digital infrastructure may not suit renters who prefer speaking face-to-face.
- Best For: Millennials, Gen Z, and renters living in modern high-rises or managed apartment complexes across the Las Vegas Strip, Downtown, and Summerlin who manage everything via smartphone.
2. State Farm: Best for Local Agent Support and Bundling Discounts
State Farm maintains a robust physical presence throughout the Las Vegas metropolitan area, featuring numerous local agents who can provide personalized guidance. This makes State Farm ideal for renters who want to sit down with a professional to review liability limits, discuss specific local risk factors, and bundle their renters policy with auto insurance to maximize discounts.
- Pros: Exceptional network of local agents in Las Vegas and Henderson; extensive discount opportunities when bundling auto and renters insurance; highly rated financial stability; responsive local claims handling.
- Cons: Website and mobile app user interfaces are less streamlined than pure tech competitors; base rates can sometimes be higher unless multi-policy bundles are applied.
- Best For: Renters who value face-to-face customer service, want comprehensive personal property protection, and plan to bundle multiple insurance lines under one provider.
3. Progressive: Best for Customizable Policies and High-Value Property
Progressive is well-known for its robust policy customization tools and transparent quoting system. Through their online Name Your Price tool, Las Vegas renters can adjust their deductible and coverage limits to match their exact monthly budget. Furthermore, Progressive makes it easy to add specialized riders for expensive jewelry, firearms, art, or electronics frequently exposed to travel or loss outside the home.
- Pros: Highly flexible coverage options; transparent online quote generator; excellent options for scheduling high-value personal property; user-friendly online account management.
- Cons: Rates can vary significantly depending on credit history and specific Las Vegas zip codes; some discounts require enrollment in automatic payments or paperless billing.
- Best For: Renters with valuable collections, electronics, or specialized gear who want granular control over their policy deductibles and liability limits.
4. USAA: Best for Military Members, Veterans, and Their Families
For active-duty military personnel, veterans, and eligible family members stationed at or living near Nellis Air Force Base or Creech Air Force Base, USAA is the premier choice. USAA consistently ranks near the top of J.D. Power customer satisfaction surveys for property claims handling and offers specialized military perks that standard commercial insurers often omit.
- Pros: Specialized military coverage (such as zero deductible for gear damaged or stolen while on active duty); superior customer service ratings; highly competitive premium rates; comprehensive digital and phone support.
- Cons: Strictly restricted eligibility criteria (must be military, veteran, or an immediate family member); physical brick-and-mortar office availability is limited outside of military hubs.
- Best For: Military families, airmen, and veterans residing in the Las Vegas valley who qualify for membership and want industry-leading customer support.
5. Allstate: Best for Add-On Coverages and Identity Theft Protection
Allstate rounds out the top choices by offering comprehensive standard coverage coupled with unique optional endorsements. Las Vegas renters can enhance their policies with add-ons such as identity theft restoration, green improvement coverage, and pet injury protection—a valuable feature for renters with dogs or cats requiring veterinary care after an accident in the home.
- Pros: Broad array of unique optional endorsements; rewarding loyalty programs like the eSmart discount; reliable mobile app for managing policies and filing claims.
- Cons: Standard premiums can trend slightly higher than competitors without applied discounts; customer satisfaction scores vary depending on the independent local agency managing the account.
- Best For: Renters looking for specialized protection features like pet injury coverage, identity theft monitoring, and robust liability limits.
Comparing Renters Insurance Providers in Las Vegas
| Provider | Starting Monthly Cost (Est.) | Replacement Cost Available? | Best Feature | Mobile App Rating |
|---|---|---|---|---|
| Lemonade | $12 – $18 | Yes | Instant digital claims payouts | Excellent |
| State Farm | $15 – $22 | Yes | Extensive local agent network | Good |
| Progressive | $14 – $25 | Yes | Highly customizable deductibles | Very Good |
| USAA | $10 – $15 | Yes | Military-specific property perks | Excellent |
| Allstate | $16 – $26 | Yes | Unique add-ons like pet injury | Good |
Note: Monthly premium estimates are generalized averages based on standard coverage limits ($30,000 personal property, $100,000 liability, $500 deductible). Actual rates in Las Vegas vary widely depending on your specific credit history, claims history, exact zip code, and building security features.
Key Factors That Influence Las Vegas Renters Insurance Rates
Insurance underwriters evaluate several risk variables when calculating your monthly premium in Las Vegas. Understanding these factors can help you lower your costs:
- Location and Zip Code: Urban areas with higher property crime or vehicle break-in statistics often command slightly higher premiums than quieter suburban master-planned communities like Summerlin, Green Valley, or Anthem.
- Building Construction and Safety Features: Apartments located within gated communities equipped with security guards, controlled access gates, fire sprinklers, smoke detectors, and burglar alarms frequently qualify for policy discounts.
- Deductible Amount: Choosing a higher deductible—such as $1,000 instead of $250—lowers your monthly premium, but requires you to pay more out-of-pocket before insurance kicks in during a claim.
- Credit-Based Insurance Score: Under Nevada regulations, insurance companies may utilize credit history as a rating factor to determine your financial reliability, directly influencing your final quoted price.
Common Mistakes to Avoid When Buying Renters Insurance
Navigating your first renters insurance policy or switching providers can lead to missteps. Avoiding these common errors ensures you remain fully protected:
- Underestimating Total Personal Property Value: Many renters fail to conduct a home inventory, grossly underestimating the cumulative replacement cost of their wardrobe, electronics, shoes, furniture, and kitchenware. Take a video walkthrough of your apartment and catalog high-value items to ensure adequate coverage limits.
- Assuming Roommates Are Covered: A standard renters insurance policy only covers the named insured and their immediate family members. If you live with roommates, each individual generally needs to secure their own separate policy unless the carrier explicitly permits multi-tenant underwriting.
- Overlooking Loss of Use Limits: Selecting a minimal loss of use limit can leave you stranded if an apartment fire forces you out for months. Ensure your policy provides enough funds to cover temporary housing in the competitive Las Vegas rental market.
Frequently Asked Questions About Las Vegas Renters Insurance
Do landlords in Las Vegas legally require renters insurance?
While Nevada state landlord-tenant law does not universally mandate renters insurance by statute, individual landlords and property management companies possess the legal right to require proof of an active policy as a mandatory condition of your lease agreement. Review your lease terms carefully before moving in.
Does standard renters insurance cover flash flooding in Las Vegas?
No. Standard HO-4 renters insurance policies exclude damage caused by surface water, flash floods, or overflowing natural storm channels. Because Las Vegas experiences intense summer monsoons and flash flood warnings, residents living in low-lying areas or ground-floor units should purchase a separate flood insurance policy.
How much personal property coverage do I typically need?
A good rule of thumb is to calculate the total cost required to replace every single physical item you own if your apartment was completely destroyed. Most renters discover they need between $30,000 and $50,000 in personal property coverage, though individuals with extensive tech gear, musical instruments, or designer wardrobes may require $100,000 or more.
Can I transfer my renters insurance policy if I move across town in Las Vegas?
Yes. Renters insurance policies are fully portable. If you move from a downtown high-rise to a suburban home in Henderson, you can easily transfer your policy by updating your new address with your insurer, though your monthly rate may adjust depending on the new zip code's risk profile.
Final Recommendations for Las Vegas Renters
Securing the best renters insurance in Las Vegas requires balancing your budget with adequate property and liability protection. If you value speed, mobile convenience, and minimalist policy management, Lemonade is an exceptional fit. If you prefer working directly with an established local agent to bundle policies and maximize discounts, State Farm provides unmatched stability and service.
Always review your lease requirements, complete a thorough home inventory, and choose a replacement cost policy to ensure your belongings are fully safeguarded against unexpected events in the desert city.