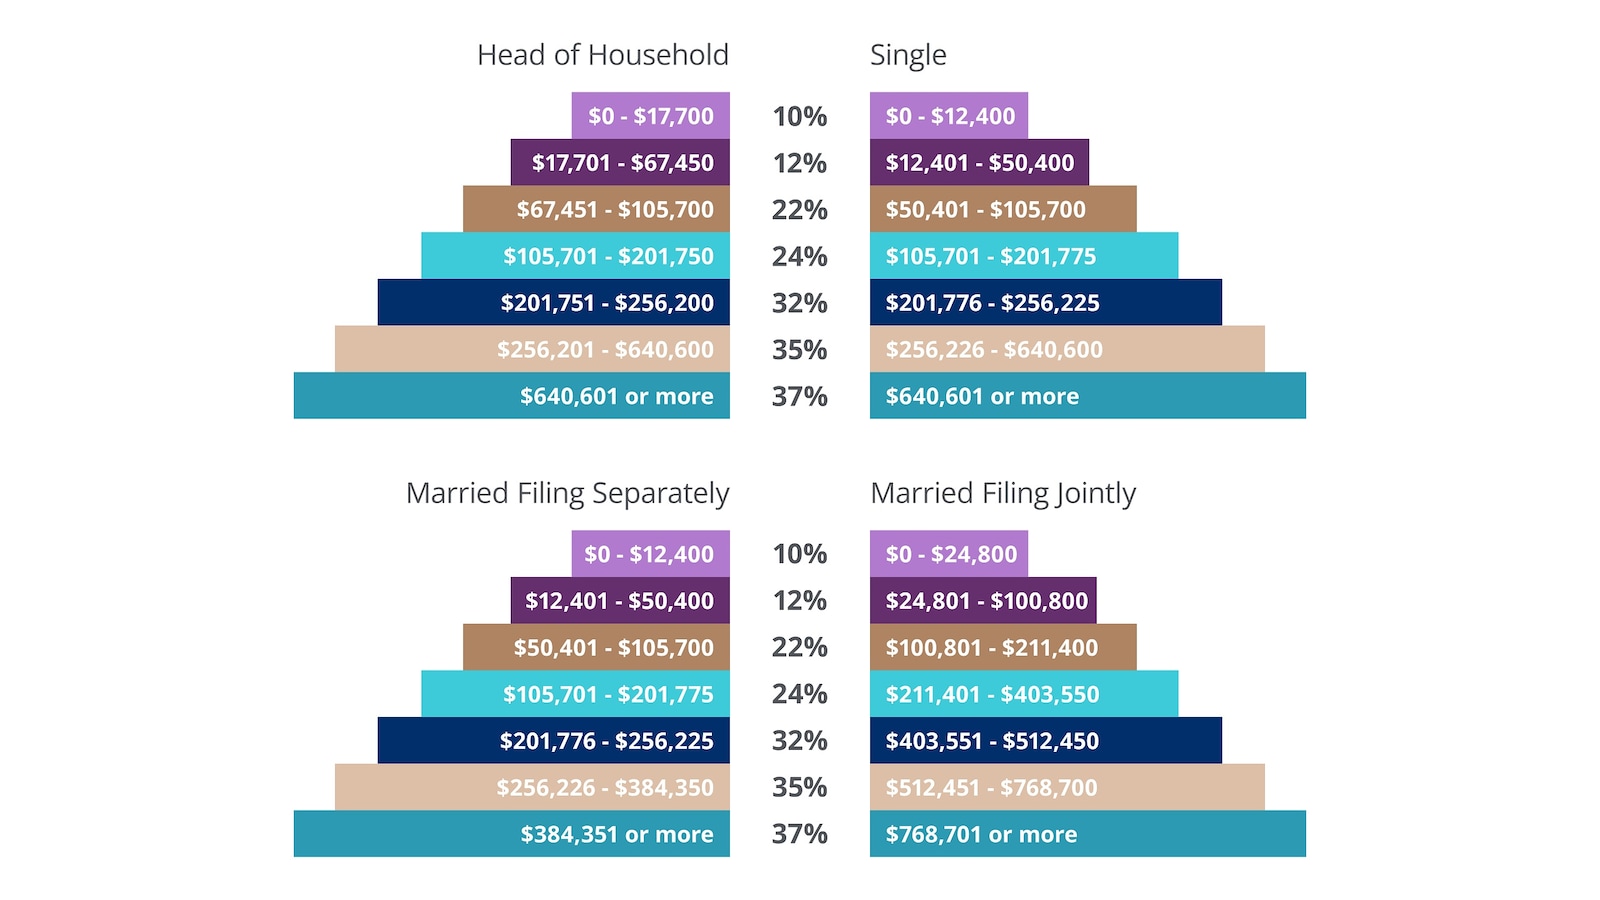
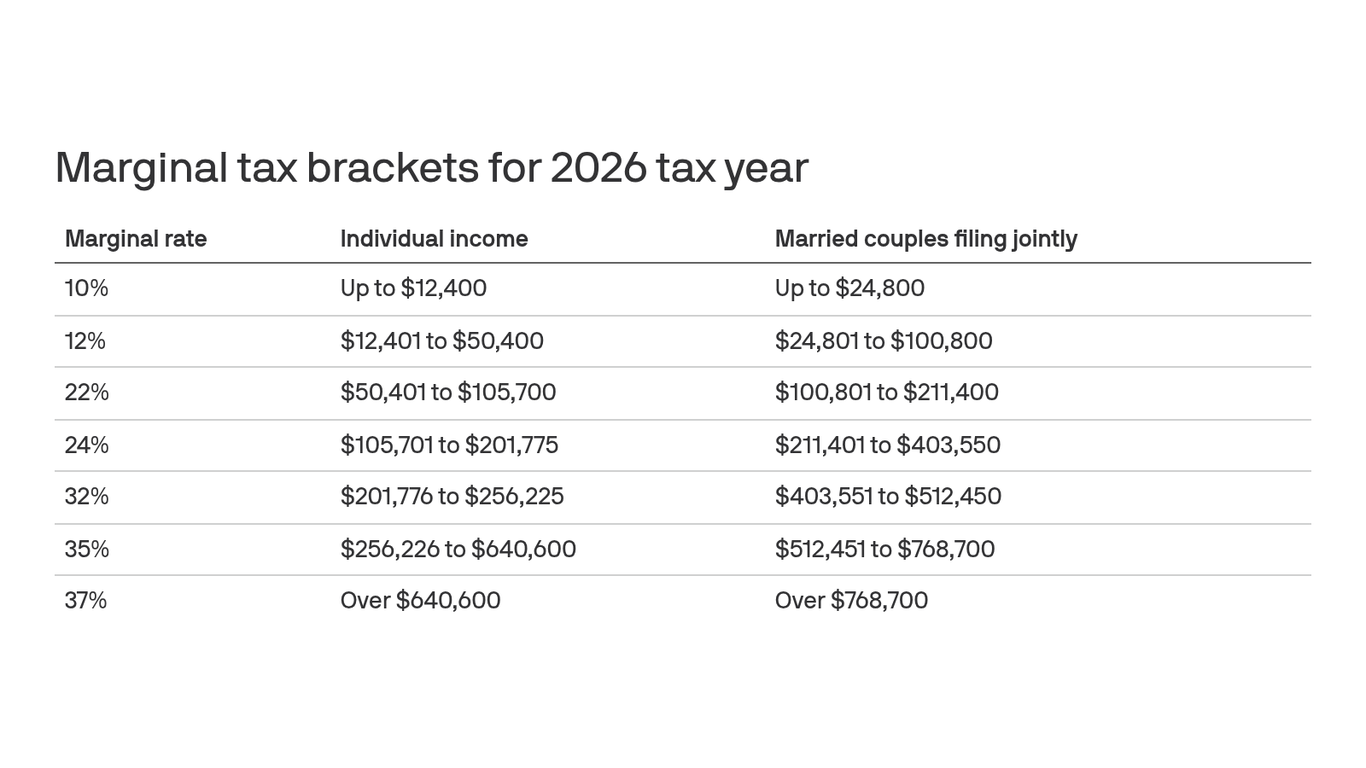
For the 2026 tax year, New York State tax rates for married couples filing jointly range from 4% to 10.9%. Most middle-income couples fall into the 5.5% or 6.0% brackets, following the full implementation of the state’s multi-year middle-class tax cut plan. High-earning households with income over $2.15 million are subject to supplemental top-tier rates.
Understanding the New York State Progressive Tax Structure
New York utilizes a progressive income tax system, meaning your income is not taxed at a single flat rate. Instead, as your taxable income moves through different thresholds, only the portion within each specific bracket is taxed at that corresponding rate. For married couples filing jointly (MFJ), these thresholds are wider than those for single filers, effectively preventing the "marriage penalty" at most state-level income tiers.
As we navigate the 2026 fiscal year, it is important to distinguish between New York State (NYS) taxes and New York City (NYC) resident taxes. While this guide focuses primarily on the state brackets, residents of the five boroughs must account for an additional local tax, which is also progressive and collected by the state on behalf of the city.
The 2026 tax year is particularly significant because it marks the full maturity of the Middle-Class Tax Cut legislation first initiated in 2017. This legislation gradually lowered rates for those in the middle tiers of the income spectrum to provide relief to working families. However, temporary tax increases for the state's highest earners—those making over $2.15 million—remain in effect through legislation extended in recent budget cycles.
2026 New York State Tax Brackets: Married Filing Jointly
The following table outlines the tax rates and income ranges for married couples filing a joint return in New York for the 2026 tax year. These figures apply to New York State Taxable Income, which is your adjusted gross income minus your New York standard deduction or itemized deductions.
| Taxable Income Range (MFJ) | 2026 Tax Rate | Base Tax Amount + Rate on Excess |
|---|---|---|
| $0 – $17,150 | 4.00% | 4% of taxable income |
| $17,150 – $23,600 | 4.50% | $686 + 4.5% of excess over $17,150 |
| $23,600 – $27,900 | 5.25% | $976 + 5.25% of excess over $23,600 |
| $27,900 – $161,550 | 5.50% | $1,202 + 5.5% of excess over $27,900 |
| $161,550 – $323,200 | 6.00% | $8,553 + 6.0% of excess over $161,550 |
| $323,200 – $2,155,350 | 6.85% | $18,252 + 6.85% of excess over $323,200 |
| $2,155,350 – $5,000,000 | 9.65% | $143,749 + 9.65% of excess over $2,155,350 |
| $5,000,000 – $25,000,000 | 10.30% | $418,304 + 10.3% of excess over $5,000,000 |
| Over $25,000,000 | 10.90% | $2,478,304 + 10.9% of excess over $25,000,000 |
Note: The "Base Tax Amount" is the cumulative tax from all lower brackets. For very high earners, the "Benefit Recapture" (explained below) may adjust these calculations.
The New York State Standard Deduction for 2026
Before applying the tax brackets above, you must calculate your New York taxable income. Most married couples choose the standard deduction, which reduces the amount of income subject to tax.
For the 2026 tax year, the New York State standard deduction for Married Filing Jointly is $16,050.
It is important to note that New York’s standard deduction is separate from the federal standard deduction. Even if you itemize on your federal return, you may still choose to take the standard deduction on your New York return if it provides a greater tax benefit. However, if you itemized on your federal return, you are generally permitted to itemize on your New York return, provided you make the necessary state-specific adjustments (such as adding back state and local taxes paid).
The "Benefit Recapture" for High-Income Earners
New York employs a unique and often misunderstood mechanism known as Tax Benefit Recapture. This provision is designed to ensure that the highest-earning taxpayers do not receive the benefit of the lower tax brackets that apply to middle-income families.
Once a married couple’s New York Adjusted Gross Income (NYAGI) exceeds $107,650, the state begins to "recapture" the benefit of the lower tax rates. For those with incomes in the highest brackets (above $2,155,350), the recapture effectively applies a flat rate to the entire income.
For example, if your income puts you in the 6.85% bracket, the recapture mechanism adds a supplemental tax to your return that gradually eliminates the savings you gained from having your first few thousand dollars taxed at 4% or 5.5%. By the time you reach the top of the income scale, your entire income is effectively taxed at the top applicable marginal rate. This makes New York’s tax system much closer to a flat tax for the ultra-wealthy, while remaining progressive for the middle class.
New York City Resident Income Tax
If you and your spouse reside in any of the five boroughs of New York City, you are subject to New York City Resident Personal Income Tax in addition to the state tax. This tax is also progressive.
For 2026, the NYC tax rates for married filing jointly generally range from 3.078% to 3.876%.
When combined with the state's top rate of 10.9%, the highest-earning married couples in New York City face a combined local and state marginal tax rate of 14.776%. This is currently one of the highest combined sub-federal tax rates in the United States. NYC residents do not file a separate city return; the city tax is calculated on Form IT-201 alongside the state tax.
Impact of Federal Tax Changes in 2026
The 2026 tax year is a landmark period due to the expiration (or "sunset") of many provisions from the federal Tax Cuts and Jobs Act (TCJA) of 2017. Unless Congress passes new legislation, several federal changes will indirectly affect New York taxpayers:
- State and Local Tax (SALT) Deduction: The $10,000 cap on federal SALT deductions is scheduled to expire. This would allow New York couples to once again deduct the full amount of their state and city income taxes (or property taxes) on their federal returns, significantly lowering federal tax liability for many New Yorkers.
- Federal Standard Deduction: The federal standard deduction is expected to decrease by nearly half (adjusted for inflation), making it more likely that New York couples will choose to itemize their deductions at both the federal and state levels.
- Personal Exemptions: Federal personal exemptions are set to return. While New York has its own rules for exemptions (specifically for dependents), the broader federal landscape change will require couples to re-evaluate their withholding and estimated payments.
Credits That Reduce Your 2026 New York Tax Bill
The tax brackets tell only half the story. New York offers several significant tax credits that can dollar-for-dollar reduce the amount of tax you owe. For married couples filing jointly, the following are the most impactful:
- Empire State Child Credit: For couples with children aged 4 to 16, this credit is generally 33% of the federal child tax credit or $100 per child, whichever is greater.
- Household Credit: This is a small credit available to MFJ filers with a NYAGI of $32,000 or less.
- Earned Income Credit (EIC): New York’s EIC is equal to 30% of the federal earned income credit, providing substantial relief to lower-income working couples.
- Child and Dependent Care Credit: If you pay for childcare so you and your spouse can work, you may be eligible for this credit, which is a percentage of the federal childcare credit. In New York, this credit is refundable, meaning if it reduces your tax below zero, the state will send you a check for the difference.
Filing Requirements and Deadlines for 2026
To use the Married Filing Jointly brackets, you must have filed a joint federal return (with limited exceptions for certain non-resident statuses).
- Filing Deadline: The 2026 New York State income tax return is due on April 15, 2027.
- Extensions: You can obtain an automatic six-month extension to file (until October 15, 2027), but this does not extend the time to pay. Any tax owed must be paid by the April deadline to avoid interest and penalties.
- Electronic Filing: New York heavily encourages e-filing. Most taxpayers are required to e-file if they use tax preparation software or a professional preparer.
The New York Department of Taxation and Finance offers a Free File program for taxpayers under a certain income threshold, which typically allows MFJ couples with moderate incomes to file both state and federal returns at no cost.
Frequently Asked Questions
1. Does New York have a "Marriage Penalty" in its tax brackets?
For most taxpayers, New York does not have a marriage penalty. The income thresholds for Married Filing Jointly are exactly double those for Single filers in the lower and middle brackets. However, at the very highest income levels (the multi-million dollar tiers), the brackets do not always double, which can result in a higher tax liability for a married couple than if they were two single individuals with the same total income.
2. Can we file jointly for federal and separately for New York?
Generally, no. New York law requires your filing status on your state return to match your federal filing status. If you filed a joint federal return, you must file a joint New York return. The only common exception is if one spouse is a New York resident and the other is a non-resident.
3. What is the difference between NYAGI and Taxable Income?
New York Adjusted Gross Income (NYAGI) is your Federal Adjusted Gross Income with specific New York additions and subtractions (such as adding back out-of-state municipal bond interest or subtracting Social Security benefits). Taxable Income is your NYAGI minus your New York standard or itemized deduction and any applicable dependent exemptions.
4. Are Social Security benefits taxed in New York?
No. New York State does not tax Social Security benefits. If your federal AGI includes Social Security income, you are permitted to subtract that amount on your New York return before applying the tax brackets. Additionally, New York provides a pension exclusion of up to $20,000 for taxpayers aged 59½ or older on qualifying pension and annuity income.
5. How does the NYC tax work for people who work in the city but live in the suburbs?
Only residents of New York City are required to pay the NYC resident income tax. If you live in Westchester, Nassau, or elsewhere and commute into the city, you generally only pay New York State income tax (and any local taxes for your specific place of residence), not the NYC resident tax.
6. What happens if I lived in New York for only part of 2026?
You would file Form IT-203, the Nonresident and Part-Year Resident Income Tax Return. You will calculate the tax on your total income as if you were a resident, and then prorate the tax based on the percentage of income you earned while living or working in New York.
Final Recommendation for 2026 Tax Planning
As 2026 brings the full implementation of the middle-class tax cuts alongside the major shifts in federal law, married couples should proactively review their withholding. If you or your spouse recently received a significant raise or have substantial investment income, use the NYS Estimated Tax Calculator to ensure you are paying enough throughout the year.
Because of the sunsetting of federal TCJA provisions, 2026 is an ideal year to consult with a tax professional regarding itemized deductions. The potential return of the full SALT deduction could change your strategy for property tax payments and charitable giving. Always keep detailed records of any New York-specific subtractions, such as 529 plan contributions (up to $10,000 for MFJ) and interest on U.S. government bonds, as these can lower your taxable income bracket.