Evaluating AIG life insurance requires understanding its specific position as a global financial services organization, its product architecture, and how its underwriting process functions for different demographics. Securing an accurate quote involves navigating their specific digital tools, understanding the nuances of their term and permanent life offerings, and recognizing the critical financial strength ratings that underpin their stability as a long-term issuer.
Understanding AIG’s Market Position and Product Scope
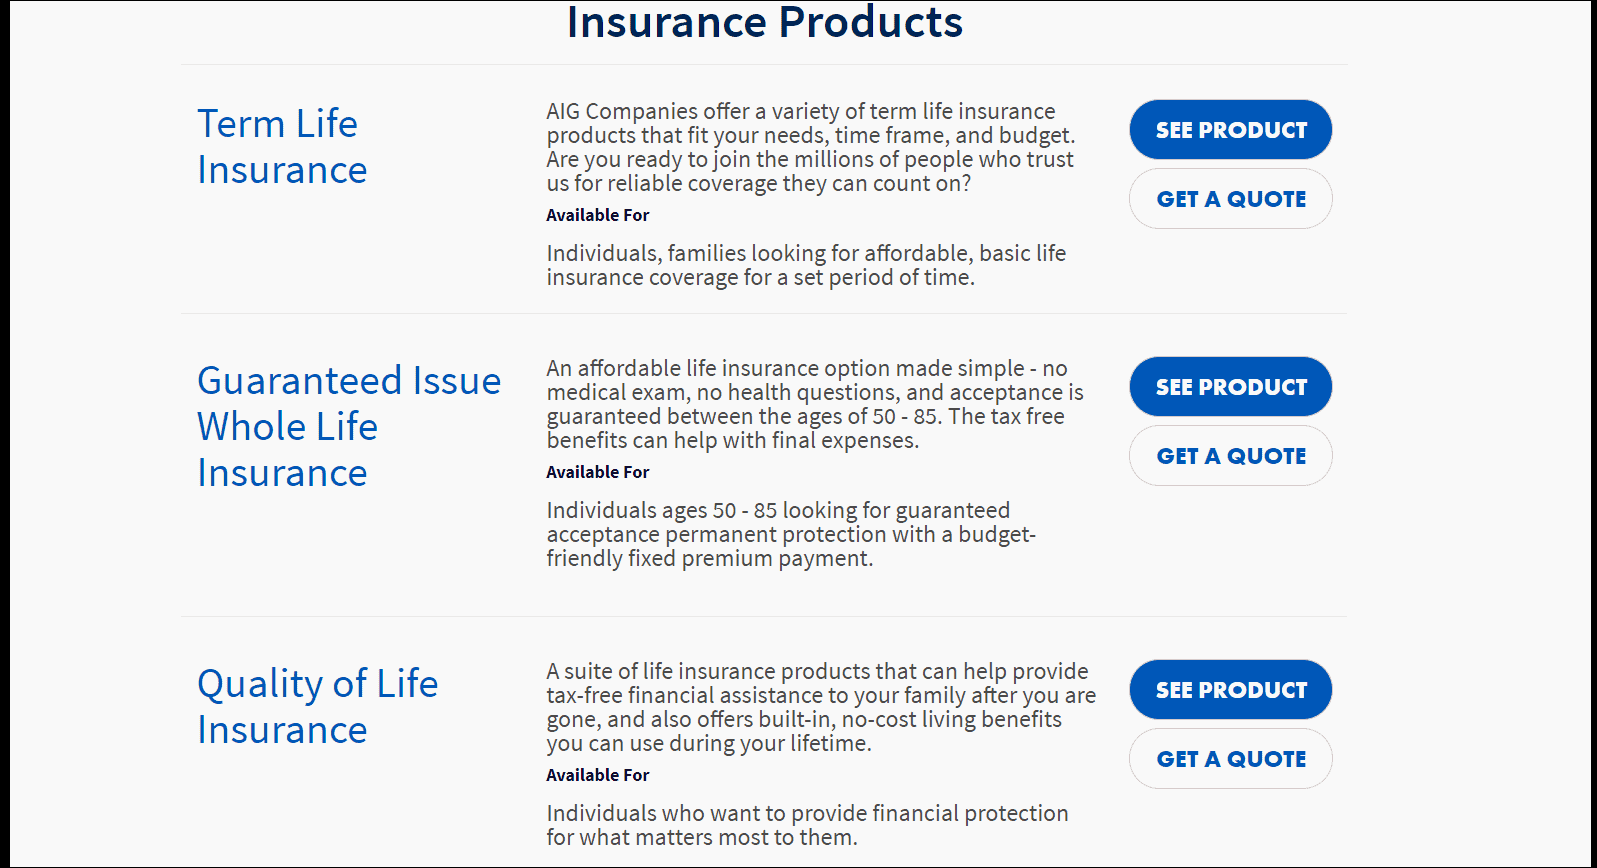
American International Group (AIG) is a multinational finance and insurance corporation that, through its life and retirement business, offers a variety of life insurance products. As of 2026, it is important to distinguish between the various entities under the AIG umbrella. Many of its life insurance offerings, particularly under the brand "Corebridge Financial," represent the evolution of AIG’s life and retirement division. When searching for reviews or quotes, applicants are often directed toward policies that emphasize flexibility, such as indexed universal life, term life, and accidental death and dismemberment products.
The primary appeal of AIG’s life products lies in their large-scale capacity to underwrite diverse risk profiles. Unlike smaller, niche insurers that may specialize only in "super-preferred" health classes, AIG maintains a broad underwriting appetite, making it a frequent candidate for individuals with complex medical histories or high-net-worth estate planning needs.
How to Obtain Accurate Life Insurance Quotes
Obtaining a quote from AIG or its affiliated brands usually follows a multi-tiered approach. Because life insurance is a customized financial product, "quick quotes" found on third-party comparison sites are rarely definitive.
- Digital Quote Tools: Most applicants begin with the online calculator tools provided on the official provider portal. These tools provide a rough premium estimate based on age, gender, tobacco use, and state of residence.
- The "Accelerated" Underwriting Path: Many of AIG’s term products utilize automated underwriting systems. This means that if you fall within certain age and health parameters, you may be able to bypass the traditional medical exam (the "paramedical" exam).
- The Full Underwriting Process: For larger face amounts or for applicants with significant health histories, a traditional application is required. This involves a phone interview and the collection of medical records.
To ensure the quote you receive is meaningful, you must be precise with your information. Underestimating pre-existing conditions or lifestyle risks (such as frequent international travel or hazardous hobbies) will result in a "rated" policy, which is significantly more expensive than the initial quote suggested.
Analyzing AIG Life Insurance Reviews
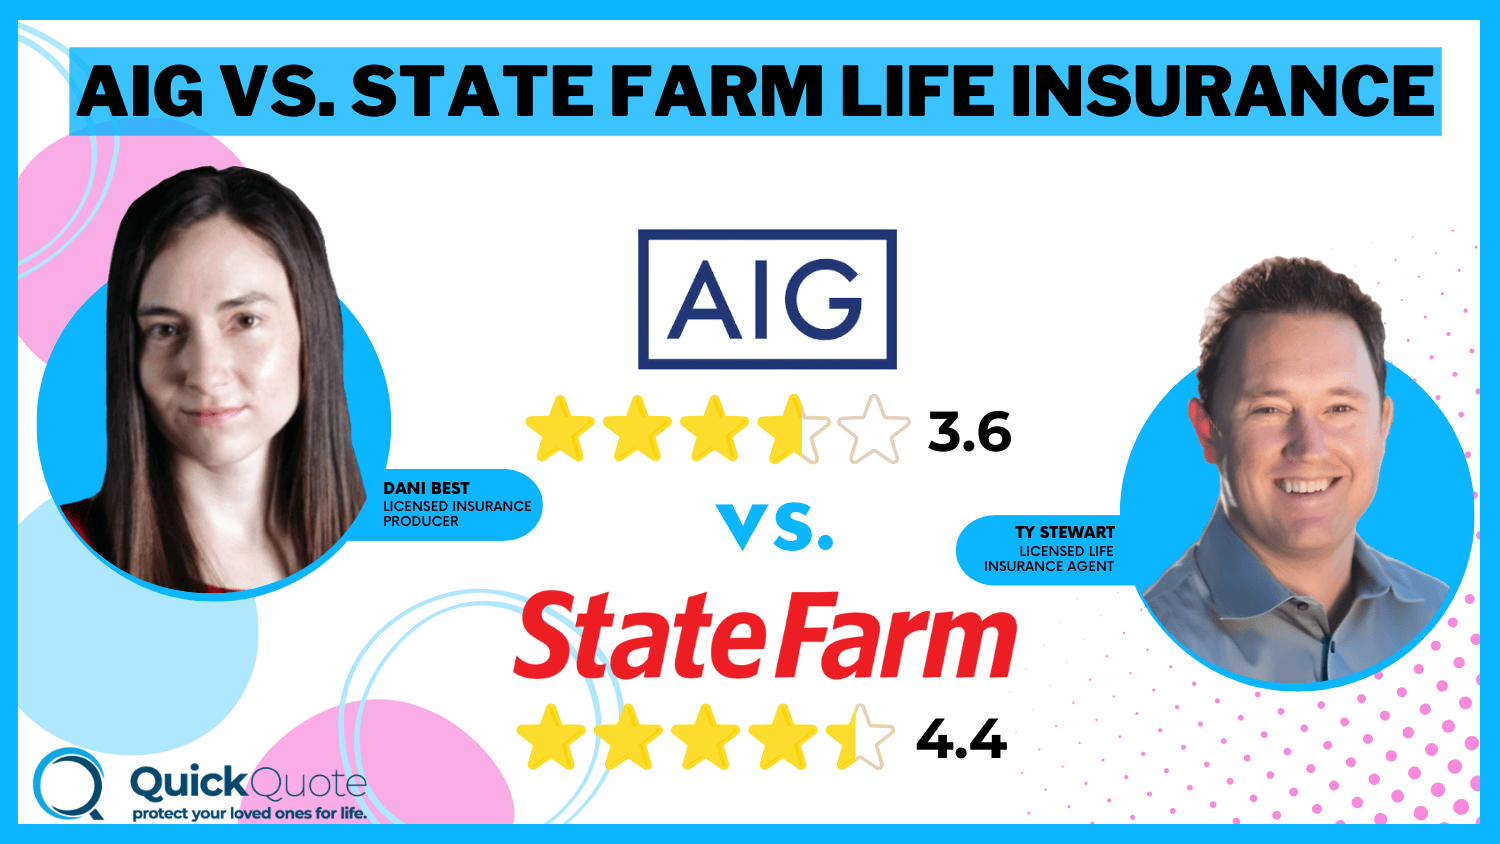
When analyzing customer and expert reviews for AIG, it is necessary to categorize the feedback into two distinct areas: customer service experience and financial strength.
Financial Strength: AIG maintains high ratings from agencies like A.M. Best, S&P, and Moody’s. These ratings are critical for life insurance because they indicate the company’s ability to pay out death benefits decades into the future. Consumers frequently cite this stability as a primary reason for choosing the carrier over newer, digital-only "insurtech" startups.
Customer Experience: Common critiques in the consumer landscape often revolve around the complexity of the underwriting process for permanent life products. Because products like Universal Life (UL) and Indexed Universal Life (IUL) are investment-linked, they are inherently more complex than simple term insurance. Reviews that suggest "poor service" often correlate with policyholders who did not fully understand the cost-of-insurance increases or the volatility associated with cash-value accumulation in these specific products.
Comparing AIG Life Insurance Options
| Product Type | Primary Purpose | Key Feature | Best For |
|---|---|---|---|
| Term Life | Income replacement | Fixed premiums for 10–30 years | Young families, debt coverage |
| Universal Life | Permanent coverage | Flexible premiums and benefits | Long-term estate planning |
| Indexed Universal Life | Cash value growth | Returns tied to market indices | Growth potential with protection |
| Guaranteed Issue | Final expenses | No medical exam required | Seniors with health limitations |
Prerequisites for Application
Before you initiate an application for AIG life insurance, prepare the necessary documentation to ensure the process remains smooth. The insurer will require:
- Identification: Government-issued photo ID (driver’s license or passport).
- Financial Data: Verification of income (W-2s or tax returns) if applying for a high death benefit amount to justify the "insurable interest."
- Medical Context: A comprehensive list of current medications, dosages, and the names/contact information of your primary care physicians.
- Beneficiary Details: Full legal names, dates of birth, and social security numbers of your intended beneficiaries.
Common Pitfalls in the Quoting Process
A frequent mistake applicants make is relying solely on an automated quote that assumes a "Preferred Plus" health classification. In reality, most applicants fall into "Standard" or "Standard Plus" categories. If you are applying for a policy in 2026, ensure that the quotes you are reviewing reflect your actual health history. If you have a history of hypertension, high cholesterol, or family history of heart disease, request that your broker or the quoting tool adjust for "Standard" or "Table-rated" premiums to avoid disappointment later in the application process.
The Role of Financial Professionals
Given the technical complexity of AIG’s permanent life products, working with an independent financial advisor or an insurance broker is often more effective than applying directly. An independent professional can represent multiple carriers, allowing you to see how AIG’s pricing stacks up against direct competitors like Prudential, Lincoln Financial, or Mutual of Omaha. They can also explain the "non-guaranteed" elements of IUL policies, which are often misunderstood by policyholders.
Managing Your Policy
Once a policy is in force, the relationship with AIG becomes administrative. Policyholders should utilize the company's online portal to monitor cash values (if applicable), update beneficiary designations, and set up automated premium payments. In 2026, the shift toward mobile-friendly management tools has increased, making it easier for policyholders to check their status. It is recommended to perform an annual policy review—not necessarily to buy more coverage, but to ensure that your coverage amounts still align with your changing financial liabilities, such as mortgage balances or changes in family size.
Frequently Asked Questions
1. Does AIG require a medical exam for all applicants? No, AIG offers "accelerated" underwriting for specific term life products, which may allow healthy applicants to bypass the medical exam. However, if you are older or seeking a high death benefit, a medical exam is generally mandatory to confirm insurability.
2. How do I know if AIG is financially stable? AIG maintains "A" (Excellent) or higher ratings from major credit rating agencies. These ratings are publicly available and updated annually. They reflect the company’s ability to meet its long-term financial obligations, which is the most critical factor in life insurance.
3. Are online quotes binding? No, online quotes are estimates. Your final premium is determined only after you complete the formal application, undergo underwriting, and are approved by the insurance company’s medical and financial risk teams.
4. Can I use AIG life insurance for business planning? Yes, AIG’s permanent products are frequently used for "Key Person" insurance, buy-sell agreements, and executive bonus plans. Because these are complex financial arrangements, it is standard practice to involve a tax attorney or a certified financial planner.
5. What happens if I stop paying premiums? For term insurance, your policy will generally lapse and the coverage will end. For permanent products with cash value, there may be "non-forfeiture" options that allow the policy to continue for a shorter period or with a lower face amount, depending on the accumulated cash value.
Next Steps for Interested Applicants
If you are currently evaluating AIG, the most effective next step is to determine your specific insurance needs—term vs. permanent—and consult with an independent insurance agent. Provide your medical history truthfully to receive a realistic premium estimate. Once you have a quote that fits your budget, verify that the coverage amount is sufficient to cover your current debt obligations and future income replacement needs.