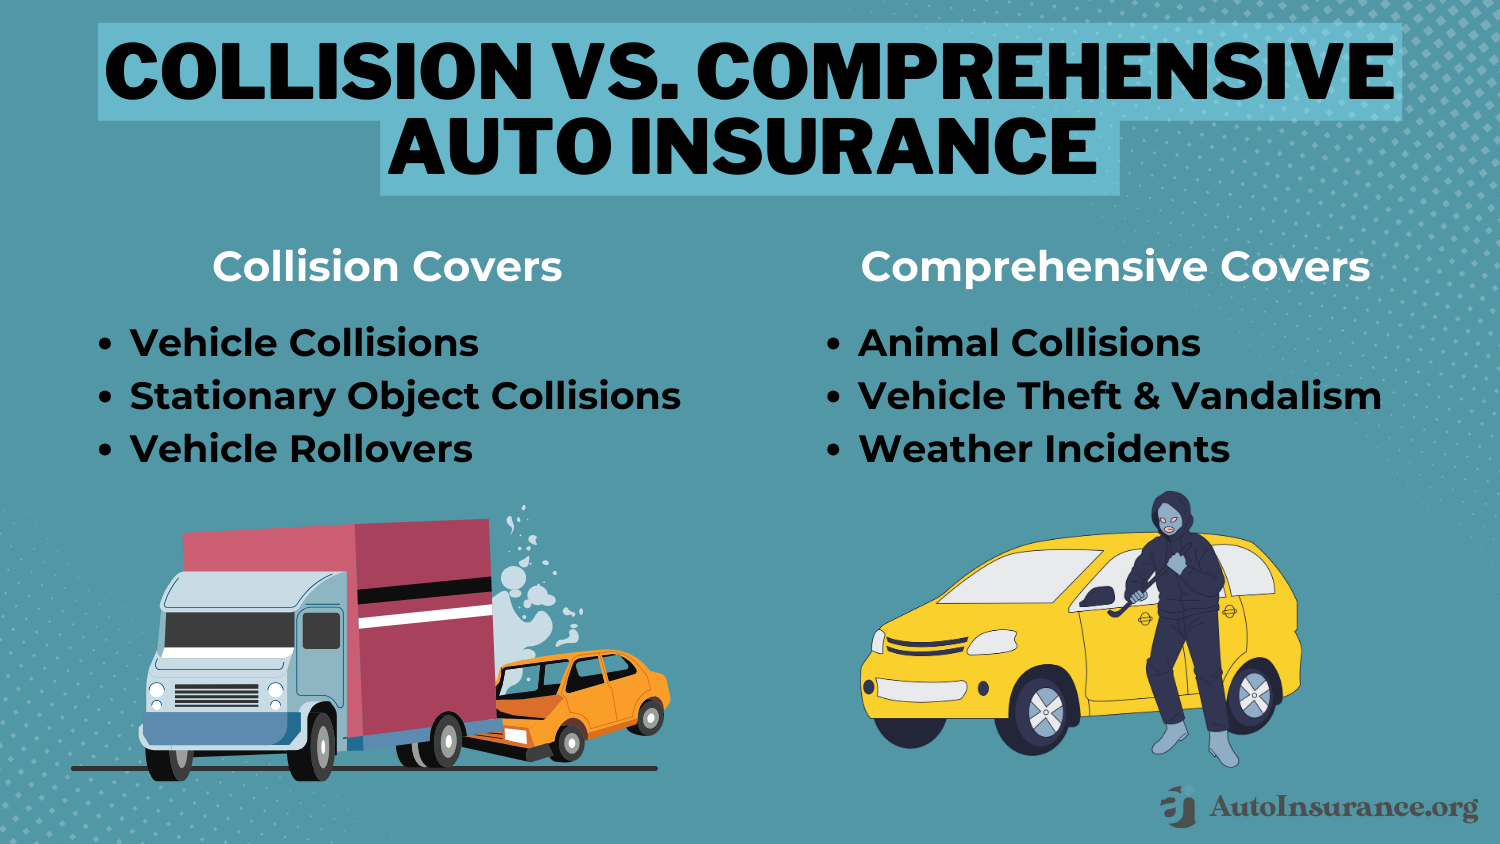
Finding affordable auto insurance options in Monroe, Louisiana requires balancing state-mandated coverage requirements with competitive pricing from local and national carriers. Drivers in Ouachita Parish can secure lower rates by comparing quotes from top insurers, maximizing eligible discounts, adjusting comprehensive and collision deductibles, and maintaining continuous coverage under Louisiana law.
Understanding Louisiana Auto Insurance Requirements
Before shopping for car insurance in Monroe, drivers must understand the statutory baseline set by state law. Louisiana requires all registered motor vehicles to carry evidence of financial responsibility, typically fulfilled through a minimum-liability auto insurance policy issued by a carrier licensed by the Louisiana Department of Insurance.
| Coverage Type | Statutory Minimum Limit |
|---|---|
| Bodily Injury (Per Person) | $15,000 |
| Bodily Injury (Per Accident) | $30,000 |
| Property Damage (Per Accident) | $25,000 |
This statutory requirement is commonly designated as 15/30/25 liability limits:
- $15,000 for bodily injury or death to one person in a single accident.
- $30,000 total for bodily injury or death to two or more people in a single accident.
- $25,000 for damage to property of others in a single accident.
The Limits of State-Minimum Coverage
While a 15/30/25 policy satisfies the legal mandate to register a vehicle at the Louisiana Office of Motor Vehicles, state-minimum coverage rarely offers complete financial protection. Modern vehicle replacement costs and medical expenses frequently exceed these statutory caps. If you cause an accident along heavily traveled routes like Interstate 20 or Highway 165 that results in major structural damage or serious injuries, medical bills and repair costs beyond $15,000 or $25,000 become your personal personal financial responsibility.
Carriers in Monroe routinely offer higher liability limits, such as 50/100/50 or 100/300/100, which significantly increase financial protection for modest additions to your monthly premium.
Uninsured/Underinsured Motorist (UM) Options
Louisiana law mandates that insurers offer Uninsured/Underinsured Motorist (UM) coverage on every policy issued in the state. Because Louisiana historically experiences a higher-than-average percentage of uninsured drivers, carrying UM coverage is critical.
UM coverage pays for your medical expenses, lost wages, and pain and suffering if you are struck by a hit-and-run driver or a motorist who lacks adequate insurance. By state law, UM coverage will automatically be included in your quote at limits matching your bodily injury coverage unless you specifically sign an official waiver form selecting lower limits or rejecting the coverage entirely.
Factors Influencing Auto Insurance Rates in Monroe and Ouachita Parish
Auto insurance premiums are calculated using complex actuarial data tailored to specific geographic zones. Drivers in Monroe experience specific regional factors that influence baseline premiums compared to national averages.
- Monroe Rate Influence Factors:
- Severe Weather & Floods
- High Traffic Corridors (I-20/US-165)
- State Legal & Claims Framework ("No Pay No Play")
- Credit Scores & History
Severe Weather and Environmental Hazards
Monroe lies in North Louisiana's Ouachita River basin, exposing vehicles to localized severe storms, hail damage, falling tree limbs, and flash flooding. Comprehensive insurance coverage protects your vehicle against non-collision environmental losses, including water damage caused by heavy rain events. Because weather risks directly affect loss ratios, carriers adjust comprehensive rates across Ouachita Parish zip codes accordingly.
Local Traffic Density and Commute Patterns
Commute times and traffic flow directly impact accident statistics. Key traffic arteries—such as the Interstate 20 corridor connecting West Monroe and Monroe, Louisville Avenue, and DeSiard Street near University of Louisiana Monroe (ULM)—see dense traffic during morning and evening rush hours. Higher traffic volumes increase accident frequencies, which leads insurers to set rates based on specific zip codes (such as 71201, 71202, and 71203).
Louisiana's "No Pay, No Play" Statute
Louisiana enforces a strict statutory rule known as the "No Pay, No Play" law (Louisiana Revised Statutes § 32:863.1). Under this law, uninsured drivers involved in motor vehicle accidents cannot collect the first $15,000 of bodily injury damages and the first $25,000 of property damage, regardless of who caused the accident.
While there are limited statutory exceptions (such as accidents caused by out-of-state drunk drivers or hit-and-run incidents), this rule underscores the importance of maintaining uninterrupted insurance coverage in Monroe. Lapsing on your insurance policy not only exposes you to state fines and registration suspensions but also forfeits key legal rights if an uninsured driver injures you.
Credit-Based Insurance Scores
In Louisiana, auto insurance carriers are legally permitted to use credit-based insurance scores as a rating factor when setting rates for new policies and renewals. Insurers rely on credit histories to predict the likelihood of future claims. Maintaining a high credit score can reduce annual auto insurance costs by hundreds of dollars in Monroe, whereas poor credit histories often lead to higher baseline rates.
Top Providers for Cheap Car Insurance in Monroe
Finding cheap car insurance in Monroe requires reviewing national insurance companies alongside local and regional carriers. Rates vary based on driver demographics, vehicle types, and selected policy coverages.
National Insurance Carriers
- State Farm: Consistently ranks among the most competitive options in North Louisiana for full coverage and bundled policies. State Farm maintains a wide network of local captive agents throughout Monroe and West Monroe, making it a strong choice for drivers who prefer face-to-face service.
- GEICO: Known for low standard rates, direct online management, and strong military discounts. GEICO frequently offers affordable minimum-liability policies for low-risk drivers in Ouachita Parish.
- Progressive: Offers competitive rates for high-risk drivers, drivers with past accidents, or those needing an SR-22 filing. Their Name Your Price tool helps budget-conscious buyers build a policy that fits their monthly allocation.
- Allstate: Provides robust add-on coverages such as sound system insurance and dynamic roadside assistance. While its baseline rates can be higher, broad policy discounts can make Allstate competitive for families bundling home and auto policies.
Regional and Specialty Carriers
- Southern Farm Bureau Casualty Insurance: Available to members of the Louisiana Farm Bureau Federation. Farm Bureau frequently provides lower rates and personalized local underwriting for drivers residing in Ouachita and surrounding rural parishes.
- GoAuto Insurance: A Louisiana-based specialty insurer focused primarily on low-cost minimum liability coverage. GoAuto eliminates middleman agent commissions to offer low baseline rates, though options for non-standard add-ons may be more limited.
- Direct Auto Insurance: Specializes in accessible policies for drivers with lower credit scores, prior coverage lapses, or a history of moving violations. Direct Auto offers flexible payment schedules and convenient down-payment terms.
Comparing Auto Insurance Options in Monroe
Selecting the ideal insurer requires balancing initial premium costs against policy features, claims service quality, and local support. The following table provides a comparison of common coverage profiles available in Monroe:
| Carrier / Profile Category | Best For | Typical Pricing Tier | Key Strengths | Considerations |
|---|---|---|---|---|
| State Farm | Families & Bundled Policies | Moderate to Low | Broad local agent network, excellent discount options | Requires agent contact for certain policy adjustments |
| GEICO | Digital Shoppers & Low-Risk Drivers | Low | Competitive baseline quotes, user-friendly digital tools | Limited face-to-face storefront support in Ouachita Parish |
| Progressive | Drivers with Violations / SR-22 | Moderate | Strong telematics program (Snapshot), flexible options | Premium increases can occur rapidly following an at-fault accident |
| Southern Farm Bureau | Rural & Suburban Property Owners | Low to Moderate | Personalized local underwriting, stable policy pricing | Requires annual Farm Bureau membership fee |
| GoAuto Insurance | Minimum Liability Seekers | Lowest (Basic) | Direct-to-consumer pricing, low upfront cash requirement | Stripped-down basic coverage, fewer optional add-ons |
| Direct Auto Insurance | High-Risk / Credit-Challenged | Moderate to High | Low down payments, flexible payment schedules | Full coverage policies can carry higher total costs |
Actionable Strategies to Reduce Auto Insurance Premiums in Monroe
To secure the most competitive auto insurance rates in Ouachita Parish, drivers can implement targeted strategies that directly lower insurance company risk assessments:
- Premium Reduction Checklist:
- Bundle Auto with Homeowners or Renters Coverage
- Enroll in Carrier Telematics (Usage-Based Insurance)
- Raise Comprehensive and Collision Deductibles
- Complete an Approved Defensive Driving Course
- Audit Driver List and Remove Unnecessary Operators
- Maintain Continuous Coverage (Avoid Lapses)
1. Bundle Homeowners or Renters Insurance
Combining auto insurance with a homeowners policy, mobile home policy, or renters coverage through the same insurer is one of the most effective ways to lower total costs. Carriers in Louisiana frequently extend multi-policy discounts ranging from 10% to 25% across both policies.
2. Enroll in Telematics and Usage-Based Programs
Most major carriers—including Progressive (Snapshot), State Farm (Drive Safe & Save), and GEICO (DriveEasy)—offer usage-based insurance (UBI) programs. These programs use smartphone apps or OBD-II vehicle plugins to monitor driving habits like hard braking, late-night driving, speed compliance, and total mileage. Safe drivers in Monroe can earn immediate initial discounts with further savings applied at policy renewal.
3. Adjust Comprehensive and Collision Deductibles
If your auto loan is fully paid off, evaluate your vehicle's current market value relative to your policy deductibles. Raising physical damage deductibles from $250 or $500 up to $1,000 can lower the comprehensive and collision portion of your monthly premium by 15% to 30%. However, ensure you maintain sufficient cash reserves to cover the higher out-of-pocket expense if an accident occurs.
4. Leverage Student and Occupational Discounts
Monroe is home to major educational institutions like the University of Louisiana Monroe (ULM) and Louisiana Delta Community College. Full-time high school and college students under 25 who maintain a "B" average (3.0 GPA) or higher can qualify for Good Student Discounts. Additionally, major employers, military personnel, first responders, and certified teachers frequently qualify for occupational affinity discounts depending on the carrier.
5. Prevent Unintended Lapses in Coverage
In Louisiana, even a single day without coverage can lead to severe financial consequences. The Louisiana Office of Motor Vehicles tracks coverage electronically. If an insurer reports a cancellation, the state can flag your vehicle registration, levy administrative fines ranging from $50 to $500, and impose vehicle impoundment risks. Furthermore, insurance companies classify drivers with recent coverage lapses as high-risk, which significantly increases future monthly premiums.
Step-by-Step Guide to Purchasing Car Insurance in Monroe
Switching coverage or buying a new auto insurance policy requires careful planning to prevent accidental coverage gaps and avoid state fines. Follow these steps to secure compliant coverage in Monroe:
- Gather Data & Vehicle Details: Collect VIN, driver's license numbers, current policy info, and mileage.
- Select Coverage Limits & Add-ons: Decide between 15/30/25 minimum vs. full coverage (Collision/Comp/UM).
- Solicit Quotes & Apply Discounts: Obtain side-by-side quotes from at least 3 national and regional carriers.
- Verify License & Bind New Policy: Confirm carrier active status via the Louisiana Dept. of Insurance (LDI).
- Cancel Prior Policy Correctly: Set start date to overlap with cancellation date to prevent legal coverage gaps.
Step 1: Gather Vehicle and Driver Documents
Before starting the quote process, collect all necessary documentation:
- Driver’s license numbers for all household members.
- Vehicle Identification Numbers (VINs) for all listed automobiles.
- Current odometer readings and estimated annual commute distances.
- Declarations page from your existing auto policy (if applicable) to establish prior continuous coverage.
Step 2: Establish Your Target Coverage Profile
Determine whether your vehicle requires minimum liability or full coverage. If your car is financed or leased through a lender, the financial institution will require full coverage—including collision and comprehensive protection—along with maximum deductible caps (typically $500 or $1,000). If your vehicle is paid off, assess whether its current market value warrants paying for comprehensive and collision coverage.
Step 3: Request Quotes from Multiple Providers
Obtain quotes from at least three different insurance companies. Ensure that every quote lists identical coverage limits, deductibles, and endorsement choices so you can make an accurate, side-by-side comparison.
Step 4: Verify Carrier Standing with the LDI
Before making a down payment, confirm that your chosen carrier is licensed to operate in Louisiana. You can verify licensing status, review financial strength ratings, and check historical consumer complaint indices using the online portal at the Louisiana Department of Insurance.
Step 5: Bind the New Policy Before Canceling the Old One
To avoid coverage gaps that trigger OMV penalties, establish the effective start date of your new policy before canceling your existing policy. Once the new policy is active, contact your prior insurer to formally cancel the old contract and request a pro-rated refund of any prepaid, unearned premium. Keep your new physical or digital insurance card inside your vehicle at all times.
Frequently Asked Questions
What is the legal minimum auto insurance required in Monroe, LA?
Louisiana law requires drivers in Monroe to carry at least 15/30/25 liability insurance: $15,000 for bodily injury per person, $30,000 for bodily injury per accident, and $25,000 for property damage per accident.
While state minimums keep you legally compliant, they often do not fully cover major accidents. Drivers who can afford higher limits should strongly consider expanding bodily injury and property damage limits to safeguard personal savings and real estate assets from potential court judgments.
How does Louisiana's "No Pay, No Play" law impact uninsured drivers in Monroe?
Under Louisiana Revised Statute § 32:863.1, uninsured drivers cannot collect the first $15,000 in bodily injury damages and the first $25,000 in property damage from an at-fault driver's insurance policy.
This law means that if another driver hits your vehicle in Monroe, you cannot recover compensation for initial medical bills or repair costs if you failed to maintain valid insurance at the time of the collision. Maintaining continuous liability coverage protects both your health and your legal remedies.
Is flood damage to my vehicle covered under standard car insurance policies?
Standard basic liability auto insurance does not cover flood damage. Comprehensive coverage is required to protect your vehicle against floodwaters, rising water along the Ouachita River, hail damage, fallen tree limbs, or severe storm events.
If your vehicle carries comprehensive coverage on its declarations page, flood repairs or total loss cash values are covered up to the actual cash value (ACV) of the automobile, minus your selected deductible.
Can auto insurance companies in Louisiana use my credit score to determine rates?
Yes, Louisiana law allows auto insurance providers to use credit-based insurance scores when calculating baseline rates for drivers in Monroe.
Insurers use credit metrics as a predictive tool for financial risk and claim frequency. Improving your credit score over time by making prompt payments, reducing credit card balances, and resolving inaccurate credit report entries can directly lower your monthly auto insurance costs.
How can ULM students secure cheaper car insurance rates in Monroe?
Students attending the University of Louisiana Monroe (ULM) can lower auto insurance costs by maintaining a cumulative 3.0 GPA (or "B" average) to qualify for Good Student Discounts.
Additionally, students who leave their vehicle registered at their parents' primary address—or who leave their vehicle at home while living on campus more than 100 miles away—can qualify for lower "student away at school" rating categories. Comparing quotes across online providers like GEICO and State Farm often yields student-friendly rates.
Recommended Next Steps for Monroe Drivers
To lower your car insurance rates in Monroe while ensuring your policy complies with state law, take these next steps:
- Review your current declarations page: Verify your existing liability limits, deductible amounts, and optional coverages like Uninsured Motorist protection.
- Solicit competitive quotes: Obtain detailed quotes from at least three distinct providers—combining national digital insurers like GEICO with local agents for State Farm or Southern Farm Bureau.
- Audit available discounts: Contact your chosen insurance representative to ensure all applicable safe-driver, multi-policy, occupational, and telematics discounts are added to your policy.
- Confirm policy continuity: Ensure your new insurance coverage takes effect before canceling your old policy to keep your vehicle fully covered and maintain your good standing with the Louisiana Office of Motor Vehicles.