AIG Direct, now operating primarily under the Corebridge Financial brand, remains a highly reputable and financially stable life insurance provider in 2026. It is particularly well-regarded for its flexible "Select-a-Term" policies and robust "living benefits" riders, making it an excellent choice for families seeking customizable coverage backed by top-tier financial strength ratings.
Determining whether a life insurance company is "good" requires looking beyond brand recognition and into the specifics of policy flexibility, claims-paying ability, and the modern underwriting experience. For many years, American International Group (AIG) was a household name in global finance. As of 2026, the transition of its life and retirement division into the independent entity known as Corebridge Financial is complete. While many consumers still search for "AIG Direct," they are interacting with Corebridge's digital distribution platform. This article evaluates the current standing of this entity, its product suite, and whether its offerings align with your financial goals.
The Evolution from AIG Direct to Corebridge Financial
To understand the current state of AIG Direct, one must understand the corporate restructuring that concluded in the mid-2020s. AIG strategically spun off its life insurance and retirement business to create Corebridge Financial. This move was designed to allow the life insurance segment to operate with greater focus and capital efficiency.
In 2026, Corebridge Financial stands as one of the largest providers of retirement solutions and life insurance in the United States. When you apply through the AIG Direct portal, you are essentially accessing Corebridge products. This transition has not diminished the company's historical strengths; rather, it has modernized the digital interface and streamlined the application process. For the consumer, this means the financial "backbone" of the policy remains robust, while the user experience has seen significant updates to meet 2026 standards for speed and transparency.
Analyzing Corebridge (AIG) Term Life Insurance Policies
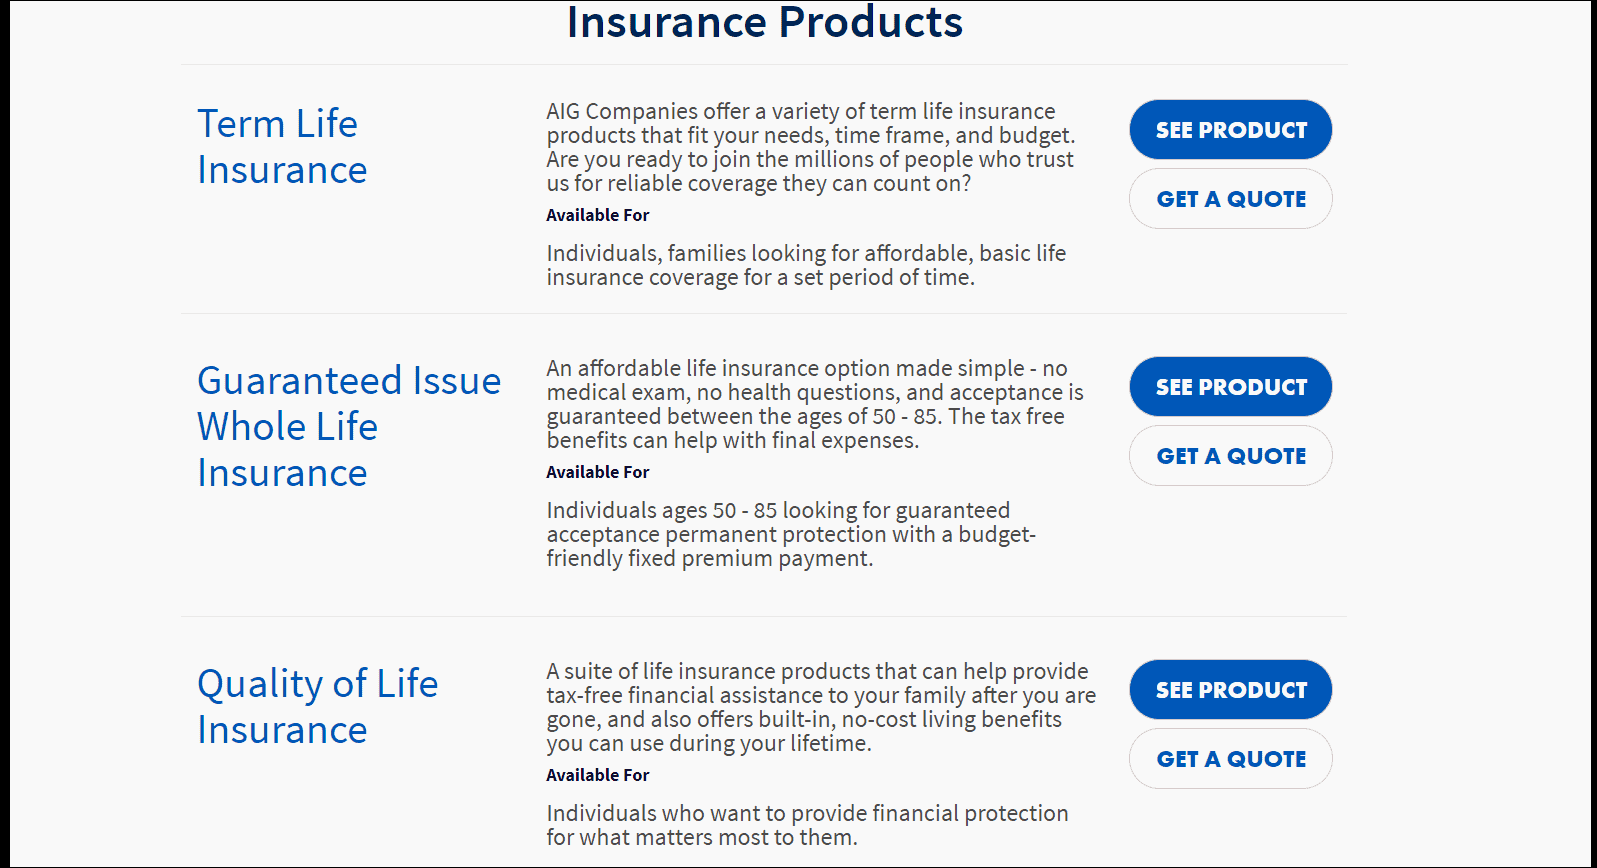
The flagship product of AIG Direct has long been its term life insurance, specifically the Select-a-Term offering. Unlike many competitors that only offer coverage in five or ten-year increments (e.g., 10, 15, 20, or 30 years), Corebridge allows for significantly more granularity.
Custom Term Lengths
In 2026, the ability to match your insurance term to a specific financial obligation is a major advantage. If you have 17 years left on a mortgage or 12 years until your youngest child graduates from university, Corebridge allows you to select a term of exactly 17 or 12 years. This prevents you from paying for unnecessary years of coverage or being left underinsured by a shorter standard term.
Renewable and Convertible Options
Most AIG Direct term policies include a conversion privilege. This is a critical feature for long-term financial planning. It allows policyholders to convert their term coverage into a permanent life insurance policy without undergoing a new medical exam. In 2026, as healthcare costs and longevity trends shift, the "guaranteed insurability" provided by a conversion rider is a high-value asset. If your health declines during your term, you can still secure lifelong coverage based on the health status you had when you first bought the policy.
Permanent Life Insurance and the Growth of IUL
Beyond term insurance, AIG Direct/Corebridge provides several permanent life insurance options. These are designed for individuals who need coverage that lasts their entire life and who may wish to use the policy as a wealth-accumulation tool.
Index Universal Life (IUL)
The Max Accumulator+ IUL is a popular choice in 2026 for those looking for a balance between death benefit protection and cash value growth. The cash value of an IUL policy is tied to the performance of a market index, such as the S&P 500. While the policy provides a "floor" (protecting against market losses), it also has a "cap" on gains. This makes it a strategic tool for tax-advantaged supplemental retirement income.
Guaranteed Universal Life (GUL)
For those who want the lifetime duration of a whole life policy but without the high premiums associated with rapid cash value growth, Corebridge offers Guaranteed Universal Life. This product is often referred to as "Term to age 100" (or 121). It is a "good" option if your primary goal is ensuring a death benefit is paid out regardless of when you pass away, provided premiums are met.
The "Quality of Life" Suite: Living Benefits Explained
One of the most compelling reasons AIG Direct is considered a "good" company in 2026 is its emphasis on living benefits. Historically, life insurance only paid out upon the death of the insured. Corebridge’s Quality of Life (QoL) suite changed this paradigm.
Living benefits allow the policyholder to accelerate a portion of the death benefit if they are diagnosed with a qualifying chronic, critical, or terminal illness. In 2026, with medical advancements extending life but often increasing the cost of long-term care, these riders are essential.
- Chronic Illness Rider: If you cannot perform two of the six "Activities of Daily Living" (ADLs), such as bathing or dressing, you can access funds to pay for care.
- Critical Illness Rider: This covers major events like heart attacks, strokes, or invasive cancer.
- Terminal Illness Rider: Provides access to the death benefit if a physician certifies a life expectancy of 12-24 months.
These are often "built-in" to the QoL policies, meaning the consumer does not always have to pay a separate, high premium for a stand-alone long-term care policy.
Financial Strength and Ratings
When you buy life insurance, you are buying a promise that may not be fulfilled for 30, 40, or 50 years. Therefore, the financial "health" of the insurer is the most critical metric. As of 2026, Corebridge Financial (the entity behind AIG Direct) maintains strong ratings from the major independent credit rating agencies.
| Agency | Rating (2026) | Significance |
|---|---|---|
| AM Best | A (Excellent) | Indicates an excellent ability to meet ongoing insurance obligations. |
| Standard & Poor's (S&P) | A+ (Strong) | Reflects very strong financial security characteristics. |
| Fitch Ratings | A+ (Strong) | Signifies low default risk and strong capacity for payment of financial commitments. |
| Moody’s | A2 (Good) | Suggests the company is upper-medium grade with low credit risk. |
These ratings confirm that despite the rebranding and spinoff, the capital reserves backing AIG Direct policies remain robust. For a consumer, this provides peace of mind that the company is highly unlikely to face insolvency.
Underwriting in 2026: The Agile Process
AIG Direct has heavily invested in "Agile Underwriting." In the past, getting life insurance required a "paramedical exam" involving blood draws and physical measurements. In 2026, Corebridge utilizes data-driven underwriting for many applicants.
By leveraging electronic health records (EHR), pharmacy databases, and motor vehicle records, the company can often approve "Preferred" or "Standard" risk classes without a medical exam. This is generally available for younger applicants (under age 50) and for coverage amounts up to $1 million or $2 million, depending on current 2026 guidelines. This reduces the approval time from weeks to potentially days or even hours.
Comparing AIG Direct with Industry Competitors
To determine if AIG Direct is the "best" fit, it is helpful to see how it stacks up against other major carriers in 2026.
| Feature | AIG Direct (Corebridge) | State Farm | Northwestern Mutual |
|---|---|---|---|
| Best For | Custom terms & living benefits | Customer service & bundling | Cash value/Dividends |
| Term Flexibility | High (any year 10-30) | Low (10, 20, 30) | Medium |
| Online Experience | Excellent (Direct portal) | Good | Moderate |
| Living Benefits | Comprehensive (QoL Suite) | Limited | Available via riders |
| Financial Strength | A (Excellent) | A++ (Superior) | A++ (Superior) |
While companies like State Farm or Northwestern Mutual might have slightly higher AM Best ratings (A++), AIG Direct often wins on price flexibility and the technical depth of their living benefit riders.
Potential Drawbacks and Considerations
No insurance company is perfect for every individual. While AIG Direct is a "good" company, there are specific scenarios where a different carrier might be preferable.
Customer Service Volume
Due to its massive size, AIG Direct/Corebridge handles millions of policies. According to data from the National Association of Insurance Commissioners (NAIC), large carriers sometimes face higher complaint indexes related to administrative delays or communication during the claims process. However, in 2026, Corebridge has implemented AI-driven customer service tools to mitigate these legacy issues.
Niche Health Issues
While Corebridge is competitive for "Standard" and "Preferred" risks, individuals with very specific high-risk medical conditions (such as certain rare autoimmune disorders) might find better rates through smaller, "niche" insurers like Prudential or Banner Life, which may have more aggressive underwriting tables for specific impairments.
Complexity of Products
The Quality of Life (QoL) suite and IUL products are technically complex. For a consumer who wants a "simple" policy without any "bells and whistles," the sheer volume of options at AIG Direct can be overwhelming. It is often beneficial to speak with a licensed agent who can explain the nuances of the accelerated death benefit triggers.
Who Should Choose AIG Direct in 2026?
AIG Direct is an ideal choice if you fall into one of the following categories:
- The "Gap" Filler: You need a specific number of years of coverage (e.g., 16 years until retirement) and don't want to overpay for a 20-year term.
- The Value-Oriented Family: You want life insurance that serves a dual purpose—providing a death benefit and acting as a "safety net" for chronic illness through living benefits.
- The Tech-Savvy Applicant: You prefer a digital-first application process with the possibility of skipping the medical exam.
- The Wealth Builder: You are interested in permanent insurance (IUL) that offers market-linked growth with a protective floor.
Professional Advice and Financial Planning
Life insurance is a foundational element of a comprehensive financial plan. While AIG Direct provides the tools to secure coverage, users should consult with a financial advisor or a licensed insurance professional to ensure their coverage amount ($500k vs. $1M) and policy type align with their broader estate planning and tax strategies. Note that insurance regulations vary by state, and certain riders, like the QoL accelerated benefits, may have different availability or triggers in states like New York or California.
Frequently Asked Questions
Is AIG Direct the same as Corebridge Financial?
Yes. As of 2026, Corebridge Financial is the independent public company that was formerly AIG Life & Retirement. AIG Direct is the consumer-facing brand/portal used to sell these Corebridge life insurance products directly to the public.
How long does it take to get approved by AIG Direct?
For many healthy applicants under age 50, "Agile Underwriting" can result in an approval within 24 to 72 hours. If a medical exam is required or if the medical history is complex, the process typically takes 3 to 6 weeks.
Can I cancel my AIG Direct policy if I change my mind?
Yes. Most policies come with a "Free Look Period" (usually 10 to 30 days, depending on your state). During this time, you can cancel the policy for any reason and receive a full refund of any premiums paid.
Do AIG Direct policies pay out for suicide?
Like almost all U.S. life insurance policies in 2026, there is a standard two-year "Suicide Clause." If the insured passes away by suicide within the first two years of the policy, the company will typically only refund the premiums paid. After two years, the full death benefit is generally covered.
What happens to my AIG Direct term policy when the term ends?
When the term expires, you usually have three options: let the coverage lapse, renew it annually (at a significantly higher "attained age" rate), or convert it to a permanent policy if your contract includes a conversion rider.
Summary of Actionable Next Steps
If you are considering AIG Direct, start by utilizing their online quote tool to compare different "Select-a-Term" lengths. This will give you a baseline for cost. Before signing, ask for a "Summary of Benefits" specifically regarding the Quality of Life riders to ensure you understand how much of your death benefit can be accessed early if you become ill. Given the strong financial ratings of Corebridge in 2026, you can move forward with confidence regarding the company's ability to honor its long-term commitments.