Insurance agents selling flexible premium variable universal life (FPVUL) insurance must fulfill rigorous licensing, disclosure, and suitability duties. Because FPVUL is classified as both an insurance product and a security, agents must hold a valid life insurance license and FINRA registration, provide a current prospectus, and ensure the policy aligns with the client's risk tolerance and long-term financial objectives.
Flexible premium variable universal life (FPVUL) insurance represents one of the most complex financial instruments available to the public in 2026. It combines the death benefit protection of traditional life insurance with the investment potential of a securities portfolio, all while offering the policyholder the ability to adjust premium payments. Due to this complexity, the duties of the agent (or registered representative) extend far beyond those required for term or whole life policies. The agent acts as a bridge between the insurance carrier’s actuarial requirements and the client’s investment goals, bearing a significant burden of regulatory and ethical responsibility.
The Dual Nature of FPVUL: Regulatory Oversight in 2026
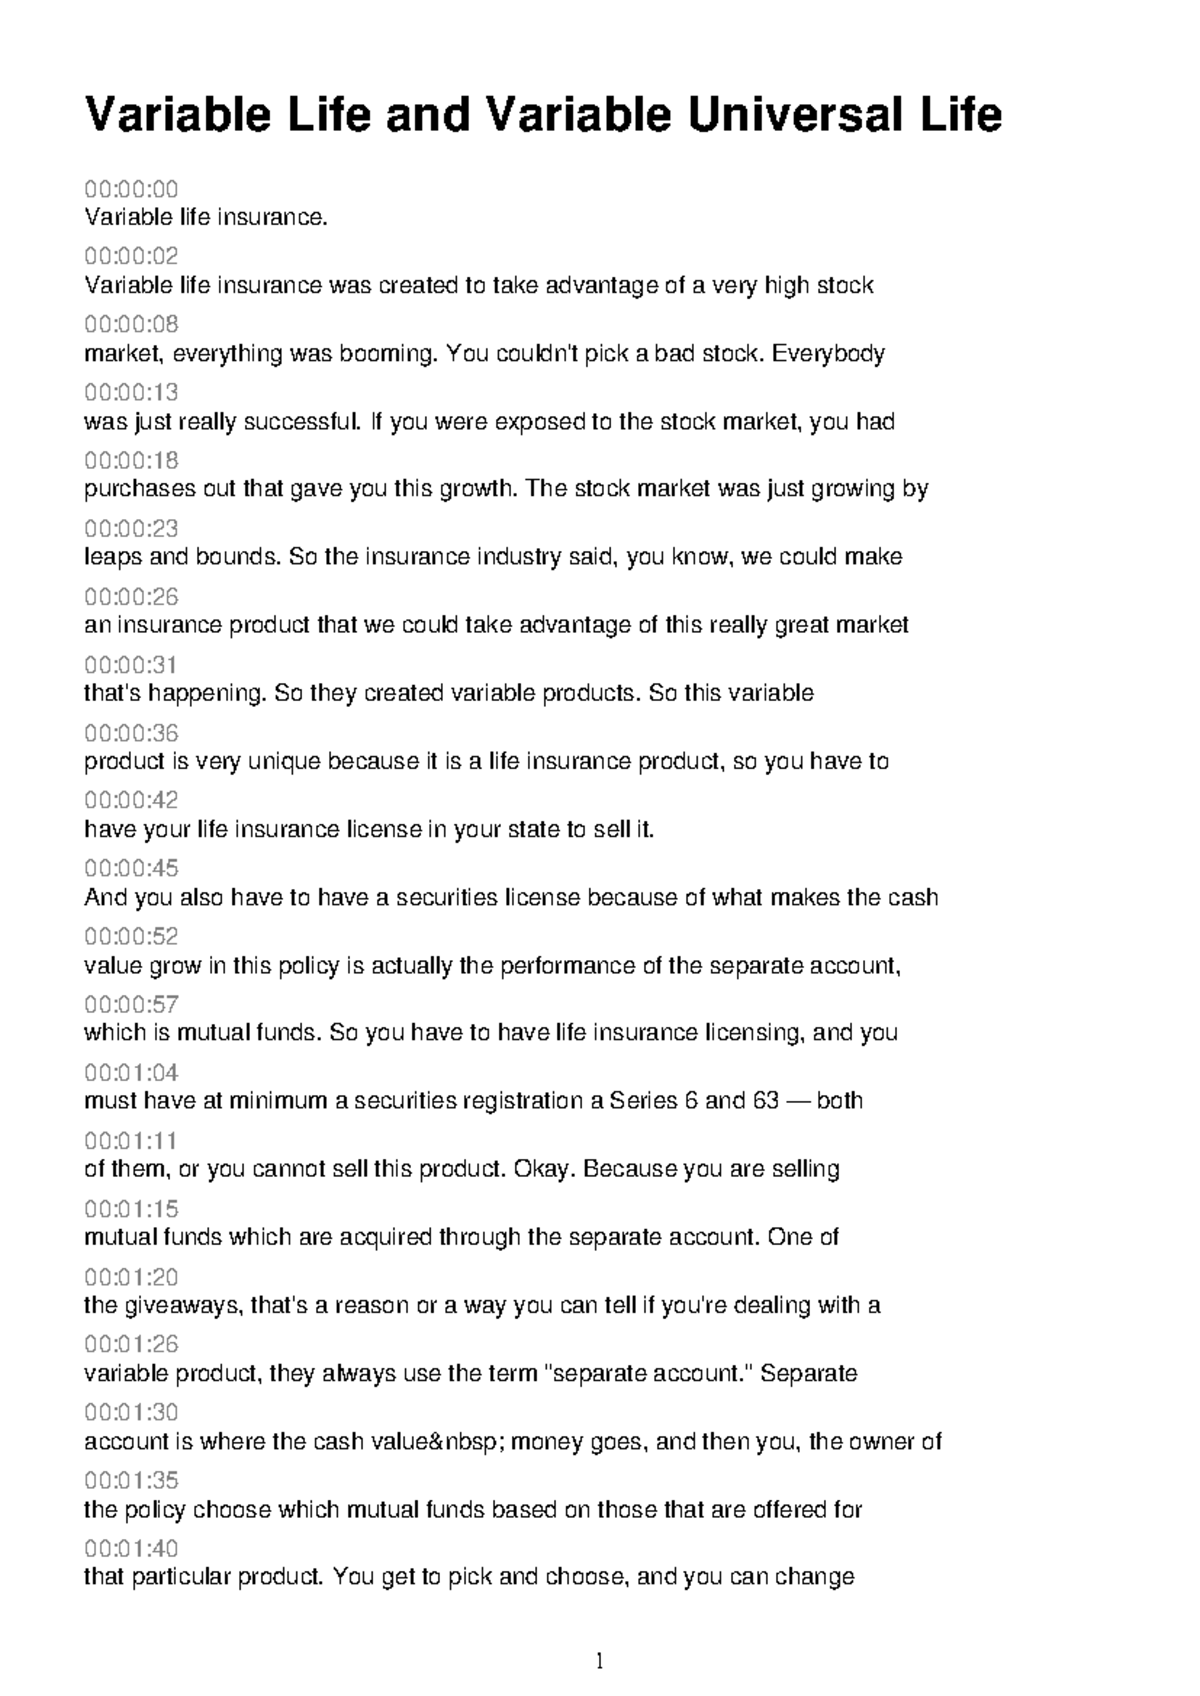
To understand an agent's duties, one must first recognize that FPVUL is a "hybrid" product. Under federal law, the sub-accounts into which premiums are invested are considered securities. Consequently, the sale of these policies is governed by both state insurance departments and federal entities like the Securities and Exchange Commission (SEC) and the Financial Industry Regulatory Authority (FINRA).
As of 2026, the standard of care for these transactions remains centered on Regulation Best Interest (Reg BI). This means that agents cannot simply recommend a policy because it offers a high commission; they must prove that the FPVUL policy is in the client’s best interest based on their financial profile. The duty of the agent starts with ensuring they have the legal authority to even discuss the product, which requires a Life Insurance license and usually a FINRA Series 6 or Series 7 registration.
Pre-Sale Duties: Suitability and the Best Interest Standard
The most critical duty an agent performs occurs before the policy is even issued: the suitability analysis. Because FPVUL policies involve market risk—meaning the cash value can decrease if the underlying investments perform poorly—the agent must conduct a thorough "Know Your Customer" (KYC) assessment.
Assessing Risk Tolerance and Financial Capacity
An agent must document the client’s investment experience, time horizon, liquidity needs, and risk tolerance. For many clients, a variable product is inappropriate. If a client is nearing retirement and cannot afford a loss of principal, recommending an FPVUL policy may be a breach of duty. The agent must ensure the client understands that while there is a "floor" for the death benefit in some configurations, the cash value is not guaranteed.
Determining the Purpose of the Policy
Agents must clarify whether the client is seeking death benefit protection, tax-advantaged wealth accumulation, or a supplement to retirement income. Because the "flexible premium" aspect allows clients to underfund or overfund the policy, the agent must explain the consequences of these choices. Overfunding can turn the policy into a Modified Endowment Contract (MEC), which changes the tax treatment of loans and withdrawals—a vital disclosure duty for the agent.
The Duty of Disclosure: The Prospectus and Beyond
In the sale of any variable product, the delivery of the prospectus is a non-negotiable legal requirement. The agent is duty-bound to provide the most current version of the prospectus, which outlines the investment objectives of the sub-accounts, the risks involved, and the internal costs of the policy.
Explaining Internal Costs and Fees
One common area of litigation involves the misunderstanding of "Cost of Insurance" (COI). As the insured ages, the COI within a universal life policy increases. In an FPVUL policy, if the sub-accounts are underperforming while the COI is rising, the policy can rapidly deplete its cash value. The agent has a proactive duty to explain:
- Mortality and Expense (M&E) Risks: Fees charged by the insurer to cover the risks they assume.
- Administration Fees: Costs for maintaining the policy and sub-accounts.
- Surrender Charges: Significant penalties for withdrawing funds or canceling the policy in the early years.
- Investment Management Fees: Fees associated with the specific mutual fund-like sub-accounts chosen.
Illustrating Policy Performance
Agents use "illustrations" to show how the policy might perform over decades. A key duty here is to use realistic growth rates. Presenting an illustration that only shows 10% annual growth without showing a 0% or negative growth scenario is often considered a violation of industry standards. In 2026, many regulators require agents to provide a "range of outcomes" to ensure the client understands the volatility inherent in the variable component.
Managing the "Flexible Premium" Aspect
The "Flexible Premium" feature is both a selling point and a point of failure for many policies. Agents have a duty to explain that "flexible" does not mean "optional" in a way that ignores the policy's health.
The Risk of Lapse
If a client decides to stop paying premiums because the policy is "flexible," the policy relies entirely on the existing cash value to pay the monthly COI and administrative fees. If the market crashes simultaneously, the cash value could drop to zero, causing the policy to lapse. The agent’s duty is to monitor these policies and warn clients when a lapse is imminent. This is often referred to as a "rescue" duty, where the agent advises the client to increase premiums to keep the death benefit in force.
Guidance on Premium Allocation
While agents who are not licensed investment advisors cannot provide specific "buy/sell" advice for individual stocks, as registered representatives, they must help the client allocate premiums among the available sub-accounts in a way that matches the stated risk profile. This includes explaining the difference between equity funds, bond funds, and the "fixed account" (which offers a guaranteed minimum interest rate).
Administrative and Compliance Duties
Beyond the client-facing roles, the agent has several administrative duties to the insurance carrier and regulatory bodies.
- Anti-Money Laundering (AML) Compliance: Agents are the first line of defense against money laundering. They must report suspicious activity, such as large cash-equivalent premium payments or rapid surrenders of high-value policies.
- Accuracy in Underwriting: The agent must ensure that all health and lifestyle information provided by the applicant is accurate. Misrepresentation can lead to a denial of the death benefit claim during the two-year contestability period.
- Record Keeping: Under SEC and FINRA rules, agents must maintain records of all communications, signed disclosures, and illustrations used during the sale for several years.
Ongoing Servicing: The Post-Sale Responsibility
The duty of an agent does not end when the policy is delivered. FPVUL policies require ongoing maintenance. As of 2026, the industry standard has shifted toward "active servicing."
Periodic Reviews
Agents should conduct annual or biennial reviews with the policyholder. During these reviews, the agent checks the policy’s performance against the original projections. If the sub-accounts have underperformed, the agent must discuss whether the client needs to increase their premium payments to meet their long-term goals.
Handling Policy Loans and Withdrawals
FPVUL policies allow clients to take loans against the cash value. The agent’s duty is to explain that these loans accrue interest and reduce the death benefit. Furthermore, if the policy lapses while a loan is outstanding, it can trigger a massive taxable event for the client. The agent must warn the client of these "tax traps" before a loan is processed.
Comparison of Agent Responsibilities Across Life Insurance Types
The following table highlights how the duties for an FPVUL agent differ from those selling other common life insurance products.
| Feature/Duty | Term Life Insurance | Fixed Universal Life | Variable Universal Life (FPVUL) |
|---|---|---|---|
| Licensing Required | State Life License | State Life License | Life License + FINRA Series 6/7 |
| Suitability Focus | Death benefit need | Interest rate sensitivity | Market risk & investment goals |
| Mandatory Disclosure | Policy terms | Crediting rates/fees | Full Prospectus delivery |
| Premium Guidance | Fixed payments | Minimum to stay in force | Solvency monitoring vs. volatility |
| Primary Regulatory Body | State Dept. of Insurance | State Dept. of Insurance | SEC, FINRA, and State Dept. |
| Service Frequency | Low (at renewal) | Moderate (rate changes) | High (market/premium reviews) |
Common Mistakes and Breach of Duty
Failure to perform these duties can result in severe consequences for the agent, including the loss of their license, FINRA fines, and Errors and Omissions (E&O) insurance claims. Common breaches include:
- Churning: Encouraging a client to replace an existing FPVUL policy with a new one solely to generate a new commission, without a demonstrable benefit to the client.
- Inadequate Diversification: Recommending that a client put 100% of their premium into a single high-risk sub-account when their profile suggests a moderate risk tolerance.
- Guaranteed Projections: Implying that the "variable" portion of the policy is guaranteed or "cannot lose money."
- Failure to Explain the "Net Amount at Risk": Not explaining that the COI is charged based on the difference between the death benefit and the cash value, which can fluctuate wildly.
Frequently Asked Questions (FAQs)
1. Does an agent need a special license to sell FPVUL?
Yes. Because FPVUL involves sub-accounts that are considered securities, an agent must have a state life insurance license and be a registered representative of a broker-dealer. This usually requires passing the FINRA Series 6 or Series 7 exam, along with the Securities Industry Essentials (SIE) exam.
2. Is the agent responsible if my investment sub-accounts lose money?
Generally, no, as long as the agent performed their "Best Interest" duty. If the agent properly disclosed the risks, provided the prospectus, and ensured the investment was suitable for your risk tolerance, they are not liable for market losses. However, if they promised "guaranteed" returns or ignored your low-risk profile, they may be liable for a suitability breach.
3. What is the agent’s duty regarding the "Flexible Premium" feature?
The agent must explain that while you have the flexibility to pay more or less than the planned premium, the "cost of insurance" is still being deducted every month. They have a duty to warn you that underpaying premiums, especially during a market downturn, could cause the policy to lapse.
4. Why did my agent give me a thick booklet (prospectus) before I signed?
Providing the prospectus is a legal requirement. It contains all the essential technical information about the policy’s fees, risks, and investment options. Agents are required by the SEC to ensure you have access to this document before or at the time of the sale to make an informed decision.
5. Can an agent help me change my investment sub-accounts?
Yes, an agent can facilitate the paperwork or electronic transfers to reallocate your cash value among the available sub-accounts. However, unless they are also a licensed Investment Adviser Representative (IAR), they may be limited in the specific "advice" they can give regarding market timing or specific fund picking.
6. What happens if my agent stops servicing my policy?
If an agent leaves the industry or ignores your policy, the responsibility for oversight often falls to the "Agent of Record" assigned by the insurance company or broker-dealer. You have the right to request a new agent if your current one is not fulfilling their duty to provide periodic reviews and solvency updates.
Practical Recommendation for Policyholders
If you are considering or currently own a flexible premium variable universal life insurance policy in 2026, your most important action is to demand a "policy stress test." Ask your agent to provide an illustration showing how the policy would perform if the market returns 0% for the next five years while you pay only the minimum premium. This will reveal the true "net amount at risk" and help you understand the agent's primary duty: keeping your policy solvent while you pursue investment growth. Ensure you receive a written summary of the annual fees and confirm that your agent is currently registered with FINRA to verify their standing and any past disciplinary history.