Finding affordable life insurance in Scottsdale, Arizona, requires balancing your specific coverage needs with a realistic assessment of your financial profile and health history. By leveraging local competitive markets, understanding how the Arizona Department of Insurance and Financial Institutions regulates carriers, and applying strategic shopping methods, residents can obtain necessary protection while minimizing premium costs.
The landscape of life insurance in Scottsdale is influenced by both national actuarial trends and state-specific regulations. Because Arizona does not impose a state-level tax on life insurance premiums, costs are primarily dictated by the insurer’s risk assessment, the type of policy selected, and your personal medical underwriting. To secure the most favorable rates, you must navigate the distinction between term life, which provides cost-effective coverage for a set duration, and permanent life, which serves as a long-term financial asset.
Understanding the Regulatory Environment in Arizona
When shopping for life insurance in Scottsdale, it is vital to understand that your policy is governed by Arizona state law and overseen by the Arizona Department of Insurance and Financial Institutions (DIFI). The DIFI serves as a critical resource for verifying that a life insurance company is licensed to conduct business within the state.
Selecting a state-authorized insurer is the first step in ensuring your policy is backed by the state’s guaranty association protections. In the unlikely event that your insurance carrier becomes insolvent, the Arizona Life and Disability Insurance Guaranty Fund provides a safety net, protecting policyholders up to certain statutory limits. Always verify the license status of a potential agent or insurance carrier through the official DIFI database before committing to an application. This verification ensures that you are dealing with a legitimate entity that adheres to Arizona’s consumer protection standards.
Determining Your Specific Coverage Needs
Before scouting for "affordable" rates, you must define what "affordable" means in the context of your family’s financial stability. The primary purpose of life insurance is to replace income, cover debt obligations, and ensure that funeral or final expenses do not become a burden on your survivors.
The Role of Income Replacement
A common rule of thumb is to purchase coverage that is 7 to 10 times your annual income. However, in a market like Scottsdale, where cost-of-living metrics fluctuate, you should factor in local variables. If you are paying off a mortgage in an area with rising property values, your insurance payout must be sufficient to clear that debt or provide an equivalent income stream for your beneficiaries to maintain their current standard of living.
Debt and Liability Assessment
Make a comprehensive list of your liabilities:
- Outstanding Mortgage: Is the goal to pay off the home entirely?
- Education Costs: Do you have children who will require college tuition funding?
- Personal Debt: Include credit cards, auto loans, and any personal lines of credit.
- Final Expenses: Scottsdale funeral and burial costs can be significant; ensure your policy covers these final costs to spare your family immediate financial strain.
Term Life vs. Permanent Life: The Cost Perspective
The most significant factor in the cost of your insurance is the policy type. For the vast majority of individuals seeking affordability, term life insurance is the primary recommendation.
Term Life Insurance
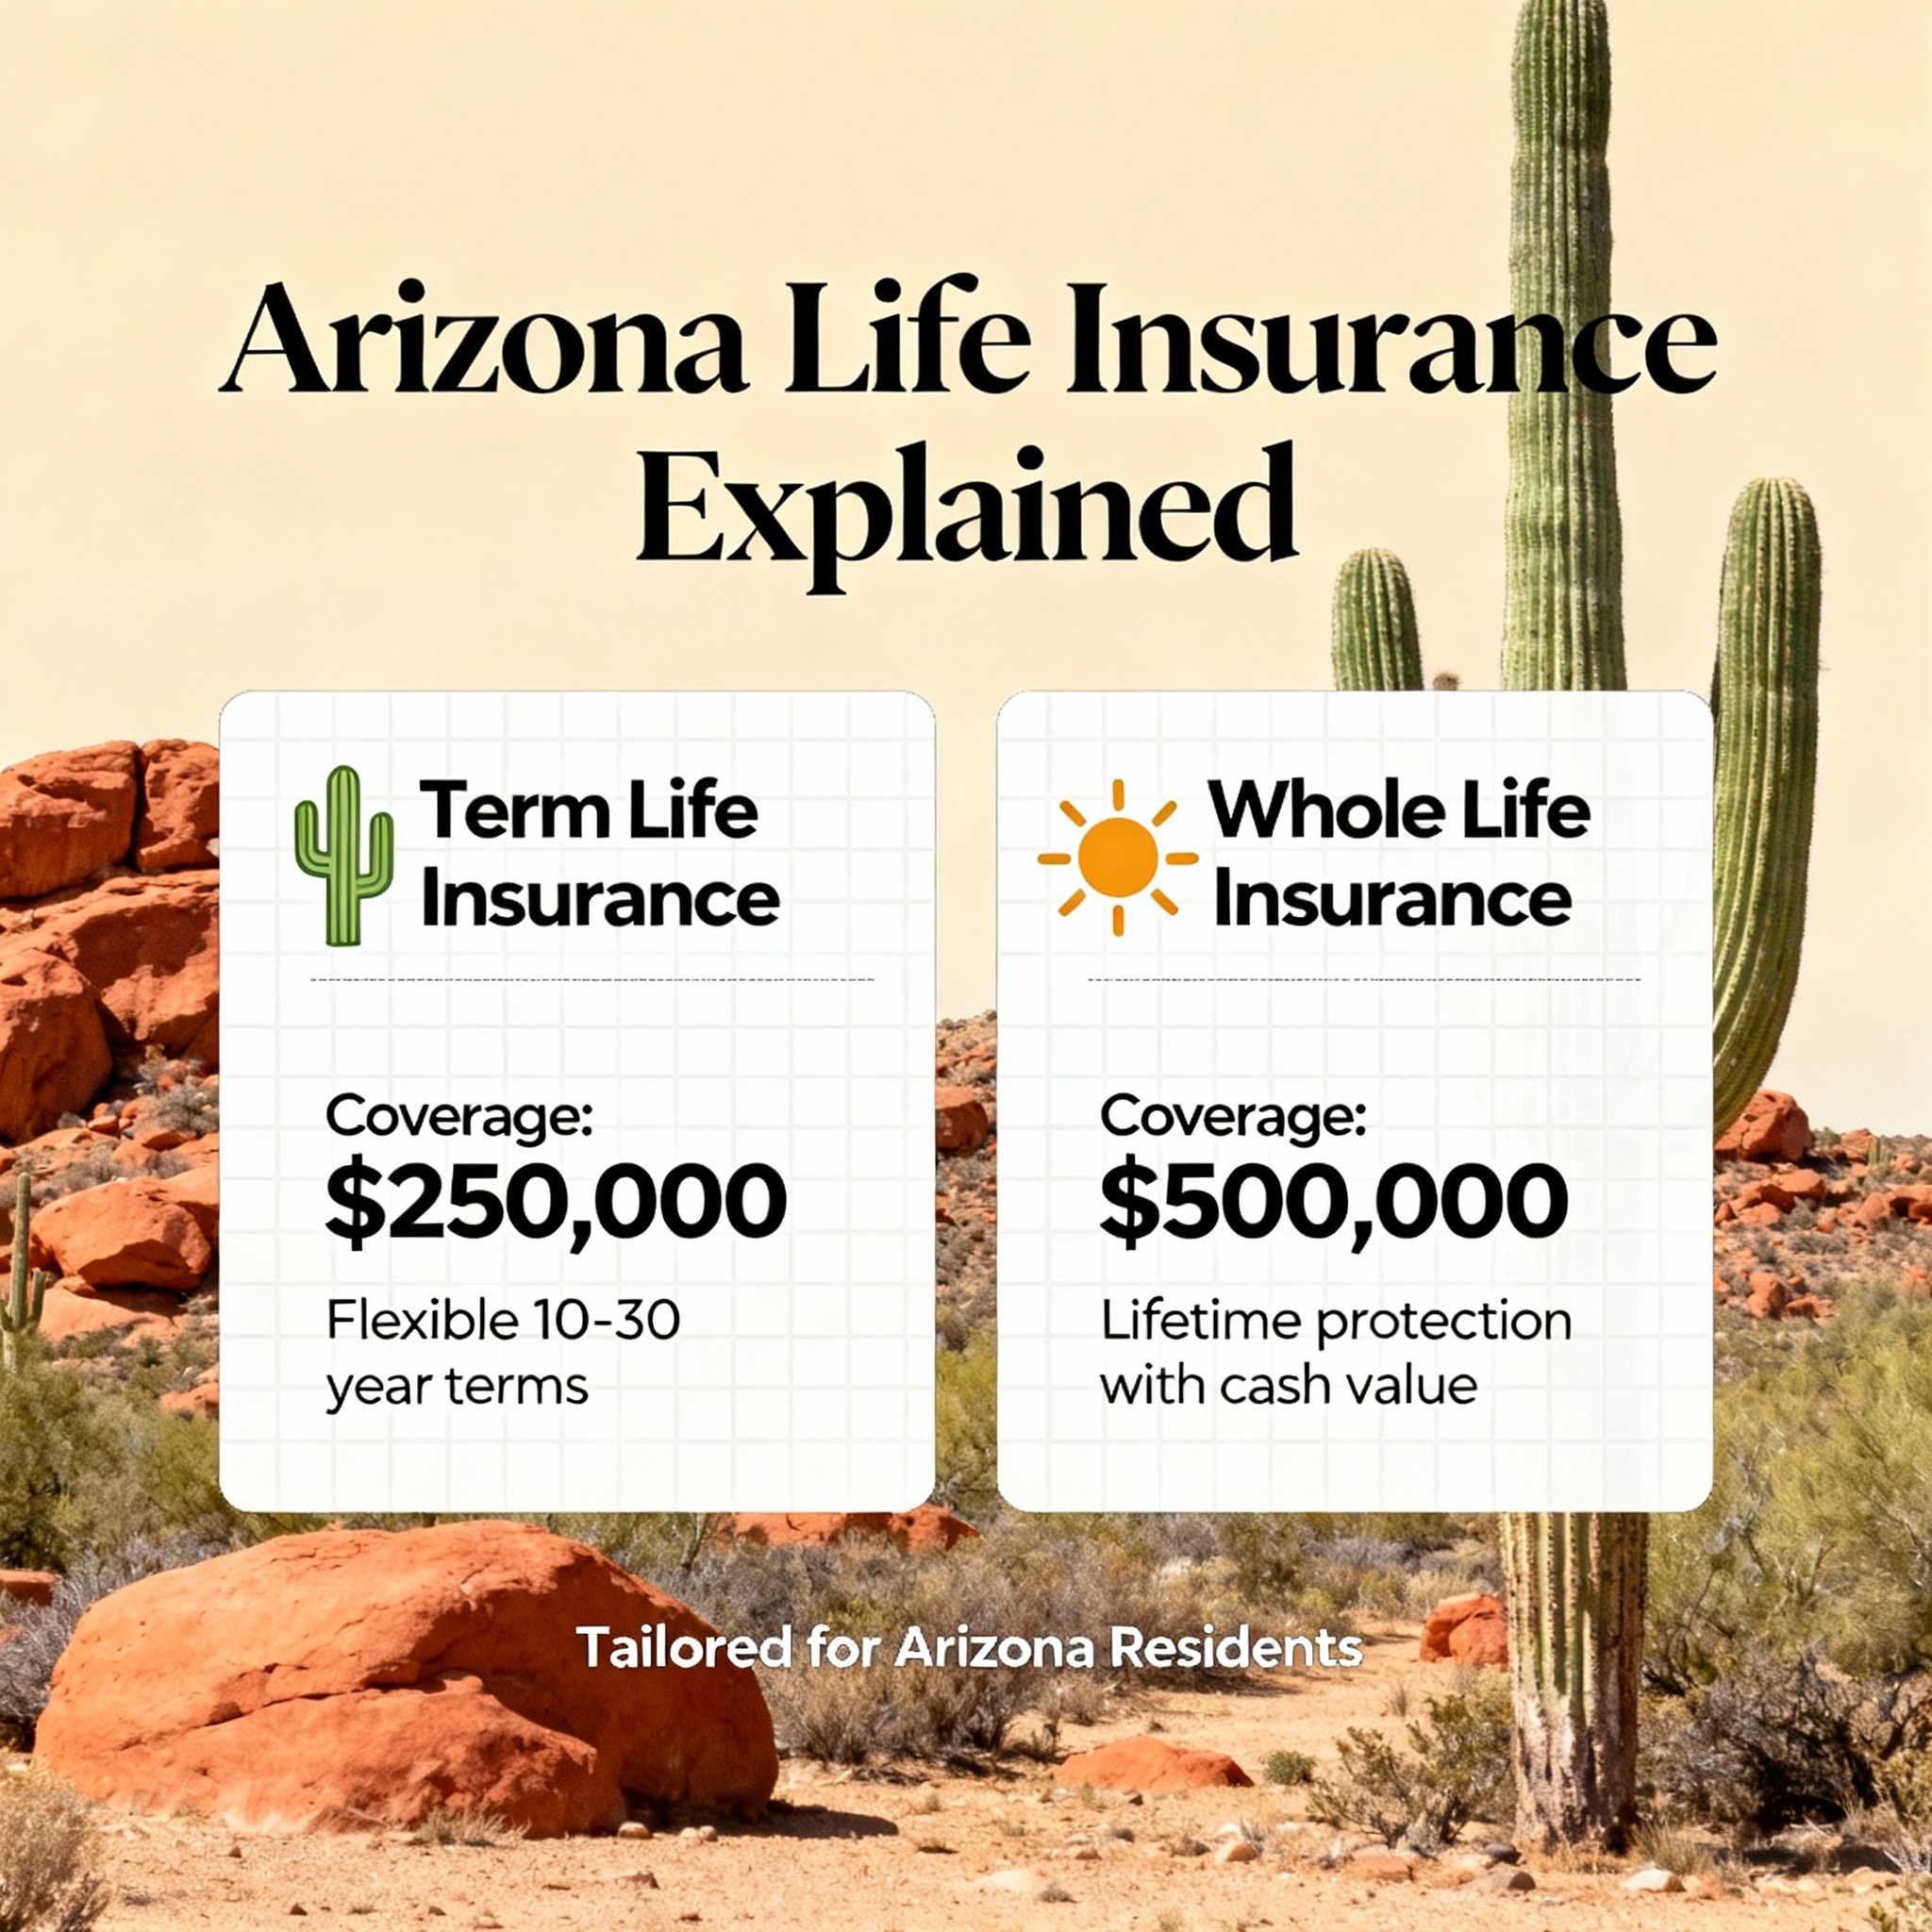
Term life provides coverage for a specific period—typically 10, 20, or 30 years. It is a "pure" insurance product because it does not include an investment or cash-value component. Because it only pays out if you pass away during the term, the premiums are significantly lower than permanent policies. For a healthy 35-year-old in Scottsdale, a 20-year term policy is often the most economical way to secure high death-benefit coverage for the years when financial responsibilities, such as mortgage payments and child-rearing, are at their peak.
Permanent Life Insurance
Permanent insurance, such as Whole Life or Universal Life, provides coverage for your entire life, provided premiums are paid. These policies include a cash-value account that grows over time. While these can be powerful estate planning tools, they are not typically the solution for those prioritizing "affordability" in their monthly budget, as the premiums are substantially higher due to the lifelong guarantee and the investment component.
Factors Influencing Your Premium in Scottsdale
Insurance carriers utilize actuarial data to determine your "risk class." Even within the same zip code in Scottsdale, two individuals can receive vastly different quotes based on these specific underwriting criteria:
- Age: The younger you are when you apply, the lower your premium. Applying for a policy today is almost always cheaper than waiting until next year.
- Health Status: Insurers look at your BMI, blood pressure, cholesterol levels, and medical history. Chronic conditions like diabetes or heart disease will increase your rate, but they do not make coverage impossible.
- Tobacco Usage: This is perhaps the most significant controllable factor. Smokers typically pay 200% to 300% more for life insurance than non-smokers.
- Lifestyle and Hobbies: Engaging in high-risk activities such as private aviation, scuba diving, or extreme sports can result in a "substandard" rating, which increases your premium.
- Family History: Insurers may inquire about the health history of immediate family members, particularly regarding premature death or hereditary conditions.
Comparative Analysis of Policy Features
To assist in your decision-making, the following table outlines the trade-offs between the two most common policy structures:
| Feature | Term Life Insurance | Permanent (Whole) Life |
|---|---|---|
| Duration | Specific term (e.g., 20 years) | Lifetime (if premiums paid) |
| Cost | Low (Most affordable) | High |
| Cash Value | None | Yes (Builds over time) |
| Premium | Level/Fixed for the term | Level for life |
| Primary Intent | Income replacement | Estate planning/Long-term savings |
The Application Process: Step-by-Step
Securing a policy in Scottsdale involves a standardized process designed to evaluate your risk level accurately.
- Selection of Coverage Amount: Calculate your financial needs based on the debt and income replacement analysis mentioned earlier.
- Choosing an Independent Agent: Unlike "captive" agents who only sell for one company, independent agents in Arizona can compare quotes from multiple carriers. This is the single most effective way to find the most affordable price for your specific profile.
- Medical Underwriting: You will likely need to complete a paramedical exam. A technician will come to your home or office in Scottsdale to measure your height, weight, and blood pressure, and take a blood/urine sample.
- Review and Approval: The carrier’s underwriters review your application, medical records, and exam results. This process can take anywhere from a few days to several weeks.
- Policy Issuance: Once approved, you review the contract, sign the necessary documents, and make your first premium payment to activate the policy.
Avoiding Common Pitfalls
Many Scottsdale residents inadvertently pay too much for life insurance by falling into these common traps:
- Buying Based on Brand Name Alone: While brand recognition is comforting, the "best" company is the one that offers the lowest rate for your specific risk profile. Use an agent who can access multiple carriers.
- Non-Disclosure: Always be honest on your application. If you fail to disclose a medical condition or smoking history, the insurer can deny a claim or void the policy entirely, leaving your beneficiaries with nothing.
- Over-insuring: While you need adequate coverage, ensure you are not paying for benefits you do not need. Reassess your coverage every few years to match your actual financial situation.
- Waiting Too Long: Do not wait for a health scare to buy insurance. The best time to apply is when you are healthy and younger.
Frequently Asked Questions
Is it cheaper to buy life insurance through my employer?
Group life insurance offered by employers is often convenient and sometimes provided at little to no cost. However, it is rarely sufficient. Most employer plans offer coverage equal to one or two years of your salary, which often fails to meet long-term family needs. Additionally, group insurance is rarely portable; if you leave your job, you lose your coverage. Use employer-sponsored plans as a supplement, not a replacement for an individual policy.
Can I get life insurance in Scottsdale if I have a pre-existing condition?
Yes. Many insurance companies specialize in "high-risk" or "impaired-risk" underwriting. While your premiums will be higher than those of a perfectly healthy applicant, insurers use specialized charts to rate your specific condition. Never assume you are uninsurable without first speaking to a broker who has experience with high-risk applications.
What is a "no medical exam" policy?
"No-exam" policies are growing in popularity due to their speed. While they are convenient, they are often more expensive for the same amount of coverage compared to traditional policies that require an exam. They are best suited for individuals who need coverage immediately or those who may have minor health concerns they wish to avoid disclosing through a full medical workup.
How often should I re-evaluate my life insurance needs?
You should conduct a review every time you experience a "major life event." This includes marriage, the birth of a child, purchasing a home, starting a new business, or a significant change in income. These milestones inherently change the amount of capital your family would need to maintain their standard of living.
Are there local tax implications for life insurance payouts in Arizona?
Generally, life insurance death benefits are income-tax-free for beneficiaries under federal law. Arizona does not have a state-level inheritance or death tax that would apply to life insurance proceeds. However, if the policy is held within an estate that exceeds federal tax exemptions, there may be estate tax implications. Consult with a financial advisor or tax professional regarding your specific estate planning needs.
Recommended Next Steps
To move forward with finding the most affordable coverage, take these three actions immediately:
- Calculate your "Number": Determine exactly how much coverage you need to protect your family’s current lifestyle.
- Consult an Independent Broker: Reach out to a licensed insurance broker in Scottsdale who represents multiple A-rated carriers. Ask them to run a "market survey" based on your age and basic health profile to compare quotes from five or more top-tier companies.
- Review the Fine Print: Before signing, ensure you understand the "grace period" for late payments and the "contestability period," which is the timeframe (usually two years) during which the insurance company can investigate the accuracy of your application.
By taking a systematic, informed approach, you can secure robust financial protection for your loved ones at a price that fits your budget, providing peace of mind in an uncertain future.