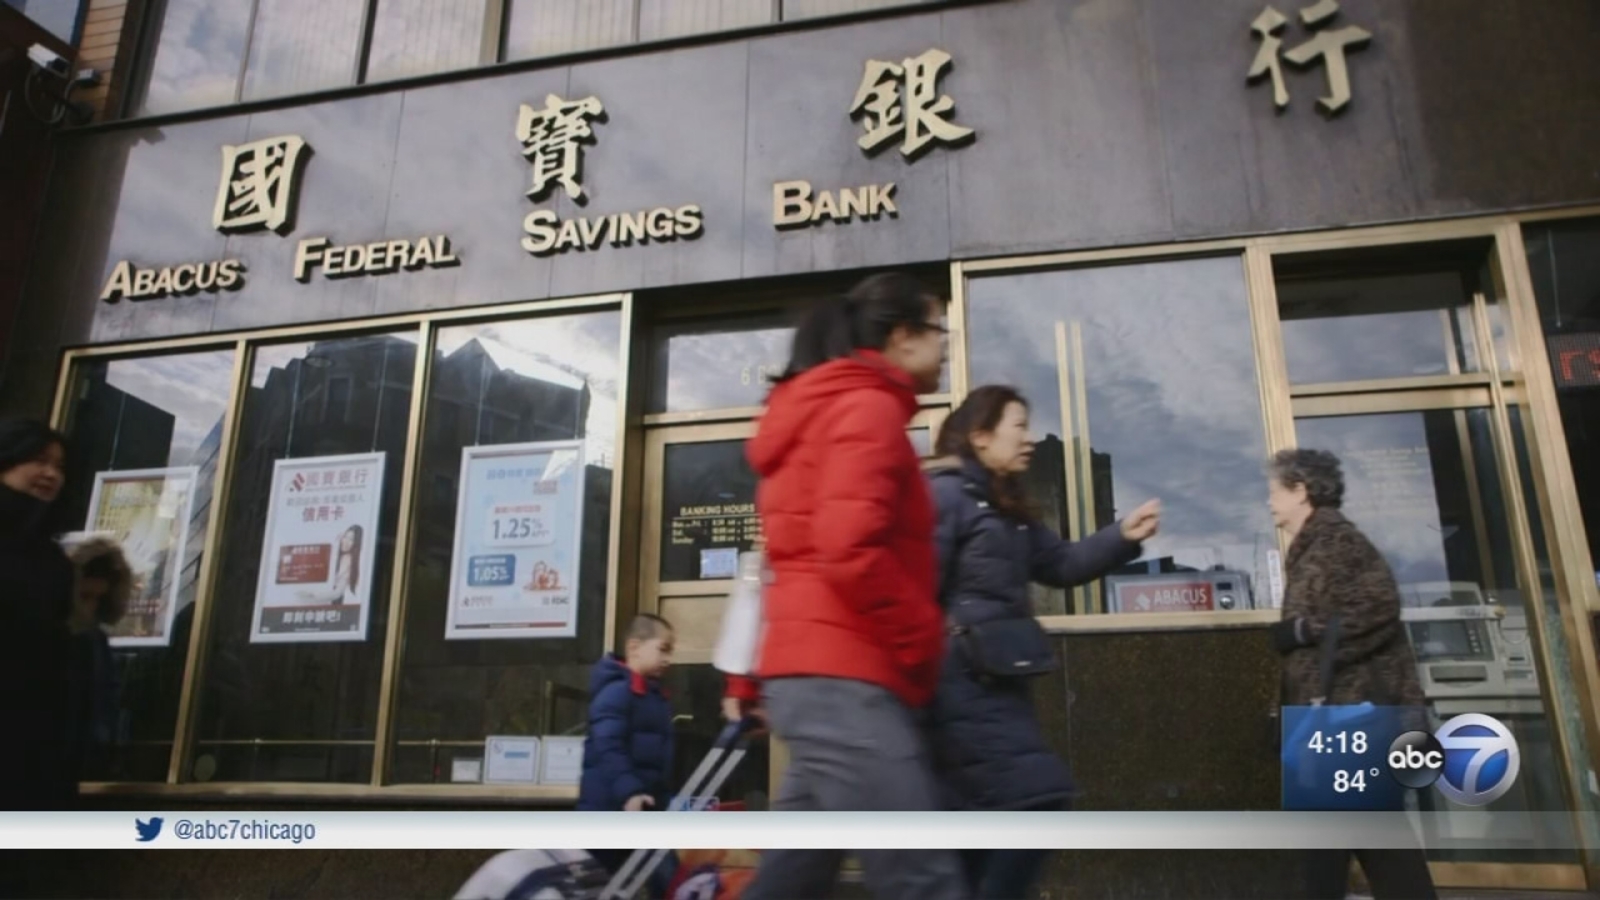
Abacus Federal Savings Bank is a community-oriented financial institution headquartered in New York City, recognized for its specialized focus on serving the immigrant community, particularly the Chinese-American population. Operating primarily within the New York metropolitan area, the bank provides a range of retail banking products, including residential and commercial mortgages, personal checking and savings accounts, and small business banking services tailored to local needs.
The Role of Community Banking in New York
Abacus Federal Savings Bank occupies a unique niche in the competitive New York financial landscape. Unlike global investment banks or massive retail chains that prioritize broad, digitized interactions, Abacus focuses on high-touch, relationship-based banking. For many residents of New York’s diverse neighborhoods—particularly in Lower Manhattan, Brooklyn, and Queens—the bank serves as a critical bridge between immigrant experiences and the established American financial system.
The institution’s mission is centered on providing accessibility to credit and deposit services for individuals who may have been underserved by larger national institutions due to language barriers or unconventional credit histories. By maintaining physical branch locations in heart-of-the-community neighborhoods, the bank prioritizes in-person interaction, which allows loan officers to assess the creditworthiness of borrowers through more holistic methods than automated algorithms might permit.
Core Banking Services and Products
As of 2026, Abacus Federal Savings Bank maintains its commitment to traditional banking principles. Their service catalog is designed to assist both individual consumers and local small business owners.
Personal Banking Solutions
For individual residents, the bank offers foundational financial tools. These include:
- Checking Accounts: Basic transaction accounts designed for payroll deposits and everyday expenses.
- Savings and Money Market Accounts: Interest-bearing vehicles intended for emergency funds or short-term wealth preservation.
- Certificates of Deposit (CDs): Time-deposit accounts that offer fixed interest rates over specific terms, providing a predictable return for conservative savers.
Residential and Commercial Lending
The bank’s primary lending activity revolves around real estate. In New York, where property values and market complexities are high, Abacus distinguishes itself by focusing on:
- Residential Mortgages: Assistance for first-time homebuyers and existing property owners looking to refinance. The bank’s underwriters are familiar with the unique documentation often associated with income streams from multi-generational or immigrant households.
- Commercial Real Estate Lending: Providing capital to local small businesses—such as restaurants, retail shops, and professional services—to acquire or renovate physical locations.
Operational Philosophy and Regulatory Oversight
Like all federally chartered savings banks in the United States, Abacus operates under the regulatory supervision of the Office of the Comptroller of the Currency (OCC) and the Federal Deposit Insurance Corporation (FDIC). This ensures that customer deposits are protected up to the standard legal limits, currently $250,000 per depositor, per insured bank, for each account ownership category.
The bank’s internal processes are built around the "Know Your Customer" (KYC) protocols required by federal law. While these protocols are standardized, the bank’s execution often involves a linguistic and cultural component that simplifies the compliance process for non-native English speakers. By providing bilingual staff and documentation, the bank effectively reduces the friction that typically prevents immigrant populations from accessing regulated banking services.
Comparison of Banking Models in New York
The following table summarizes the differences between Abacus and the broader financial services environment in New York.
| Feature | Abacus Federal Savings Bank | Large National Retail Banks |
|---|---|---|
| Primary Focus | Community-based, Relationship-driven | Mass-market, Volume-driven |
| Branch Strategy | Targeted in specific cultural hubs | Ubiquitous across all districts |
| Loan Approval | Human-centric, qualitative assessment | Automated, algorithm-based |
| Language Support | Extensive (Mandarin/Cantonese) | Limited/Digital-only in many cases |
| Tech Integration | Basic, essential digital services | Advanced, high-tech fintech suites |
Addressing the Needs of Small Business Owners
Small businesses are the economic engine of New York City, and Abacus provides tailored support for these enterprises. Business owners in New York often face challenges related to high commercial rents and the necessity of rapid capital deployment for inventory or renovations. The bank offers business checking accounts and commercial credit lines that are designed to be accessible to local entrepreneurs.
The bank’s approach to small business lending is often characterized by a longer-term perspective. By understanding the specific challenges faced by businesses in areas like Chinatown or Sunset Park, the bank’s loan officers can provide guidance that aligns with the realities of the local retail environment, rather than forcing businesses into rigid, one-size-fits-all loan products.
Prerequisites for Opening an Account
To open a standard deposit account at Abacus Federal Savings Bank, prospective customers should be prepared to provide documentation consistent with federal anti-money laundering (AML) and USA PATRIOT Act requirements. This typically includes:
- Government-Issued Identification: A valid driver’s license, state-issued ID, or passport.
- Taxpayer Identification: A Social Security Number (SSN) or an Individual Taxpayer Identification Number (ITIN).
- Proof of Address: A utility bill, lease agreement, or bank statement showing a current New York metropolitan area address.
- Initial Deposit: Minimum balance requirements vary by account type; customers should inquire at their local branch regarding the current minimums for 2026.
It is highly recommended that new customers visit a branch in person. This not only facilitates the identity verification process but also allows for a face-to-face discussion about which account features—such as online banking access or debit card options—best fit their financial habits.
Challenges and Considerations
While Abacus provides essential services, customers should be aware of the inherent limitations of a community-focused bank compared to large-scale national institutions.
- Digital Infrastructure: While the bank maintains online banking portals, users who prioritize cutting-edge fintech features, such as sophisticated expense tracking, instant peer-to-peer payment integration, or aggressive high-yield online savings rates, may find the experience more traditional than what "neobanks" offer.
- Geographic Scope: The bank’s services are optimized for those living and working within its branch footprint in New York. Customers who relocate outside of this area may find it difficult to manage their accounts compared to a national bank with branches in every state.
- Scale: Because of its smaller asset size, the bank may not offer the full suite of investment banking, wealth management, or complex credit products that large multinational corporations or high-net-worth individuals might require.
Frequently Asked Questions
1. Is my money safe at Abacus Federal Savings Bank?
Yes. Abacus is a regulated financial institution. Deposits are insured by the Federal Deposit Insurance Corporation (FDIC) up to the maximum amount allowed by law, which is $250,000 per depositor, per ownership category.
2. Can I manage my Abacus account online?
Yes, the bank provides digital banking services that allow customers to view account balances, transfer funds, and manage transactions remotely. However, it is designed for standard management rather than advanced fintech operations.
3. Does Abacus offer loans for people with limited credit history?
Abacus is known for taking a more manual, human-centric approach to underwriting. While they still adhere to safety and soundness standards, their loan officers often have more flexibility to review a borrower's full financial picture compared to the automated credit scoring systems used by major banks.
4. What language assistance is available?
The bank is specifically staffed to provide services in multiple languages, including Mandarin and Cantonese. This is a primary feature of their commitment to serving the New York Chinese-American community.
5. How do I start the mortgage application process?
You should begin by visiting a branch to speak with a mortgage loan officer. They will review your financial documentation and provide a checklist of requirements specific to the type of property you are interested in purchasing or refinancing.
Practical Next Steps for Prospective Customers
If you are considering Abacus Federal Savings Bank as your primary financial institution, your first step should be to identify the branch closest to your home or place of business. Visiting in person is the most effective way to understand the bank's culture and verify that their current offerings meet your specific financial goals.
Gather your identification documents—specifically your government-issued ID and tax documents—before your visit. By initiating a conversation with a branch representative, you can gain clarity on interest rates, account fees, and the specific terms of any lending products you may be interested in. Engaging with the bank directly allows you to assess the quality of customer service firsthand, which is often the most important factor in a long-term banking relationship.