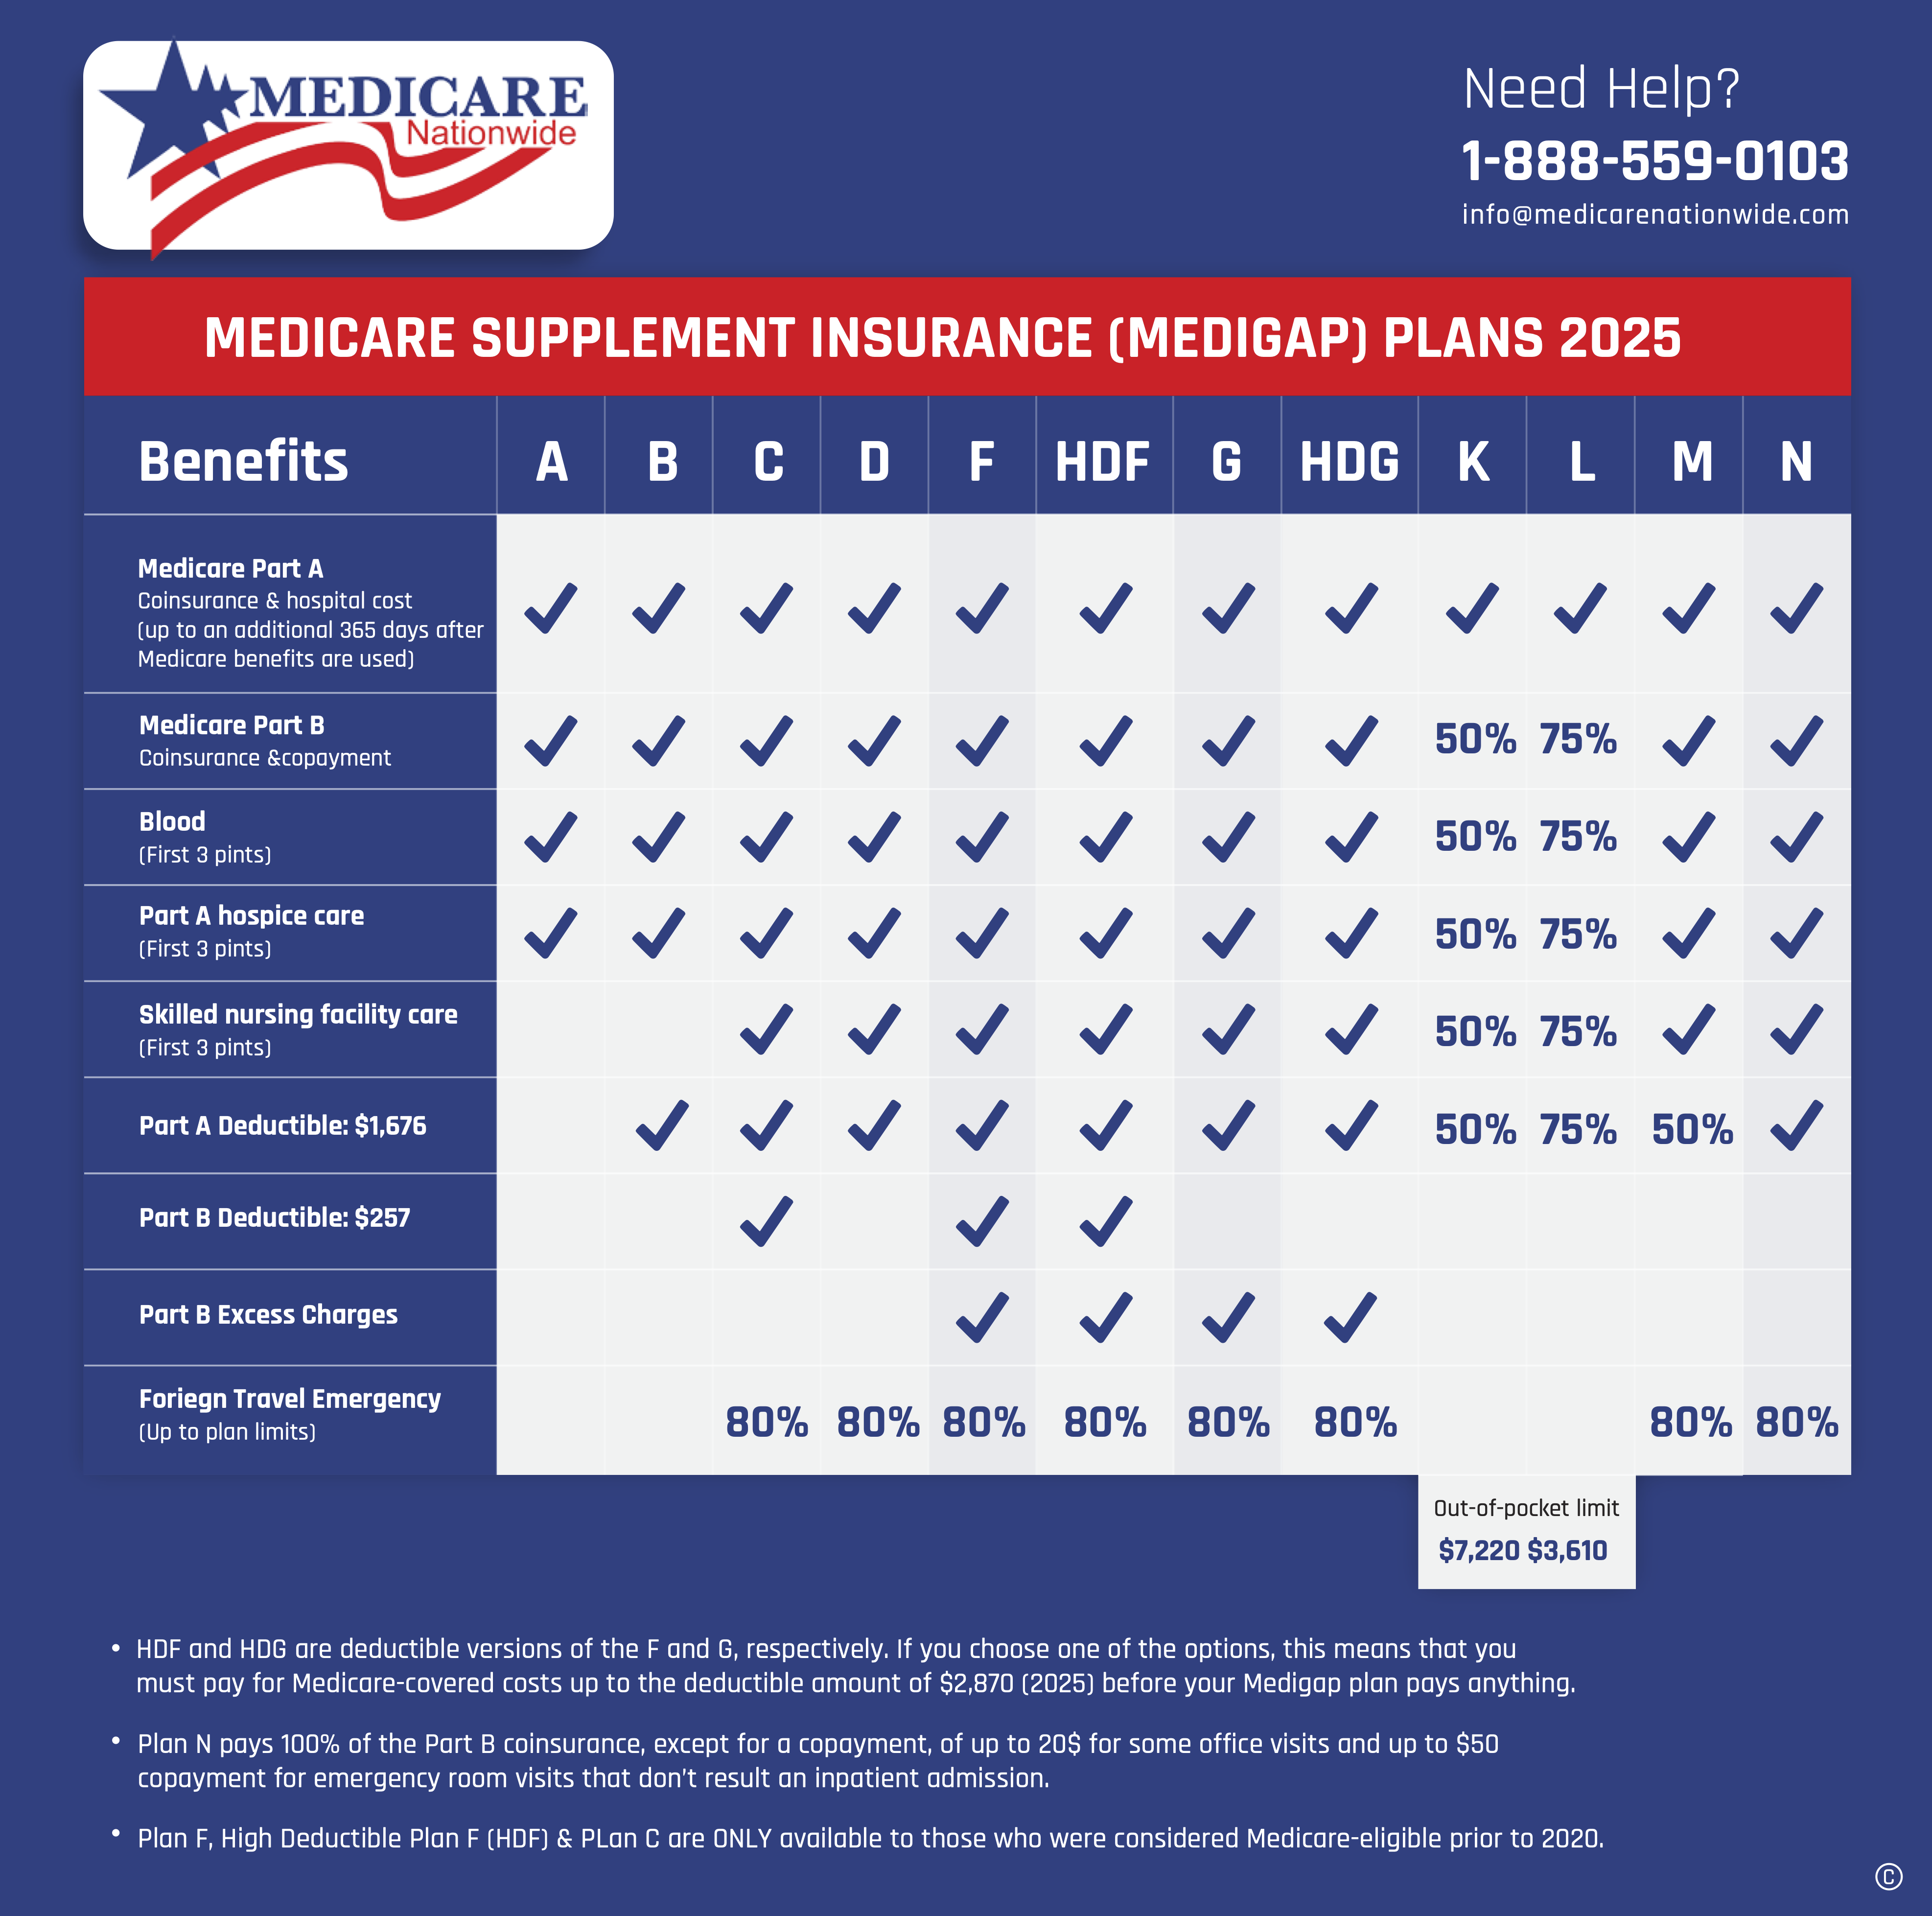
Admiral Life Insurance Medicare Supplement insurance, often referred to as Medigap, is a private insurance policy designed to cover the "gaps" in costs left by Original Medicare (Part A and Part B). In 2026, these plans specifically help beneficiaries pay for out-of-pocket expenses such as deductibles, copayments, and coinsurance, providing financial predictability for senior healthcare.
Medicare Supplement plans offered by Admiral Life Insurance Company of America—a subsidiary of Nassau Financial Group—are standardized by the federal government but sold and administered by the company. Because Original Medicare typically only covers about 80% of outpatient medical expenses, an Admiral Life Medigap policy ensures that the remaining 20% does not become a significant financial burden for the policyholder.
Understanding Admiral Life Insurance Company of America
To evaluate the value of a Medicare Supplement policy, one must first understand the carrier behind it. Admiral Life Insurance Company of America is a well-established entity in the senior market. It operates under the umbrella of Nassau Financial Group, a firm with deep roots in the insurance and annuity sectors.
In 2026, Admiral Life remains a focused provider of health and life insurance products, known for competitive pricing in specific geographic regions. Being part of a larger financial group like Nassau provides Admiral Life with the capital backing and administrative infrastructure necessary to process claims efficiently. For policyholders, this means their coverage is supported by a company with a stable financial outlook, often reflected in their AM Best financial strength ratings.
When you purchase a policy through Admiral Life, you are entering a contract that is "guaranteed renewable." This is a crucial protection in 2026; as long as you pay your premiums on time, the company cannot cancel your coverage based on your health status, regardless of how many claims you file or how your medical condition changes over time.
How Medicare Supplement Plans Work with Original Medicare
Medicare Supplement insurance is not a standalone product. It is designed to work exclusively with Original Medicare. It is important to distinguish these plans from Medicare Advantage (Part C). While Medicare Advantage replaces Original Medicare with a private managed-care network, a Medigap plan from Admiral Life sits on top of your Original Medicare benefits.
When you receive a medical service, Medicare first pays its share of the approved amount. Then, the bill is electronically "crossed over" to Admiral Life. The insurance company then pays its portion based on the specific plan you have selected (such as Plan G or Plan N). This seamless integration is one of the primary reasons seniors choose Medigap; it eliminates the need for the policyholder to act as a middleman between the doctor and the insurance company for most routine claims.
Furthermore, Admiral Life Medicare Supplement plans offer "freedom of access." Unlike Advantage plans, which often require you to stay within a specific network of doctors, a Medigap policy allows you to visit any provider in the United States that accepts Medicare. This is particularly beneficial for those who travel frequently or wish to see specialists at major national medical centers.
Popular Admiral Life Medigap Plans in 2026
While there are several standardized Medigap plans (labeled A through N), Admiral Life typically focuses on the most popular options that provide the best balance of premium cost and coverage depth. In 2026, the most sought-after plans are Plan G and Plan N.
Medicare Supplement Plan G
Plan G has become the "gold standard" for new Medicare enrollees. Since Plan F is no longer available to those who became eligible for Medicare after January 1, 2020, Plan G offers the highest level of coverage for new beneficiaries.
With Plan G, the only out-of-pocket cost for Medicare-covered services is the annual Part B deductible. Once that deductible is met, Plan G covers 100% of all remaining Medicare-approved costs, including hospital coinsurance, skilled nursing facility coinsurance, and Part B excess charges. For many seniors, the peace of mind knowing they will never see a surprise medical bill is worth the higher monthly premium associated with Plan G.
Medicare Supplement Plan N
Plan N is an excellent option for those looking for lower monthly premiums while still maintaining robust protection. It covers the same core benefits as Plan G but introduces small cost-sharing requirements. Under Plan N, you may be responsible for a copayment of up to $20 for some office visits and up to $50 for emergency room visits that do not result in an inpatient admission.
Additionally, Plan N does not cover Part B "Excess Charges." These occur if a provider does not accept "assignment" (the Medicare-approved amount) and charges up to 15% more. While excess charges are rare in many states, it is a factor to consider when choosing between N and G.
High-Deductible Plan G
For the budget-conscious consumer in 2026, Admiral Life may offer a High-Deductible version of Plan G. This plan offers the same comprehensive coverage as standard Plan G once a high annual deductible is reached. The benefit is a significantly lower monthly premium, making it a form of "catastrophic" coverage for those who are generally healthy but want protection against a major health event.
Eligibility and the Open Enrollment Period
Eligibility for an Admiral Life Medicare Supplement plan is generally tied to enrollment in Medicare Part A and Part B. However, the timing of your application is the most critical factor in determining your premium and whether you will be accepted.
The Medicare Supplement Open Enrollment Period is a six-month window that begins the first day of the month you are both 65 or older and enrolled in Medicare Part B. During this window, you have "guaranteed issue" rights. This means Admiral Life cannot:
- Refuse to sell you any Medigap policy they offer.
- Charge you more than someone with no health problems.
- Make you wait for coverage to start (except in some cases involving pre-existing conditions).
If you apply for an Admiral Life policy outside of this window, or without a specific "guaranteed issue" right (such as losing employer coverage), you will likely be subject to medical underwriting. During this process, the company will ask health questions and review your medical history. They can deny coverage or charge higher premiums based on your health status. Therefore, enrolling during your initial window is highly recommended to secure the lowest possible rates.
Cost Factors and Rating Methods
The cost of an Admiral Life Medicare Supplement policy is influenced by several factors beyond just the plan level (A, G, or N). Understanding how these premiums are calculated is vital for long-term financial planning.
| Feature | Plan G | Plan N | Plan A |
|---|---|---|---|
| Part A Deductible | Covered 100% | Covered 100% | Not Covered |
| Part B Deductible | Not Covered | Not Covered | Not Covered |
| Part B Coinsurance | Covered 100% | Covered (with copays) | Covered 100% |
| Part B Excess Charges | Covered 100% | Not Covered | Not Covered |
| Skilled Nursing Coinsurance | Covered 100% | Covered 100% | Not Covered |
| Foreign Travel Emergency | 80% (up to limits) | 80% (up to limits) | Not Covered |
Rating Methods
Insurance companies use three main methods for pricing:
- Community-rated: Everyone pays the same premium regardless of age.
- Issue-age-rated: The premium is based on your age when you first buy the policy; it doesn't increase specifically because you get older.
- Attained-age-rated: The premium is based on your current age and increases as you grow older.
Admiral Life often utilizes attained-age or issue-age structures depending on state regulations. It is important to ask which rating method applies in your state, as this determines how your costs will scale over the next 10 to 20 years.
Household Discounts
One of the competitive advantages of Admiral Life in 2026 is their Household Discount (HHD). In many states, if two people living in the same household both hold a policy with Admiral Life or its affiliates, they may receive a discount on their monthly premiums (often ranging from 5% to 12%). Some states even allow the discount if you simply live with another adult, even if they don't have a policy.
The Role of Part B Excess Charges
A nuanced but important aspect of "Admiral Life insurance Medicare supplement explained" is the coverage of Part B Excess Charges. As mentioned earlier, Plan G covers these, while Plan N does not.
A Part B Excess Charge occurs when a physician is a "non-participating" provider. This means they accept Medicare but haven't signed a contract to accept the Medicare-approved amount as full payment. They are legally allowed to charge up to 15% above the Medicare-approved rate.
While the majority of doctors today accept Medicare assignment, some specialists in high-demand areas or certain states (like New York or Connecticut, where excess charges are limited or prohibited by state law) may not. If you choose Plan N from Admiral Life, you should always ask your provider if they accept "Medicare assignment" to avoid these extra costs. If you have Plan G, this is not a concern, as the policy pays the excess amount for you.
Comparing Admiral Life to Other Carriers
When shopping for Medigap in 2026, it is tempting to focus solely on the monthly premium. However, because Medigap plans are standardized by law, the benefits of Plan G from Admiral Life are identical to Plan G from any other company (like AARP/UnitedHealthcare or Mutual of Omaha).
The differences lie in:
- Premium Stability: How often and by how much does the company raise rates each year? Admiral Life’s history under Nassau Financial Group suggests a focus on long-term stability rather than "teaser" rates that spike after the first year.
- Customer Service: The ease of reaching a representative and the speed of claims processing.
- Underwriting Flexibility: If you are outside your open enrollment period, Admiral Life may have different health questions or look-back periods compared to competitors.
Before committing, it is wise to look at the "loss ratio" of the carrier in your state. A healthy loss ratio indicates that the company is paying out a reasonable percentage of premiums as benefits, which often correlates with more stable future pricing.
Common Questions About Admiral Life Medicare Supplement
Does Admiral Life cover prescription drugs? No. In 2026, no Medicare Supplement plan sold to new enrollees covers outpatient prescription drugs. To get drug coverage, you must enroll in a standalone Medicare Part D plan. Admiral Life focuses on the medical and hospital costs (Parts A and B) only.
Can I use my Admiral Life policy for dental or vision care? Standard Medigap plans do not cover routine dental, vision, or hearing services, as these are not covered by Original Medicare. However, some agents may offer "ancillary" policies through Admiral Life or Nassau to provide these specific benefits as a separate addition to your health coverage.
Will my doctor accept Admiral Life? This is a common misconception. Your doctor does not "accept" Admiral Life; they accept Medicare. Because Medicare is the primary payer, if your doctor accepts Medicare, they are required by their agreement with CMS to accept your Medigap insurance, regardless of which private company provides it.
What happens if I move to another state? Since Medigap policies are portable, your coverage will move with you. However, your premium may change based on the zip code of your new residence. You do not need to re-apply or go through medical underwriting if you move, provided you keep the same plan level.
Summary of Benefits and Next Steps
Choosing a Medicare Supplement plan from Admiral Life is a strategy for mitigating the unpredictable costs of healthcare. By paying a monthly premium, you transfer the risk of high deductibles and coinsurance to the insurer.
For those entering Medicare in 2026, the process should begin with a review of your current health needs and budget. If you prefer a "set it and forget it" approach with almost no out-of-pocket costs, Plan G is the recommended path. If you are looking to save on premiums and don't mind small copays at the doctor’s office, Plan N is a sophisticated alternative.
To proceed, verify your Open Enrollment window. If you are within that six-month period, you can apply for an Admiral Life policy with guaranteed acceptance. If you are outside that window, consult with an independent insurance broker who can help you navigate the medical underwriting questions to ensure you qualify for the best possible rate.
Frequently Asked Questions
Is Admiral Life the same as Nassau Re? Admiral Life is a subsidiary of Nassau Financial Group (formerly known as Nassau Re). While they may use different names for different product lines or in different states, the financial backing and corporate governance are the same.
How do I file a claim with Admiral Life? In almost all cases, you do not need to file a claim yourself. When your doctor bills Medicare, the information is automatically sent to Admiral Life through the Medicare crossover system. The insurer pays the provider directly for the "gap" expenses.
Can I switch from a Medicare Advantage plan to Admiral Life? Yes, but typically only during specific times of the year, such as the Annual Enrollment Period (Oct 15 – Dec 7). Be aware that unless you are in a "trial right" period, you will likely have to answer health questions and pass medical underwriting to switch from Advantage back to a Medigap policy.
What is the "Household Discount" for Admiral Life? The Household Discount is a reduction in premium for individuals living with another adult. The exact rules vary by state; in some locations, the other adult must also have an Admiral Life policy, while in others, they simply need to be a resident in your home.
Does Admiral Life cover SilverSneakers? While many Medicare Advantage plans offer fitness programs like SilverSneakers, Medicare Supplement plans do not always include them. You should check the specific "extra benefits" offered by Admiral Life in your state for the 2026 plan year to see if a gym membership or fitness benefit is included.