Arid net worth refers to the total value of an individual's or entity's illiquid assets that cannot be quickly converted into cash without a significant loss in value. Unlike liquid net worth, arid net worth represents "frozen" or "dry" capital—such as real estate, private equity, and specialized collectibles—that provides long-term stability but limited immediate purchasing power.
Understanding the distinction between your total net worth and your arid net worth is a fundamental pillar of modern financial planning. As we navigate the economic landscape of 2026, the reliance on high-value, low-liquidity assets has reached record levels. While a high net worth suggests wealth on paper, a disproportionately high arid net worth can lead to "asset-rich, cash-poor" scenarios where an individual struggles to meet immediate obligations despite owning millions in valuation.
Defining the Arid Concept in Personal Finance
In the lexicon of wealth management, "arid" is a descriptive term used to categorize assets that lack "flow." Just as an arid landscape lacks water, an arid net worth lacks the fluid movement of capital. This category includes any asset that requires a lengthy sales process, significant transaction costs, or specialized buyers to realize its market value.
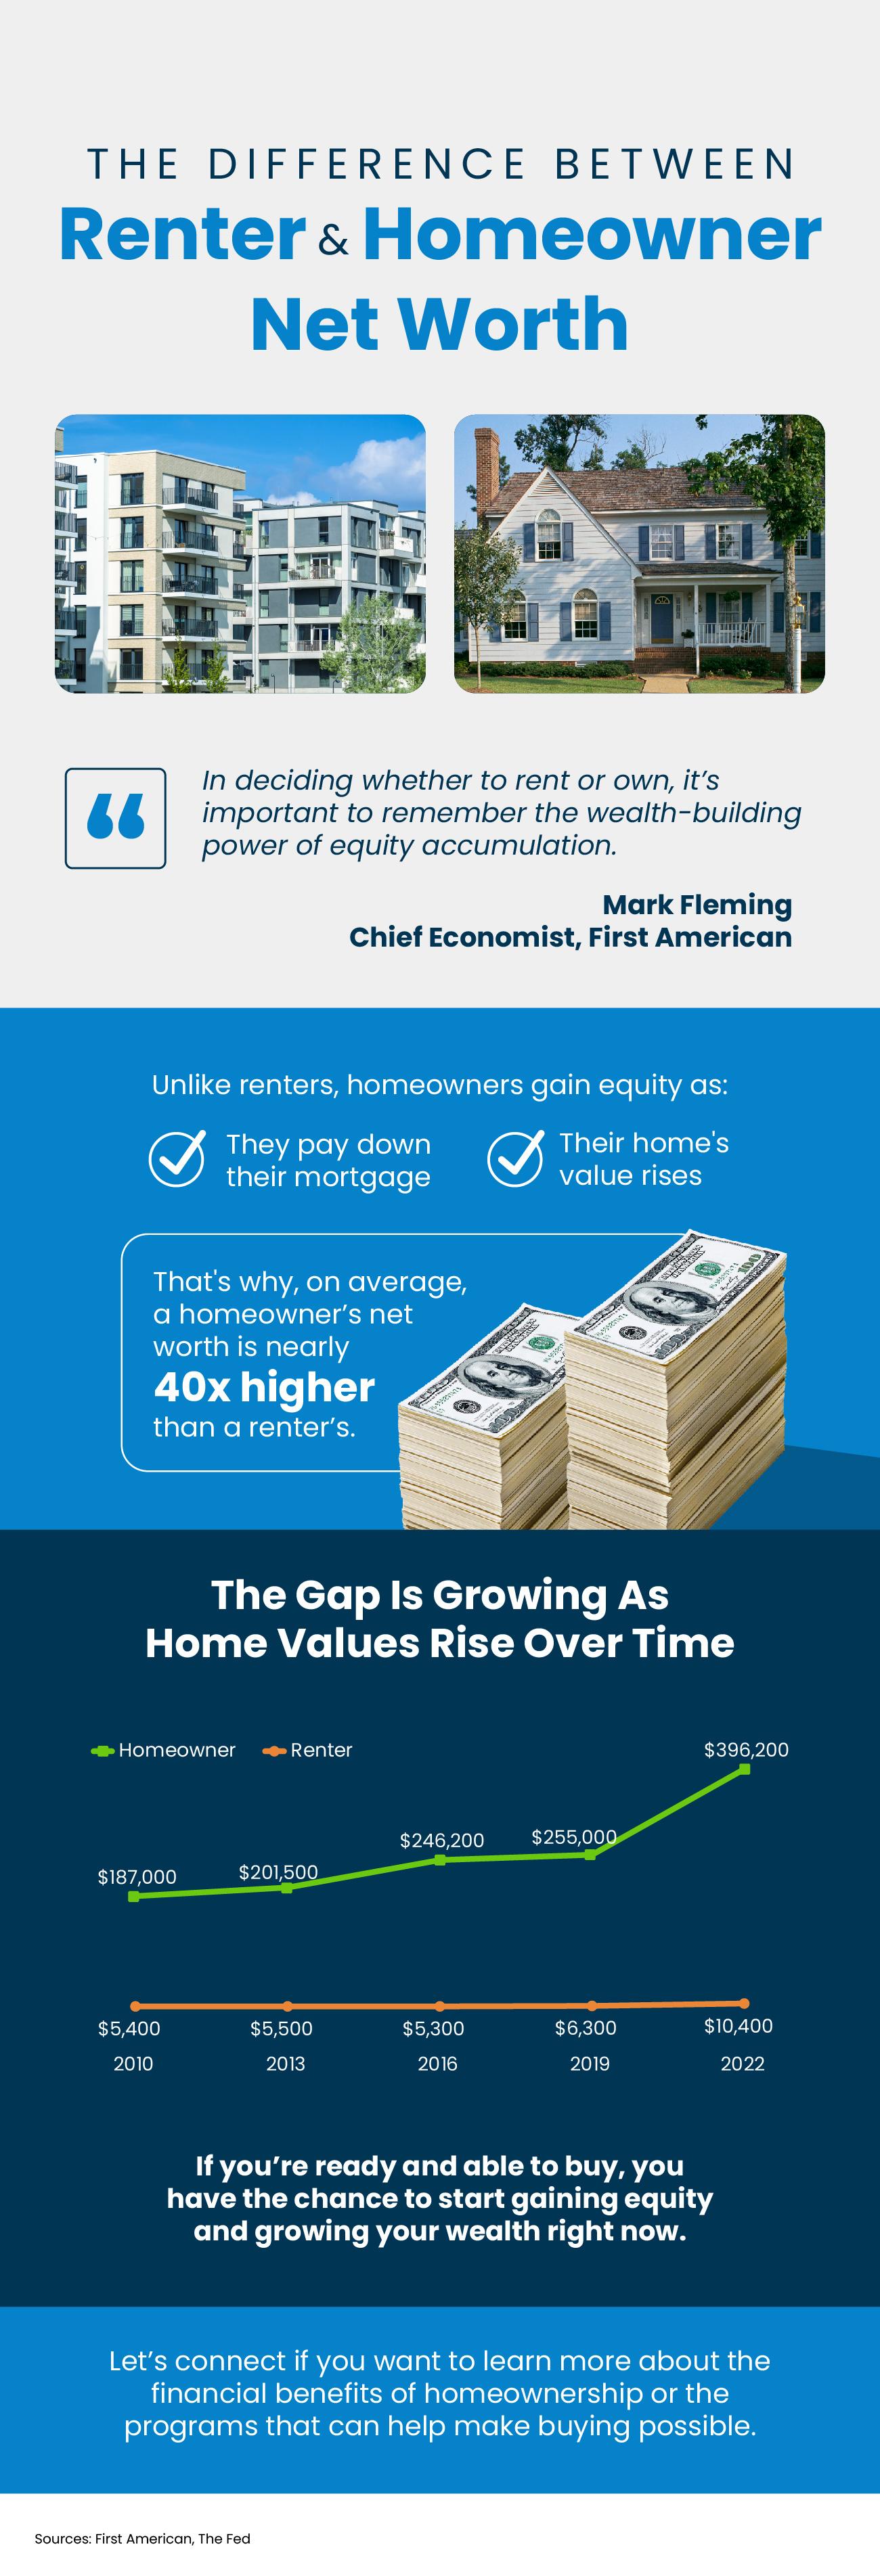
Standard net worth is calculated by subtracting total liabilities from total assets. However, this figure is often misleading. For instance, a homeowner with $2 million in equity and $5,000 in a checking account has a high net worth but a very high arid ratio. If an emergency arises, that $2 million is functionally inaccessible for 30 to 90 days—the typical duration of a real estate transaction in 2026.
The Calculation Formula
To determine your arid net worth, you must isolate assets that fall outside the "liquid" definition (cash, money market funds, and publicly traded stocks). The formula is generally:
Total Value of (Real Estate + Private Business Interests + Retirement Accounts with Penalties + Collectibles + Locked Digital Assets) - Associated Debt = Arid Net Worth.
The Core Components of Arid Net Worth
To manage wealth effectively, one must categorize assets based on their time-to-cash conversion. In 2026, the complexity of these assets has increased due to new regulatory environments and shifting market demand.
Real Estate Holdings
Real estate remains the most common driver of arid net worth. Whether it is a primary residence, a commercial office building, or undeveloped land, these assets are inherently illiquid. Selling a property involves appraisals, inspections, title searches, and financing contingencies. Even with the "Fast-Track Digital Closing" standards introduced in 2025, a residential sale rarely settles in fewer than 21 days. Furthermore, the high transaction costs (commissions and taxes) mean that the "paper value" is rarely what the owner receives in hand.
Private Equity and Venture Capital
For high-net-worth individuals, private equity represents a significant portion of their "dry" wealth. These are investments in companies not listed on public exchanges. In 2026, the secondary market for private shares has grown, but these transactions still require board approval and lengthy due diligence periods. Capital is often "called" and then locked for 5 to 10 years, making this a prime example of an arid asset.
Retirement and Pension Funds
While a 401(k) or an IRA contains liquid stocks, the account itself is often considered arid until the owner reaches age 59½. Prior to this, the 10% early withdrawal penalty and immediate tax liability act as a barrier to liquidity. In a technical sense, these funds are "semi-arid" because they can be accessed in an emergency, but the friction cost of doing so is prohibitively high.
Specialized Collectibles and Tangible Assets
This category includes fine art, classic automobiles, rare jewelry, and high-end watches. While these assets have seen tremendous appreciation over the last decade, finding a buyer at the "appraised value" can take months. Auctions are seasonal, and private sales require verified provenance, which adds to the aridity of the asset.
Why Arid Net Worth Matters for Your Financial Health
The primary reason to track arid net worth is to assess solvency vs. liquidity. Solvency is the ability to pay all debts if all assets were sold; liquidity is the ability to pay immediate bills with available cash. Many financial failures in the mid-2020s occurred not because individuals were "broke," but because their wealth was too arid to respond to market shifts.
The Risk of the "Illiquidity Trap"
The illiquidity trap occurs when an individual’s arid assets represent more than 80% of their total wealth during an economic downturn. When asset values drop, lenders may call in loans or reduce lines of credit. If the individual cannot sell their arid assets quickly to cover the gap, they may be forced into a "fire sale," where they accept 60% or 70% of the asset's true value just to generate immediate cash.
Impact on Credit and Borrowing Power
In 2026, lenders use sophisticated algorithms to weigh net worth. A borrower with a $5 million arid net worth (locked in land) may receive a higher interest rate on a personal loan than a borrower with a $1 million liquid net worth. Lenders prioritize "accessible collateral." Understanding your arid ratio allows you to negotiate better terms by demonstrating that you have sufficient "buffer" capital to service debt without selling your primary "dry" assets.
Strategic Tax Planning
Arid assets often come with significant tax advantages, such as depreciation on real estate or the "Step-up in Basis" rule for inherited property. However, they also present a challenge: you cannot pay taxes with a piece of a house. Estate planners focus on arid net worth to ensure that heirs have enough liquid cash to pay inheritance taxes without being forced to sell the family business or home.
Arid vs. Liquid Net Worth: A Comparative Analysis
The following table highlights the functional differences between these two wealth categories in the 2026 economic environment.
| Feature | Liquid Net Worth | Arid (Illiquid) Net Worth |
|---|---|---|
| Asset Examples | Cash, Savings, T-Bills, Public Stocks | Primary Home, Private Equity, Art, Land |
| Conversion Time | 1 to 5 business days | 30 days to 2 years |
| Transaction Costs | Minimal (Brokerage fees) | High (6-10% for Real Estate/Art) |
| Valuation Accuracy | Real-time market pricing | Subjective (Appraisals/Estimates) |
| Primary Purpose | Emergency fund, daily expenses | Wealth preservation, legacy, tax hedges |
| Volatility Risk | High daily fluctuations | Low daily fluctuations; high exit risk |
| 2026 Accessibility | High (Instant Digital Transfers) | Moderate (Dependent on Market Demand) |
Managing and Balancing Arid Assets
A healthy financial profile requires a balance. Financial advisors generally recommend that individuals maintain a "Liquidity Ratio" where at least 15% to 25% of their total net worth remains liquid.
Diversification Strategies
To prevent your net worth from becoming too arid, you should consider "bridging" assets. These are investments that offer the growth of arid assets but with better exit options. Examples include:
- REITs (Real Estate Investment Trusts): Provides exposure to property but can be sold on the stock market instantly.
- Secondary Market Funds: Funds that specialize in buying private equity stakes, offering slightly more liquidity than direct private investment.
- High-Yield Cash Reservoirs: Keeping 6-12 months of expenses in U.S. Treasury bills or money market accounts.
Monitoring Market Cycles
Arid assets are highly sensitive to interest rates. In 2026, as the Federal Reserve manages inflation targets, the cost of borrowing directly affects the pool of buyers for your arid assets. If rates are high, your "arid" wealth becomes even harder to move because fewer people can afford to finance the purchase of your real estate or business.
Risks of a High Arid-to-Liquid Ratio
The most significant risk of a high arid net worth is opportunity cost. When a lucrative investment opportunity arises—such as a market dip where stocks are "on sale"—those with high arid net worth cannot pivot. Their money is "stuck" in a house or a private venture, preventing them from capitalizing on short-term market inefficiencies.
Moreover, arid assets often incur "carrying costs." A vacant plot of land or a classic car collection requires property taxes, insurance, maintenance, and storage fees. If these costs exceed the liquid income generated by the individual, the arid assets actually begin to "bleed" the liquid net worth, leading to a slow-motion financial crisis.
Frequently Asked Questions
What is a "good" ratio of arid to liquid net worth?
While it varies by age and income level, a common benchmark is 70% arid and 30% liquid. For retirees, the liquid portion should ideally be higher to cover living expenses without relying on property sales. Younger professionals can afford a higher arid ratio (up to 85%) as they are in the wealth-accumulation phase and have time to wait for illiquid assets to mature.
Can digital assets like Bitcoin be considered arid net worth?
It depends on the storage method. Bitcoin held on a standard exchange is liquid. However, Bitcoin or Ethereum "staked" in a protocol with a mandatory 12-month lock-up period, or NFTs (Non-Fungible Tokens) that lack an active daily market, are classified as arid net worth. In 2026, "locked" governance tokens are a significant contributor to the arid net worth of tech-savvy investors.
Does my primary residence count toward my arid net worth?
Yes. Your primary residence is the quintessential arid asset. While it has value, you cannot "spend" your kitchen or your roof. Furthermore, selling your primary residence requires you to find a new place to live, which often involves re-investing that capital immediately, making the net gain less "liquid" than it appears on a balance sheet.
How can I reduce the "aridity" of my portfolio without selling assets?
You can use strategies like Asset-Backed Lending. In 2026, many banks allow you to take out a line of credit against your private equity or art collection. This provides liquidity without triggering a taxable sale. However, this adds debt to your balance sheet and should be managed carefully to avoid over-leveraging.
Why is arid net worth more important now than in the past?
In previous decades, the majority of middle-class wealth was in liquid savings or pensions. Today, with the rise of "gig economy" business ownership, the decline of traditional pensions, and the skyrocketing value of real estate, more people have their wealth "locked up" than ever before. This makes understanding the arid component essential for avoiding cash flow crises.
Recommendations for 2026
To optimize your financial position this year, perform a "Liquidity Audit." List every asset you own and estimate how long it would take to receive cash for it at a fair market price. If more than 80% of your wealth takes longer than 30 days to access, you are in a high-risk arid position.
Focus on building a "Liquid Buffer" that is independent of your home equity or retirement accounts. In the volatile economic climate of 2026, cash and cash equivalents are not just for spending—they are a strategic tool that protects your arid assets from being sold at a discount during a crisis. Balance your portfolio so that your "dry" wealth provides the foundation for your future, while your "wet" wealth powers your present.