Choosing the right home and auto insurance in Amarillo involves balancing protection against the region’s extreme weather risks—specifically high winds and frequent hail—with cost-effective policy structures. Residents should prioritize replacement cost coverage for dwellings and high liability limits for vehicles, while leveraging multi-policy bundling to mitigate the rising premiums seen across the Texas Panhandle in 2026.
The Unique Risk Profile of the Texas Panhandle
Amarillo is situated in a geographic zone that presents specific challenges for insurance underwriters and policyholders alike. Known for its persistent winds and location within "Hail Alley," the city requires a more nuanced approach to insurance than more temperate regions. To choose the right coverage, one must first understand the environmental factors that drive local premiums and claim frequencies.
Wind and Hail: The Primary Drivers
In the Texas Panhandle, wind and hail are not just occasional nuisances; they are the primary causes of property loss. In 2026, many national carriers have adjusted their underwriting guidelines for the 806 area code to account for the increasing severity of spring storms. When selecting home insurance, the "Wind and Hail Deductible" is often the most significant variable. Unlike a standard flat-dollar deductible (e.g., $1,000), wind and hail deductibles in Amarillo are frequently calculated as a percentage of the home’s total insured value—usually 1%, 2%, or even 5%.
Wildfire and Urban Interface Risks
While the city center is relatively protected, homes on the outskirts of Amarillo, particularly near the canyons or undeveloped grasslands, face significant wildfire risks. Choosing the right coverage means ensuring your policy does not have restrictive exclusions for fire damage in high-risk zones.
Road Safety and the I-40 Corridor
For auto insurance, Amarillo presents a unique risk due to the high volume of commercial trucking traffic on Interstate 40. The mix of local commuters and heavy long-haul freight increases the statistical likelihood of high-impact collisions. This necessitates higher liability limits than the Texas state minimums to protect personal assets from litigation following a major accident.
Home Insurance: Protecting Your Amarillo Property
Selecting home insurance in Amarillo requires moving beyond the "lowest premium" mindset. Because the cost of building materials and labor in West Texas has continued to rise through 2026, an undervalued policy can leave a homeowner with a massive financial gap after a total loss.
Replacement Cost vs. Actual Cash Value
The most critical decision a homeowner makes is between Replacement Cost Value (RCV) and Actual Cash Value (ACV).
- Replacement Cost Value: This pays to repair or replace your home and belongings with materials of "like kind and quality" at today's prices, without deducting for depreciation. In a city where a roof might need replacing every 7 to 10 years due to hail, RCV is the gold standard.
- Actual Cash Value: This pays the value of the item at the time of loss, accounting for wear and tear. If your 10-year-old roof is destroyed, an ACV policy might only pay a fraction of the cost for a new one, leaving you to cover the difference out of pocket.
Understanding Dwelling Coverage (Coverage A)
Coverage A should reflect the actual cost to rebuild your home, not its market value. In Amarillo’s 2026 real estate market, market value includes the land and location, but insurance only cares about the sticks, bricks, and labor. Ensure your agent performs a fresh "Replacement Cost Estimator" (RCE) to account for current local construction costs.
Essential Endorsements for the Panhandle
- Sewer and Drain Backup: This is rarely included in a standard policy but is vital in Amarillo, where sudden heavy downpours can overwhelm local drainage systems, causing basement or crawlspace flooding.
- Law and Ordinance Coverage: If your home is older (e.g., in the Wolflin or Plemons-Eakle areas), rebuilding after a loss might require upgrades to meet 2026 building codes. This endorsement covers those mandatory extra costs.
- Foundation/Slab Coverage: The clay-heavy soil in the Panhandle shifts frequently, especially during the extreme cycles of drought and heavy rain. Standard policies often exclude foundation repair unless it is caused by a covered plumbing leak.
Auto Insurance: Navigating the 806 Roads
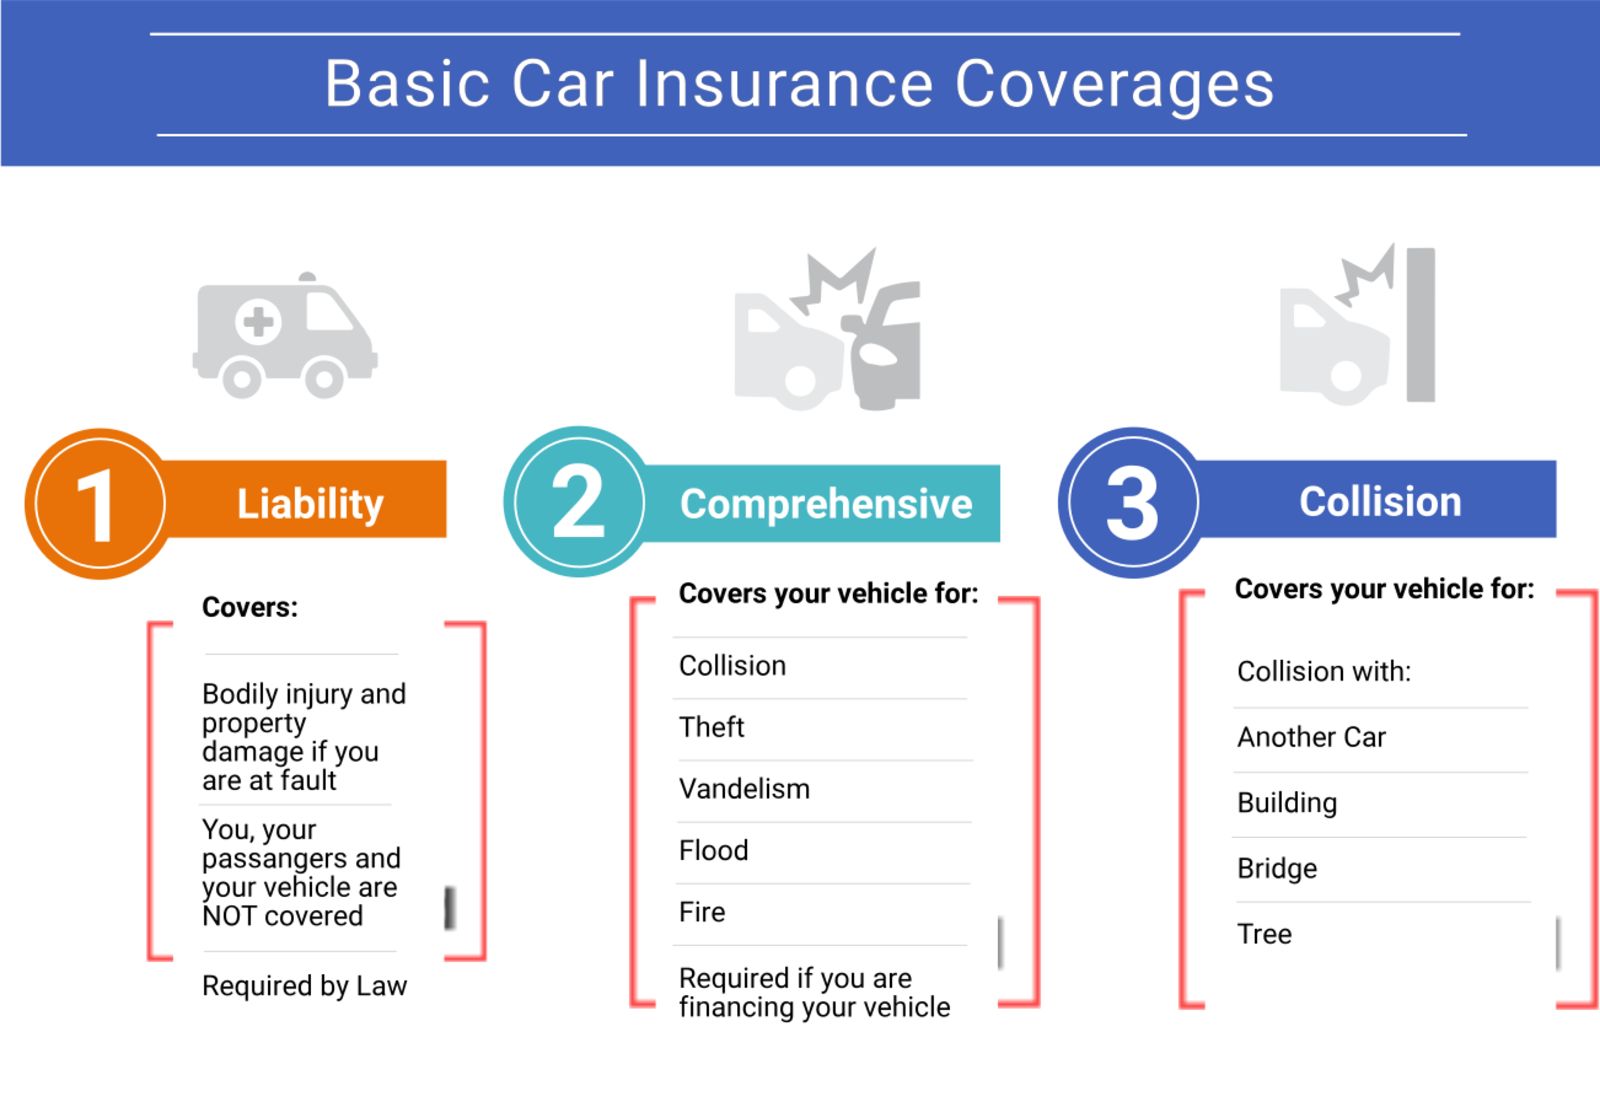
Texas law requires drivers to carry basic liability insurance, but in Amarillo, the "minimum" is rarely "enough." As vehicle technology has become more complex and expensive to repair, a minor fender-bender in 2026 can easily exceed basic policy limits.
Liability Limits: 30/60/25 vs. The Reality
The Texas state minimum for auto liability is 30/60/25 ($30,000 per person for injuries, $60,000 per accident for injuries, and $25,000 for property damage). Consider this: The average cost of a new pickup truck in Amarillo in 2026 often exceeds $60,000. If you are at fault in an accident that totals a late-model vehicle, a $25,000 property damage limit leaves you personally liable for the remaining $35,000. Experts recommend at least 100/300/100 limits for most Amarillo drivers.
Uninsured and Underinsured Motorist (UM/UIM)
Despite legal requirements, a significant percentage of drivers in the Panhandle remain uninsured or carry only the bare minimum. UM/UIM coverage is essential. It steps in to pay for your medical bills and vehicle repairs if you are hit by someone who lacks adequate insurance. Given the high-speed nature of traffic on Soncy Road or Loop 335, the potential for high-cost medical claims is significant.
Comprehensive Coverage and Glass Protection
In Amarillo, comprehensive coverage—which covers non-collision events—is largely a "hail and glass" policy. The gravel used on local roads, combined with high winds, makes windshield chips and cracks an almost annual occurrence. Check if your carrier offers a "Full Glass" endorsement with a $0 deductible; in this region, it often pays for itself within two years.
The Financial Benefits of Bundling in 2026
Bundling, or "multi-line discounting," remains the most effective way to lower total insurance costs in Amarillo. By placing both your home and auto policies with the same carrier, you create a more stable relationship with the insurer, which can be beneficial during the claims process.
Typical Bundle Savings
In 2026, Amarillo residents can expect a discount of 15% to 25% on their total premiums when bundling. Beyond the direct discount, many carriers now offer a "single deductible" feature. If a single hailstorm damages both your roof and the car parked in your driveway, you may only have to pay one deductible instead of two.
Loyalty vs. Shopping
While bundling provides a discount, the "loyalty tax" is a real phenomenon where rates creep up annually for long-term customers. Residents should review their bundled rates every two to three years. In Amarillo’s competitive 2026 market, independent agents can often compare regional carriers like Texas Farm Bureau or Germania against national giants to find the best local value.
Comparing Coverage Tiers for Amarillo Residents
The following table outlines three common coverage strategies for residents, ranging from basic legal compliance to comprehensive protection.
| Feature | The Budget Starter | The Standard Family | The Comprehensive Asset Protector |
|---|---|---|---|
| Home Valuation | Actual Cash Value (ACV) | Replacement Cost (RCV) | Guaranteed Replacement Cost |
| Wind/Hail Deductible | 2% or 5% | 1% | $500 or $1,000 Flat |
| Auto Liability | 30/60/25 (State Min) | 100/300/100 | 250/500/100 + Umbrella |
| UM/UIM Coverage | No | Yes | Yes (Max Limits) |
| Glass Coverage | Standard Deductible | Standard Deductible | $0 Deductible / Full Glass |
| Sewer/Drain Backup | Not Included | $5,000 Limit | $25,000+ Limit |
How to Verify Your Insurance Provider
Before signing a policy, it is imperative to verify the financial stability and licensing of the insurance company. The Texas Department of Insurance (TDI) provides a look-up tool to ensure the company is authorized to sell policies in the state and to review their complaint index.
Furthermore, check the A.M. Best Rating of the carrier. In a region prone to "catastrophic events" (CAT events) like major hailstorms, you need an insurer with the financial liquidity to pay out thousands of claims simultaneously. An "A" rating or higher is recommended for peace of mind in the Panhandle.
Step-by-Step Guide to Choosing Your Coverage
- Inventory Your Assets: Before calling an agent, document the age of your roof, the square footage of your home, and the safety features of your vehicles.
- Determine Your Risk Tolerance: Can you afford a $5,000 out-of-pocket expense for a 2% wind/hail deductible? If not, you must opt for a higher premium with a lower deductible.
- Request "Apples-to-Apples" Quotes: When shopping, ensure every carrier is quoting the same limits and deductibles. A "cheaper" quote often just hides a higher deductible or lower coverage limits.
- Review the Exclusions: Read the "Exclusions" section of your home policy carefully. In Amarillo, pay special attention to cosmetic hail damage exclusions—some policies won't pay for dented metal roofs or siding if they still function.
- Check for "Telematics" Discounts: Many auto insurers in 2026 offer significant discounts (up to 30%) if you allow them to track your driving habits via a smartphone app. Given Amarillo’s straightforward grid layout, safe drivers often benefit significantly from these programs.
Frequently Asked Questions
Does my home insurance cover flood damage from heavy Amarillo rains?
Standard home insurance policies do not cover "flooding," which is defined as rising surface water. If a heavy storm causes water to flow into your home from the street or a nearby playa lake, you would need a separate flood insurance policy through the National Flood Insurance Program (NFIP) or a private flood carrier. However, if the rain comes through a hole in the roof created by hail, that is generally covered.
Why are my Amarillo insurance rates higher than those in Dallas or Houston?
While Houston faces hurricanes, Amarillo’s frequency of hail and wind events is statistically higher. The "cost of risk" for roofs in the Panhandle is among the highest in the nation. Additionally, the distance from major distribution centers can sometimes increase the cost of specialized building materials, which is reflected in your premiums.
Can I change my wind/hail deductible mid-policy?
Generally, yes, but not if a storm is currently forecasted or if a "moratorium" has been placed on the area due to active weather. Increasing your deductible is a quick way to lower your monthly premium, but it increases your financial burden when a storm eventually hits.
Is "Gap Insurance" necessary for my car in Amarillo?
If you are financing or leasing a vehicle and put less than 20% down, Gap insurance is highly recommended. Because vehicles depreciate quickly, and Amarillo has a high rate of "total loss" accidents due to high-speed collisions, you could end up owing the bank more than the insurance company pays for the car's market value.
What is "Cosmetic Hail Exclusion" and should I accept it?
Some carriers offer a discount if you agree to a "cosmetic damage" exclusion. This means the insurer will not pay to fix hail dents on your metal roof, siding, or gutters if the damage is only visual and doesn't cause a leak. While this saves money on premiums, it can significantly hurt your home's resale value.
Final Recommendation for 2026
For the average Amarillo resident, the most balanced approach is an HO-3 or HO-B home policy with Replacement Cost coverage and a 1% wind/hail deductible, bundled with an auto policy featuring 100/300/100 liability limits. This configuration provides a robust safety net against the Panhandle’s volatility while keeping monthly costs manageable. Always consult with a local independent agent who understands the specific neighborhood risks from Bishop Hills to Southeast Amarillo.