AARP life insurance in Connecticut, underwritten by New York Life Insurance Company, provides residents aged 50 to 80 with accessible coverage options designed to meet the financial needs of seniors. These policies include term, permanent, and guaranteed acceptance life insurance, primarily focusing on simplified application processes that often bypass traditional medical examinations to ensure Connecticut members can secure protection for final expenses and legacy planning.
Life insurance remains a cornerstone of financial security for Connecticut residents entering their retirement years. As of 2026, the landscape of senior care and final expenses in the Nutmeg State continues to evolve, making the selection of an appropriate policy more critical than ever. The partnership between AARP and New York Life has long served as a primary resource for residents seeking straightforward coverage without the hurdles of extensive medical underwriting.
Understanding the AARP and New York Life Partnership
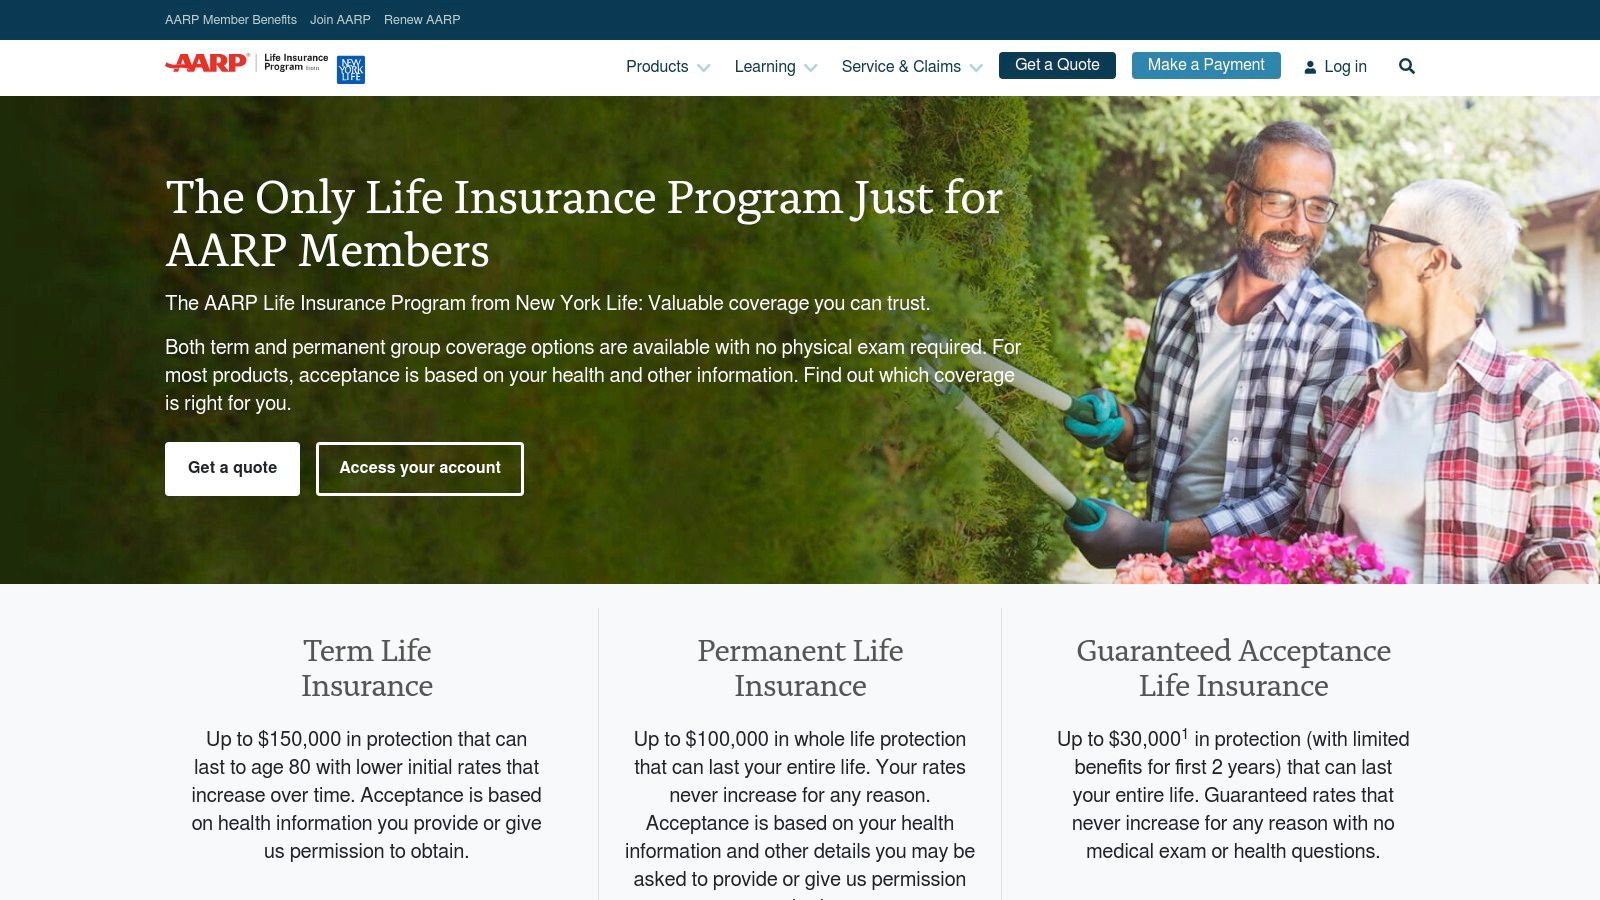
It is essential to clarify that AARP is not an insurance company. Instead, AARP advocates for the interests of people aged 50 and over and negotiates with providers to offer branded products to its members. In Connecticut, as in the rest of the United States, all AARP-branded life insurance products are issued and underwritten by New York Life Insurance Company.
New York Life is one of the oldest and most financially stable mutual life insurance companies in the country. For Connecticut residents, this means the policies are backed by a company with significant claims-paying ability. When you apply for "AARP Life Insurance," you are entering into a contract with New York Life, which manages the premiums, policy administration, and benefit payouts.
Types of AARP Life Insurance Available in Connecticut
Connecticut residents have access to three primary categories of life insurance through the AARP program. Each is tailored to different health profiles, financial goals, and age brackets.
1. AARP Term Life Insurance
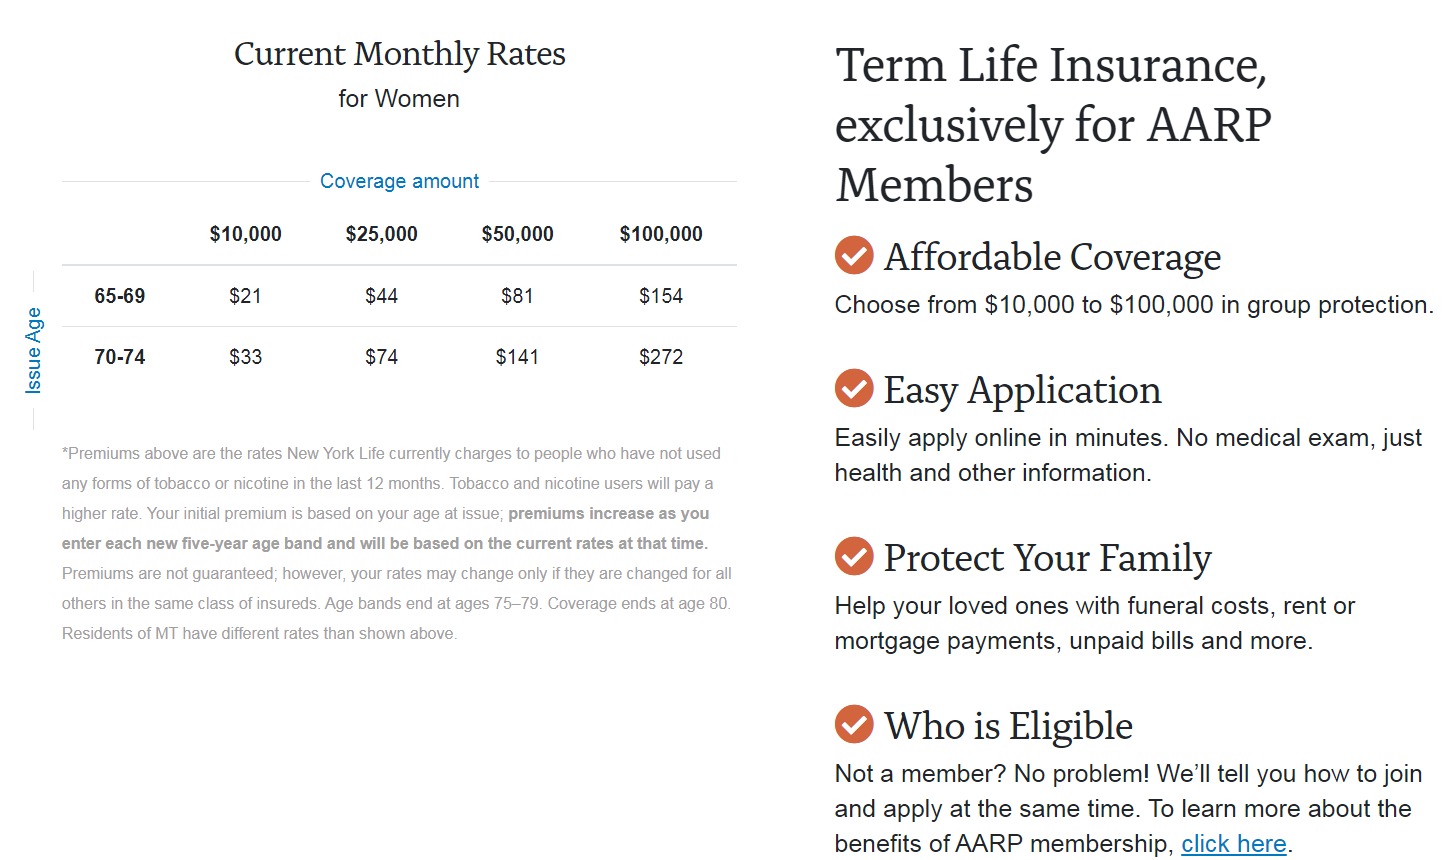
Term life insurance provides coverage for a specific period of time. For AARP members in Connecticut, this typically means coverage until age 80.
- Eligibility: Generally available to AARP members aged 50 to 74 (spouses 45 to 74).
- Coverage Amounts: Often ranges from $10,000 to $100,000, though higher amounts may be available based on underwriting.
- Premium Structure: Premiums are set in five-year age bands. This means that every five years—specifically when you move into a new age bracket (e.g., from 59 to 60)—your monthly or annual premium will increase.
- Underwriting: This is a "simplified issue" policy. While no medical exam is usually required, you must answer several health questions on the application. Coverage is not guaranteed if you have significant pre-existing conditions.
2. AARP Permanent Life Insurance (Whole Life)
Unlike term insurance, permanent life insurance is designed to last your entire life, provided premiums are paid. It is often used for final expense planning or leaving a specific inheritance.
- Eligibility: Available to AARP members aged 50 to 80 (spouses 45 to 80).
- Coverage Amounts: Usually capped at $50,000.
- Premium Structure: Premiums are fixed. Once you are accepted, your rate will never increase regardless of your age or changes in your health.
- Cash Value: Over time, these policies build "cash value" that can be borrowed against in emergencies, though this reduces the death benefit.
3. AARP Guaranteed Acceptance Life Insurance
This product is specifically designed for Connecticut residents who may have health issues that disqualify them from other types of insurance.
- Eligibility: Available to AARP members aged 50 to 80 (spouses 45 to 80).
- No Health Questions: There are no medical exams and no health questions. If you meet the age and membership requirements, you cannot be turned down.
- Graded Death Benefit: To account for the high risk of not screening applicants, these policies feature a "graded benefit" period. If the insured passes away from natural causes within the first two years of the policy, the beneficiaries receive the premiums paid plus a small percentage of interest, rather than the full face value. Accidental death is typically covered for the full amount from day one.
Policy Comparison for Connecticut Residents
Choosing the right plan requires a clear understanding of how these options differ in cost and longevity. The following table summarizes the key features of the primary AARP life insurance products available in 2026.
| Feature | Term Life Insurance | Permanent Life Insurance | Guaranteed Acceptance |
|---|---|---|---|
| Typical Age Range | 50–74 | 50–80 | 50–80 |
| Maximum Coverage | Up to $100,000+ | Up to $50,000 | Up to $25,000 |
| Medical Exam | Not required | Not required | Not required |
| Health Questions | Yes | Yes | No |
| Premium Status | Increases every 5 years | Fixed/Level | Fixed/Level |
| Policy Duration | Ends at age 80 | Lifelong | Lifelong |
| Cash Value | No | Yes | Yes |
The Application Process in Connecticut
The application process for AARP life insurance in Connecticut is streamlined to facilitate quick decisions. Most residents choose to apply online or via mail-in applications found in AARP publications.
Step-by-Step Application Guide:
- Membership Verification: You must be an active AARP member. If you are not, you can usually join during the insurance application process.
- Product Selection: Choose between Term, Permanent, or Guaranteed Acceptance based on your health and budget.
- Information Disclosure: Provide basic personal data, including your Social Security number and Connecticut residential address.
- Health Questionnaire: For Term and Permanent policies, answer the health history questions accurately. New York Life may verify this information through the Medical Information Bureau (MIB) and prescription drug databases.
- Beneficiary Designation: Clearly name who will receive the death benefit. You can name individuals, trusts, or organizations.
- Premium Payment: Select your payment frequency (monthly, quarterly, or annually). Setting up automatic bank drafts is often the most convenient method to ensure the policy does not lapse.
Connecticut-Specific Regulations and Protections
The Connecticut Department of Insurance (CID) regulates all life insurance policies sold within the state. These regulations provide several protections for AARP members:
The "Free Look" Period
In Connecticut, life insurance policies are subject to a "free look" period, typically lasting at least 10 to 30 days. This allows you to receive the physical policy, review the terms, and if you are unsatisfied for any reason, return it for a full refund of any premiums paid.
Grace Periods
If you miss a premium payment, Connecticut law requires a grace period (usually 30 or 31 days). During this time, the policy remains in force. If the insured dies during the grace period, the insurer will pay the benefit, minus the overdue premium.
Contestability Period
Like most states, Connecticut has a two-year contestability period. During the first two years of the policy, the insurer can investigate the original application for material misrepresentations if a claim is filed. After two years, the policy generally becomes "incontestable," meaning the insurer cannot deny a claim based on inaccuracies in the application, except in cases of fraud.
Why Connecticut Seniors Choose AARP Life Insurance
Connecticut residents often face a higher cost of living compared to the national average. In 2026, the average cost of a traditional funeral and burial in the Hartford or New Haven areas can easily exceed $12,000 when including cemetery fees and headstones.
Simplicity and Accessibility
The primary draw for AARP life insurance is the lack of a physical medical exam. For many seniors, the prospect of having a nurse visit their home for blood draws and vitals is a deterrent. By using "simplified issue" underwriting, AARP allows CT residents to secure coverage in days rather than the weeks or months required for fully underwritten policies.
Brand Trust
The AARP name carries significant weight. Seniors often feel more comfortable dealing with an organization they already belong to, rather than a generic insurance broker. The transparency of the New York Life partnership further solidifies this trust.
Portability
If a Connecticut resident decides to relocate to another state in retirement (such as moving to Florida or the Carolinas), their AARP life insurance policy is fully portable. The coverage remains active as long as premiums are paid, regardless of the policyholder's state of residence.
Common Pitfalls and Considerations
While AARP life insurance is a strong option for many, it is not always the most cost-effective choice for everyone in Connecticut.
1. The Cost of Convenience
Because AARP policies do not require a medical exam, New York Life assumes more risk. To compensate for this risk, the premiums can be higher than those for a "fully underwritten" policy. If you are in excellent health and do not mind a medical exam, you might find lower rates through a local Connecticut insurance broker who can shop multiple carriers.
2. Coverage Limits
The maximum coverage amounts ($50,000 for Permanent and $100,000 for Term) may be insufficient for someone who still has a mortgage or significant debts. These policies are primarily designed for final expenses and small legacy gifts, not for replacing a high income or paying off a large estate.
3. Term Expiration
The AARP Term Life policy ends at age 80. While it offers an option to convert to a permanent policy at that time, the premiums for the new permanent policy will be based on your age of 80, which can be prohibitively expensive for many seniors.
Managing Your Policy in 2026
In 2026, managing an AARP life insurance policy is largely digital. New York Life provides an online portal where Connecticut policyholders can:
- Update beneficiaries.
- Make one-time payments or change banking information.
- Download annual statements and tax documents.
- View the current cash value of permanent policies.
For those who prefer traditional methods, customer service remains available via phone and mail, with dedicated representatives familiar with the specific needs of the AARP demographic.
Frequently Asked Questions
Does AARP life insurance require a medical exam in Connecticut?
For the standard Term, Permanent, and Guaranteed Acceptance plans, a physical medical exam is generally not required. However, for Term and Permanent plans, you must answer health-related questions on the application. The Guaranteed Acceptance plan requires no health questions at all.
Is the AARP life insurance premium fixed or will it increase?
It depends on the plan. The Permanent (Whole) Life and Guaranteed Acceptance plans have fixed premiums that will never increase. The Term Life plan has premiums that increase every time you enter a new five-year age bracket (e.g., at age 55, 60, 65, etc.).
What happens if I move out of Connecticut?
Your AARP life insurance coverage is portable. If you move to another state, your policy remains in effect under the original terms and conditions. You simply need to update your address with New York Life to ensure you receive policy notices.
How do beneficiaries file a claim in Connecticut?
Beneficiaries should contact New York Life directly. They will need to provide a certified copy of the death certificate and complete a claim form. In Connecticut, insurers are required to process claims promptly once all documentation is received.
Can I have more than one AARP life insurance policy?
Yes, some members choose to combine policies—for example, having a Term policy for larger coverage during their 60s and a small Permanent policy specifically for funeral costs. However, the total coverage amount must remain within the limits set by New York Life.
Final Recommendations for Connecticut Residents
If you are a Connecticut resident seeking life insurance in 2026, AARP life insurance represents a reliable, simplified path to coverage. It is particularly well-suited for those who have minor health issues that might complicate traditional underwriting or for those who simply value the convenience of a quick application.
Before committing, it is advisable to:
- Calculate your actual need: Determine the current cost of final expenses in your specific part of Connecticut.
- Compare the long-term cost: If you are choosing Term insurance, look at what your premiums will be in 10 or 15 years, not just today.
- Review your health: If you are in near-perfect health, consider getting a quote for a fully underwritten policy to see if you can save on premiums.
To move forward, you can visit the official AARP life insurance website or call their service center to request a personalized quote based on your age and desired coverage amount.